


EN
3 Japanese Growth Stocks To Watch With Earnings Growth Up To 25%
Japan’s Nikkei has just dropped more than 6% after a sharp global selloff in AI related stocks, pulling many fast growers into a broad reset. That kind of shock often leaves solid Japanese high growth companies with heavy insider ownership trading at levels that do not fully reflect their prospects. This article walks through three such stocks from the screener so you can judge whether any deserve a spot on your watchlist.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders and analysts are broadly aligned on the outlook. However, if you want the names that matter most, these 27 high growth high conviction stocks are the strongest companies we've found.
Kotobuki Spirits (TSE:2222)
Kotobuki Spirits is a long established Japanese confectioner that produces and sells sweets and snack products, a business where insider led product launches and domestic distribution decisions directly shape growth. The group also runs an insurance agency operation and is valued at about ¥439.1b.
Kotobuki Spirits ties closely to the fast growing, high insider ownership theme through its confectionery arm, where earnings rose 11.8% last year and analysts see 13.2% yearly growth with a forecast 26% return on equity. That mix of growth, profitability and insider influence could matter a lot if a single assumption about demand and pricing shifts.
That kind of sensitivity to small shifts in assumptions is exactly why it is worth scanning the 3 key rewards and 1 important warning sign before you decide how Kotobuki Spirits fits your watchlist.

Micronics Japan (TSE:6871)
Micronics Japan builds test equipment for chipmakers, with the fast growing probe card operation generating about ¥84.9b of its ¥85.3b in segment revenue and tying it directly to the screener’s semiconductor growth theme. The much smaller TE business adds roughly ¥1.4b. The stock’s market value is about ¥336.2b.
Micronics Japan links tightly to the screener’s high growth story because its probe cards and test gear feed directly into expanding semiconductor production, with forecast earnings growth around 24.88% and net profit margins near 21.7%. That upside rests on what happens if a single pressure on memory chip testing demand shifts.
If that pressure shifts quickly, review the 2 key rewards and 2 important warning signs (1 is major!) to see how Micronics Japan’s growth story could accelerate or stall from here.

JX Advanced Metals (TSE:5016)
JX Advanced Metals produces copper and rare metal materials used in chips, electronics and industrial applications, with its Semiconductor Materials products giving direct exposure to fast growing tech demand. The group has a market value of about ¥2.32t.
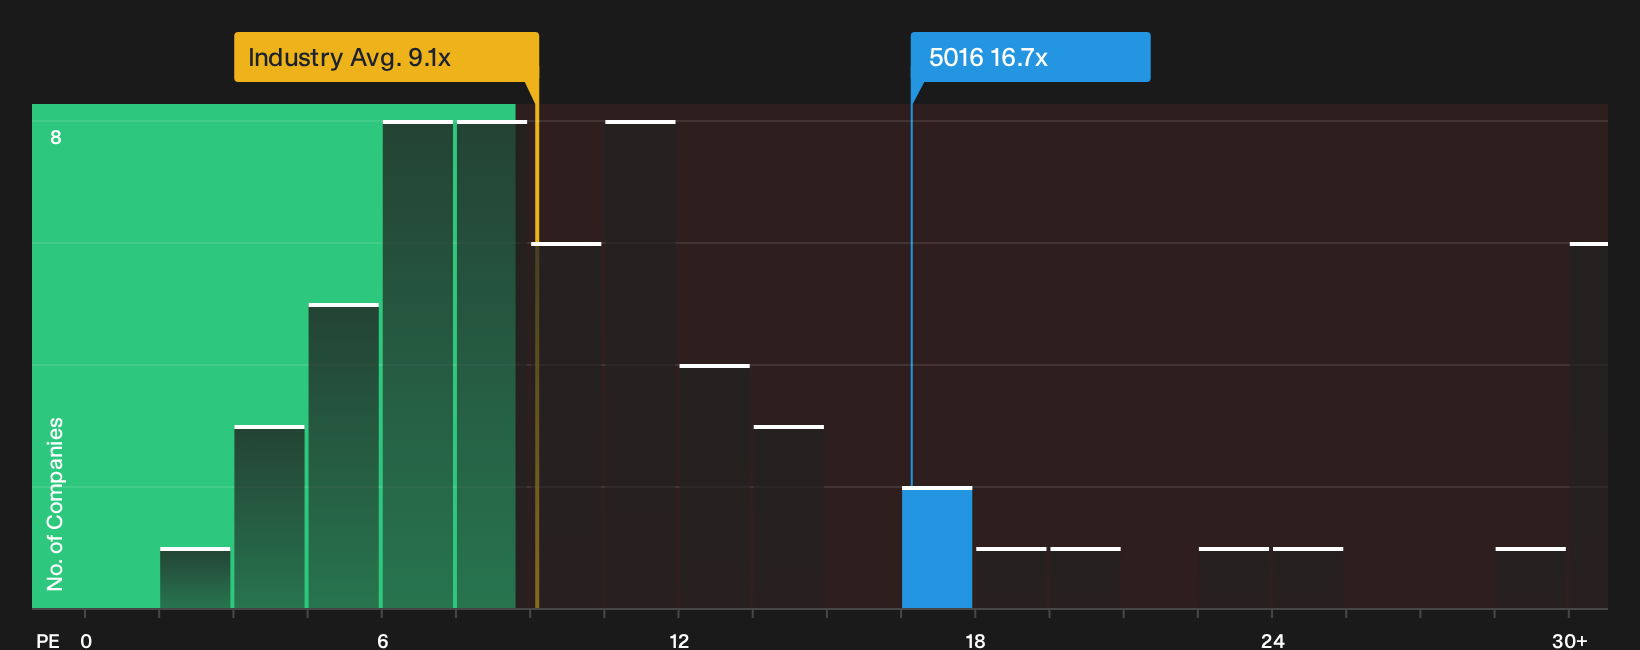
JX Advanced Metals ties into the fast growing, high insider ownership theme through its semiconductor materials exposure, where earnings are expected to rise 13.05% a year and recent profit growth of 91.8% backs that story. A P/E of 16.7x against an estimated fair 19.2x places a lot of weight on what happens if a single assumption about tech material demand shifts.
If that single assumption on tech material demand is wrong in either direction, read the 3 key rewards and 1 important warning sign to see what markets might be mispricing right now.
Seeking Alternatives Beyond Your Current Watchlist?
Fresh opportunities can move from quiet to breakout before most investors even notice. Scan these curated ideas while they are still under the radar for now, and consider them early.
- Target steady income streams by reviewing hand picked high yield candidates inside the 36 dividend fortresses before momentum buyers arrive and compress the starting yield.
- Explore opportunities in electrification and grid upgrades by checking the curated 42 power grid technology and infrastructure stocks while these stories are still priced for hesitation rather than conviction.
- Review developments in robotics adoption by scanning the focused 89 robotics and automation stocks before automation winners are fully recognized by broader institutional money.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com