


EN
Automatic Data Processing (ADP) Following Earnings And PNC Deal Is It Already Fully Valued
Automatic Data Processing (ADP) drew fresh attention after reporting first quarter figures and unveiling a partnership with PNC Bank that embeds its payroll and HR tools directly into PNC's digital banking platform.
Recent trading suggests momentum has been building in Automatic Data Processing, with a 30-day share price return of 14.9% and a 90-day move of 11.8%. The 1-year total shareholder return of 22.8% reflects the longer run impact of its earnings updates and partnership news.
Scan how Automatic Data Processing compares to other established cash generators in our 39 high quality undervalued stocks that pair solid fundamentals with potential mispricing.
The recent jump in Automatic Data Processing can be read two ways, either as a clean response to stronger earnings and the PNC rollout, or as sentiment running ahead of itself. Which story do the valuation numbers support next?
Most Popular Narrative: 13% Overvalued
On the latest numbers, the narrative fair value of $268 for Automatic Data Processing sits below the recent close of $303.35, which tilts the story toward a premium pricing debate rather than a bargain hunt.
1. Payroll and HR services leader with highly recurring, sticky revenue and margins that have expanded steadily over a decade. 2. 51 consecutive dividend increases; dividend growth (~12% p.a. over 10 years) has tracked EPS growth.
See why 1 investors see Automatic Data Processing as 13% overvalued.
The author of this narrative, according to DKDGI, anchors that $268 view on a three stage dividend discount model that uses a current dividend of $6.80, an 8% annual growth rate for the first decade, a fade to 3% in the following 10 years, and a 7.52% required return. That framework also assumes a payout ratio around 50% to 55% of free cash flow and almost no net debt, while deliberately leaving buybacks out of the equation to keep the estimate on the conservative side.
Under that lens, the recent rally in Automatic Data Processing pushes the share price meaningfully above this narrative fair value, which suggests investors are currently paying up for qualities such as recurring revenue, high reported return on equity, and a long dividend track record rather than buying primarily on a discount to intrinsic worth.
Result: Fair Value of $268 (OVERVALUED)
Still, the story around Automatic Data Processing can change quickly if client retention drops or if earnings, excluding client fund interest, stop progressing.
Find out about the key risks to this Automatic Data Processing narrative.
Another View: Cash Flows Paint Automatic Data Processing As Undervalued
While the narrative fair value pegs Automatic Data Processing at $268, the SWS DCF model reaches a different conclusion. On those cash flow assumptions, ADP at $303.35 screens as about 10.4% below an estimated $338.40 value. That raises a clear question for investors: Which story feels more convincing to you next?
Look into how the SWS DCF model arrives at its fair value.
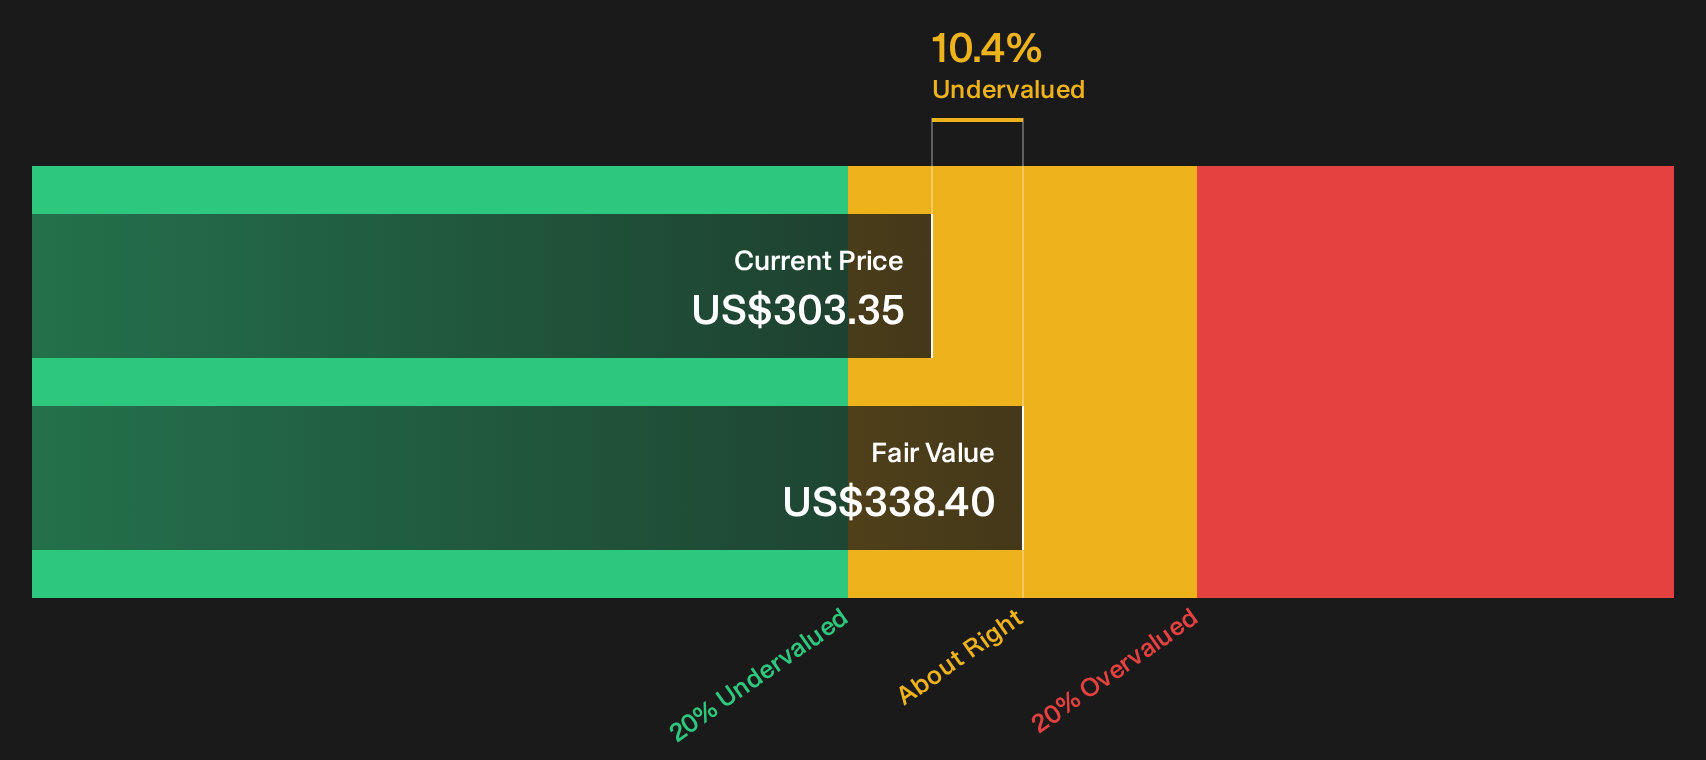
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Automatic Data Processing for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Automatic Data Processing is clearly split, which is exactly why it pays to move quickly and test the numbers yourself. To see which potential bright spots others are focused on right now, review the 4 key rewards.
Looking for more investment ideas beyond Automatic Data Processing?
If you stop at Automatic Data Processing, you risk missing other opportunities that fit your style even better, so put a few alternatives on your radar today.
- Target stronger potential value by scanning a curated pool of financially solid stocks that still look mispriced using the 39 high quality undervalued stocks.
- Build more resilient income by focusing on companies that combine higher yields with balance sheet strength through the 8 dividend fortresses.
- Prioritise durability by tracking businesses with healthier finances and cleaner fundamentals via the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com