


EN
Is Kier Group (LSE:KIE) Fully Valued On Its UK Health Security Campus Win?
Why Kier Group’s UK Health Security Campus Role Matters For Investors
Kier Group (LSE:KIE) has secured a Pre Construction Services Agreement for the H50 high containment building at the UK Health Security Campus, part of a £3.52b programme in Harlow.
The appointment links Kier Group to a long dated public sector project focused on advanced laboratory facilities for high risk pathogens, with early works planned from 2028 and full campus completion targeted for 2038.
Kier Group’s role at the UK Health Security Campus comes at a time when momentum in the shares has been building. A 30 day share price return of 7.38% has contributed to a 45.13% year to date rise and a 3 year total shareholder return of 235.17%.
Scan beyond Kier Group and see how other contractors tied to long term public projects stack up in our hand picked list of solid balance sheet and fundamentals (9 results)
The recent jump in Kier Group raises a simple tension. Are investors finally catching up with what the business is already delivering, or has sentiment raced ahead of what the current valuation can justify?
Most Popular Narrative: 10% Undervalued
The most followed valuation view puts Kier Group’s fair value at £3.49 per share, modestly above the last close at £3.14. This frames today’s move in the context of a stock already priced for solid execution rather than a deep discount.
The four growth engines in water, energy, defence and healthcare are expected to contribute roughly £900m to £1b of additional revenue by FY29 after HS2 runoff. This could support the mid single digit revenue growth and adjusted operating margin ambition.
The shift toward around 95% of project revenues on cost plus or two stage contracts, and around 60% on cost reimbursable models, concentrates future activity in lower fixed price risk work. This could support more stable net margins and earnings.
See why 24 investors see Kier Group as 10% undervalued.
Result: Fair Value of £3.49 (UNDERVALUED)
Still, the Kier Group story can shift quickly if UK infrastructure programmes are delayed or if fire and cladding remediation cash costs are heavier than planned.
Find out about the key risks to this Kier Group narrative.
Another View On Kier Group’s Valuation
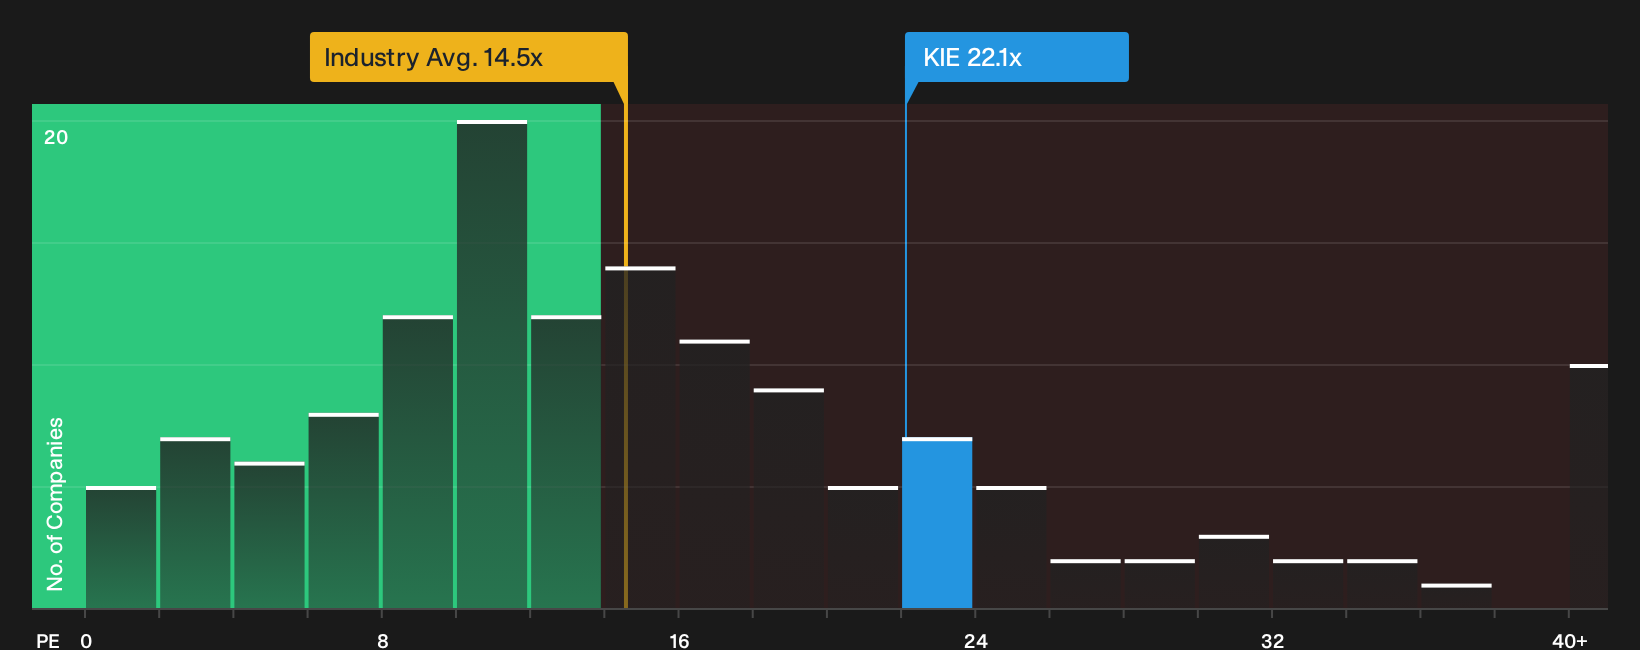
On simple earnings multiples, Kier Group screens differently. The shares trade on a P/E of 22.1x, compared with 14.5x for the European Construction group and 14.7x for close peers, while the fair ratio sits at 22.9x. That points to less obvious multiple based upside. Which lens do you trust more?
Investors who want to see how a cash flow lens compares to the current earnings multiple can walk through our DCF workup in detail in the See what the numbers say about this price — find out in our valuation breakdown.
For a visual snapshot of how that earnings multiple stacks up against the sector, take a look at the latest
Next Steps
Mixed signals on Kier Group so far. If you want to move fast and reach your own view, start by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Kier Group?
If Kier Group has sharpened your focus on quality, do not stop here. Broader research now can shape the opportunities you actually act on next.
- Target resilient balance sheets by scanning companies with low debt and sturdy fundamentals through our list of solid balance sheet and fundamentals (9 results).
- Hunt for mispriced opportunities by checking the 15 high quality undervalued stocks that pair quality metrics with discounted valuations.
- Build a smoother ride in volatile markets by focusing on the 4 resilient stocks with low risk scores that score well on financial strength and earnings stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com