


EN
How Investors Are Reacting To East West Bancorp (EWBC) Cross Border Payments Expansion
- East West Bancorp is expanding its cross border payments platform across Hong Kong and mainland China and is building an in house registered investment adviser to grow fee based wealth management revenue.
- The push toward a more integrated Asia payments network and proprietary wealth platform signals a tilt toward recurring fee income alongside traditional lending.
- We will now look at how East West Bancorp's investment narrative could be shaped by its expanded cross border payments focus.
Scan other banks pursuing fee heavy business models and cross border flows with our curated list of list of solid balance sheet and fundamentals (24 results)
East West Bancorp Investment Narrative Recap
To own East West Bancorp, you need to believe its U.S. to Asia banking niche can keep supporting loan, deposit, and fee growth while capital and credit stay disciplined. The near complete Hong Kong integration and new mainland China payment rails reinforce that thesis by aiming to deepen commercial relationships and support fee based income.
The main short term swing factor is still deposit pricing and funding costs, especially on rolling CDs, with cross border fees a helpful but smaller counterweight. The biggest risk remains any deterioration in credit quality that pushes the allowance for credit losses higher and squeezes net income.
The build out of East West Bancorp's in house registered investment adviser is the most relevant announcement here. A proprietary wealth platform sits alongside the expanding payments network and can support more stable fee streams compared with transaction heavy FX or derivatives activity that already shows quarter to quarter volatility.
Execution risk is real, since standing up an advisory business and scaling an Asia focused payments network both add expense and operational complexity. Management's ability to deliver on these projects while holding capital ratios and asset quality near current levels will likely affect how much the mix of recurring advisory fees and cross border payments matters for how earnings respond to future funding and credit cycles.
East West Bancorp's current analyst narrative points to US$3.9b in revenue and US$1.7b in earnings by 2029, based on 10.3% yearly revenue growth and an earnings increase of US$300m from US$1.4b today.
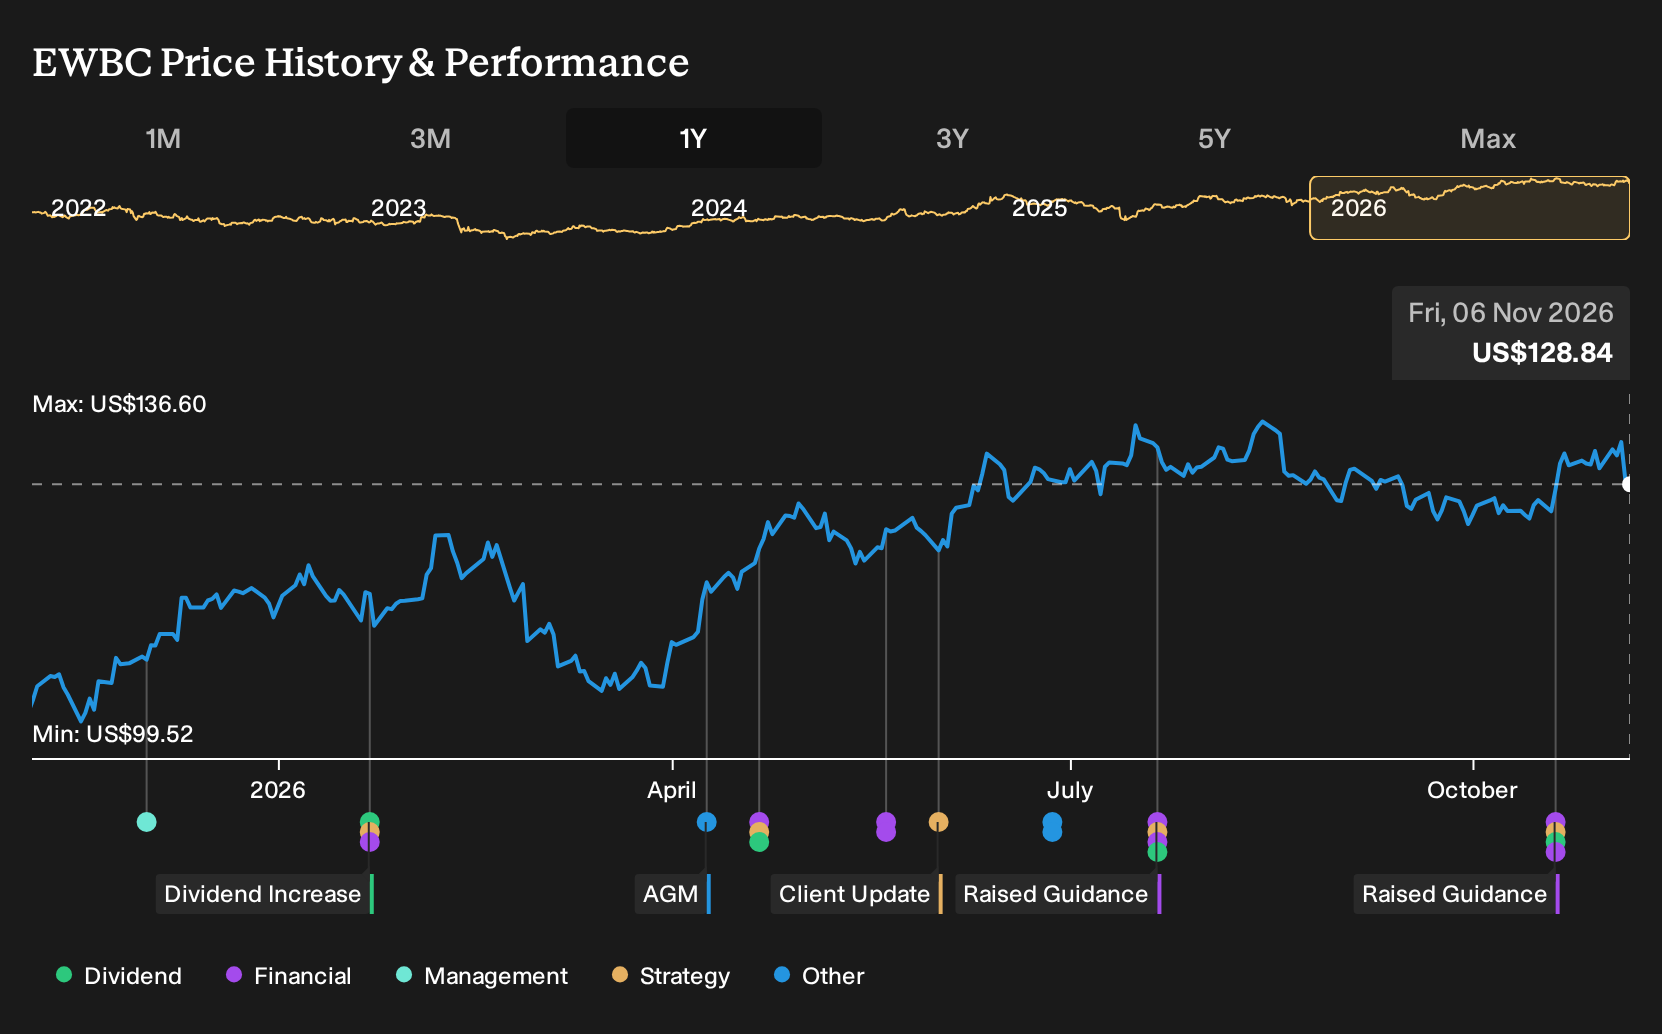
Uncover why East West Bancorp's fair value indicates a 16% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$150 to about US$268, with most estimates clustering in the middle buckets. That is a wide band for the same East West Bancorp story. Set that against deposit competition, fee volatility, and cross border growth catalysts, then compare these perspectives before deciding how you see it.
Explore 2 other East West Bancorp fair value estimates, including one that suggests it could be worth just $150.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your East West Bancorp research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for East West Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate East West Bancorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond East West Bancorp?
If the East West Bancorp story has sharpened your thinking about fee income, balance sheet strength, and credit risk, it can be useful to test that same lens on a broader watchlist using the Simply Wall St Screener.
- For investors hunting for strong businesses priced below what their fundamentals might justify, start with a curated pool of 39 high quality undervalued stocks that already clear quality and valuation checks.
- If capital preservation and steadier risk profiles matter most to you, focus on a 29 resilient stocks with low risk scores that filters for companies with more resilient metrics and fewer red flags.
- To uncover potential future leaders that are not yet widely followed, scan a 19 high quality undiscovered gems that highlights high quality operators still flying under the radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com