


EN
What NeoGenomics Stock's Narrower Loss Means For Shareholders
- NeoGenomics reported third quarter 2026 sales of US$209.25 million and a net loss of US$7.55 million, with year-to-date revenue of US$597.58 million and a US$22.41 million loss.
- Loss per share for both the quarter and the first nine months stayed in negative territory but narrowed versus the prior year, which reflects cost discipline alongside demand for the oncology testing portfolio.
- This article will look at how NeoGenomics' investment narrative is affected by the sharply narrower quarterly net loss reported in the latest results.
Scan beyond NeoGenomics' shrinking losses and spot other healthcare testing and diagnostics players that combine revenue traction with tighter cost control in our curated list of solid balance sheet and fundamentals (24 results)
NeoGenomics Investment Narrative Recap
To own NeoGenomics, you need to believe the oncology testing platform can turn rising sales into a stable, profitable lab network over time. The latest quarter helped that case at the margin. Revenue reached US$209.25 million with a quarterly loss of US$7.55 million, which shows cost discipline is starting to matter for the P&L.
The key near term catalyst is continued uptake of higher value NGS and liquid biopsy services while keeping the cost base in check. The main risk is simple. Profitability is not yet in sight and the business still carries a high fixed cost structure, so any slowdown in test volume or pricing could quickly widen losses again.
The most relevant recent development is NeoGenomics' plan to appear at the Stephens Annual Investment Conference and the Piper Sandler Healthcare Conference in November and December 2026. These events give management a platform to explain the third quarter improvement in losses and how oncology testing demand is feeding through to the income statement.
For you as a shareholder, those fireside chats are a chance to assess execution against the big catalysts. That includes progress on NGS and liquid biopsy ramps, the impact of reimbursement work on revenue quality, and how management thinks about reaching breakeven while competition in oncology diagnostics and MRD testing remains intense.
NeoGenomics' current earnings are a loss of US$32.3 million. Analysts' consensus points to earnings of US$64.0 million on revenue of US$1.0 billion by 2029, which implies an 8.8% yearly revenue growth rate and an earnings swing of about US$96 million from today.
Uncover why NeoGenomics' fair value indicates a 36% potential upside to its current price, which could narrow quickly.
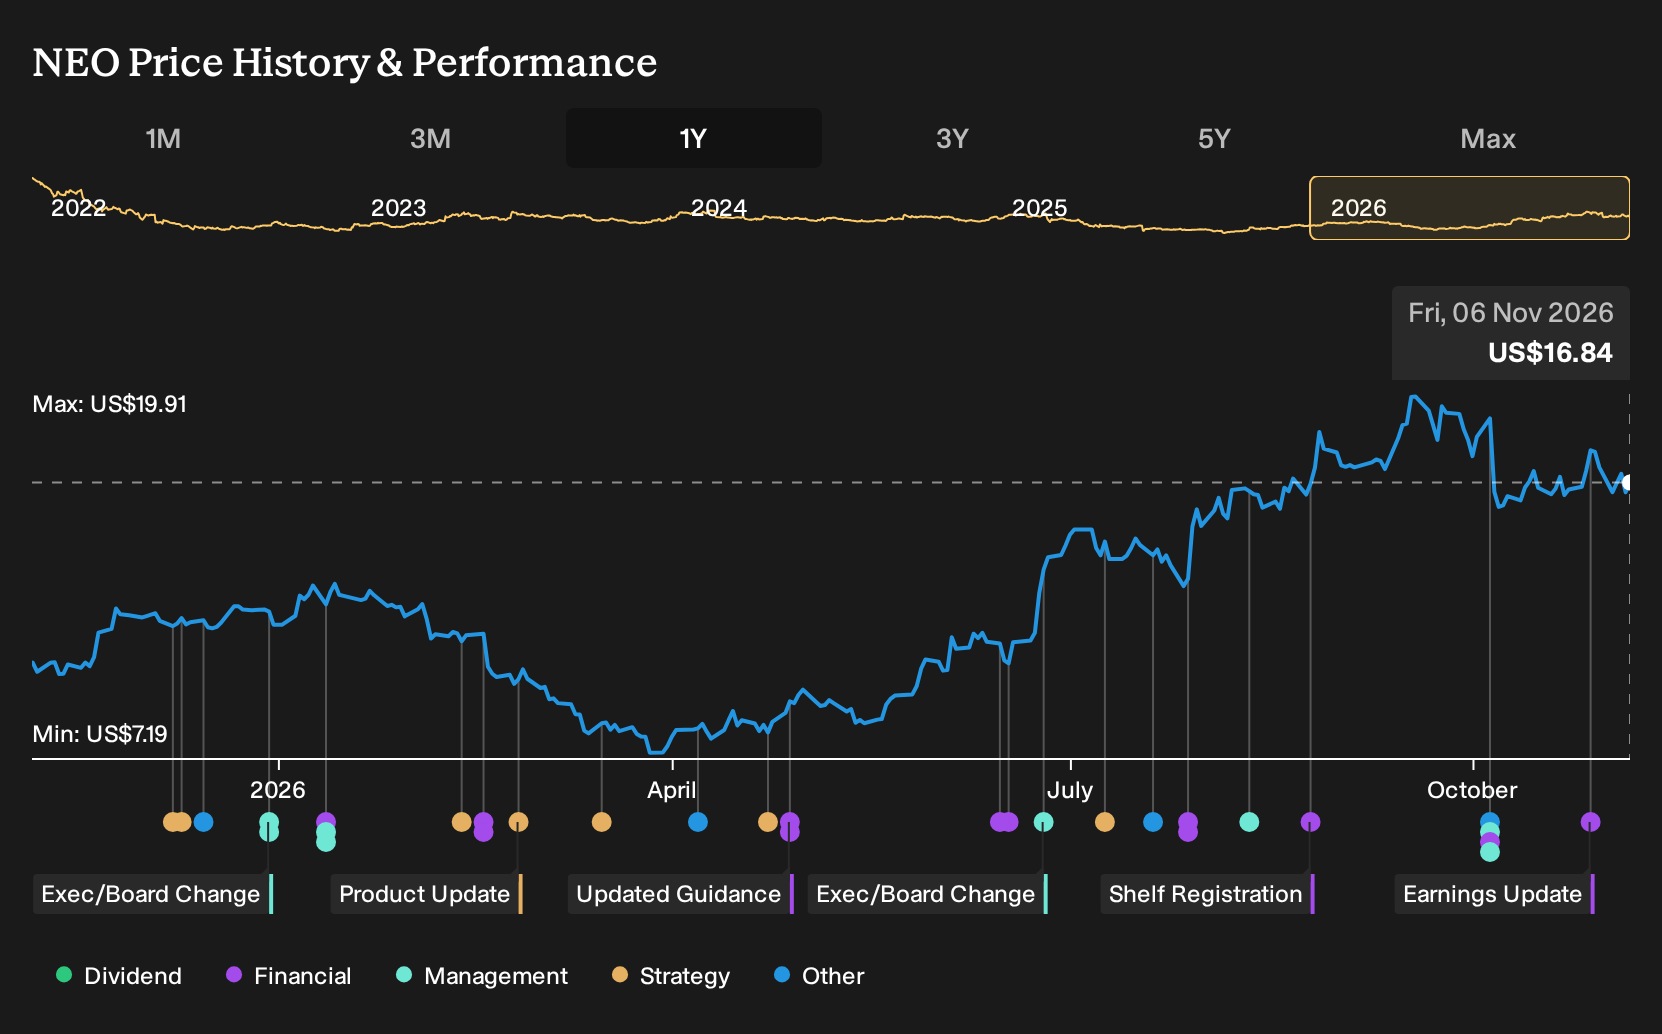
Exploring Other Perspectives
Some of the most optimistic analysts focus on margin expansion at NeoGenomics rather than revenue alone. Before this quarter, they were sketching out about US$1.0b of turnover and roughly US$67.1 million of earnings by 2029. You can read this new loss improvement as either fuel for that story or as a reason to rethink it. Views vary widely, so compare these older forecasts with your own expectations and assess which version of the future appears more realistic.
Explore another NeoGenomics fair value estimate, including one that suggests there could be as much as 92% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your NeoGenomics research is our analysis highlighting 1 important warning sign that could impact your investment decision.
- See our latest analysis for NeoGenomics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NeoGenomics' overall financial health at a glance.
Looking For More Ideas Beyond NeoGenomics?
Once you have a view on NeoGenomics, it often helps to line it up against a wider watchlist. The Simply Wall St Screener can surface other stocks that match the kind of balance sheet strength, valuation profile, or income focus you want to compare.
- If you want potential mispricing with quality in mind, scan a curated group of companies trading on compelling fundamentals through our 39 high quality undervalued stocks.
- For investors who care more about resilience than excitement, filter for businesses with sturdier finances and lower risk profiles by using the 29 resilient stocks with low risk scores.
- If you are building a watchlist of future candidates rather than widely followed large caps, broaden your radar with a 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com