


EN
Does Record Quarter Change The Bull Case For IMAX Stock (IMAX)?
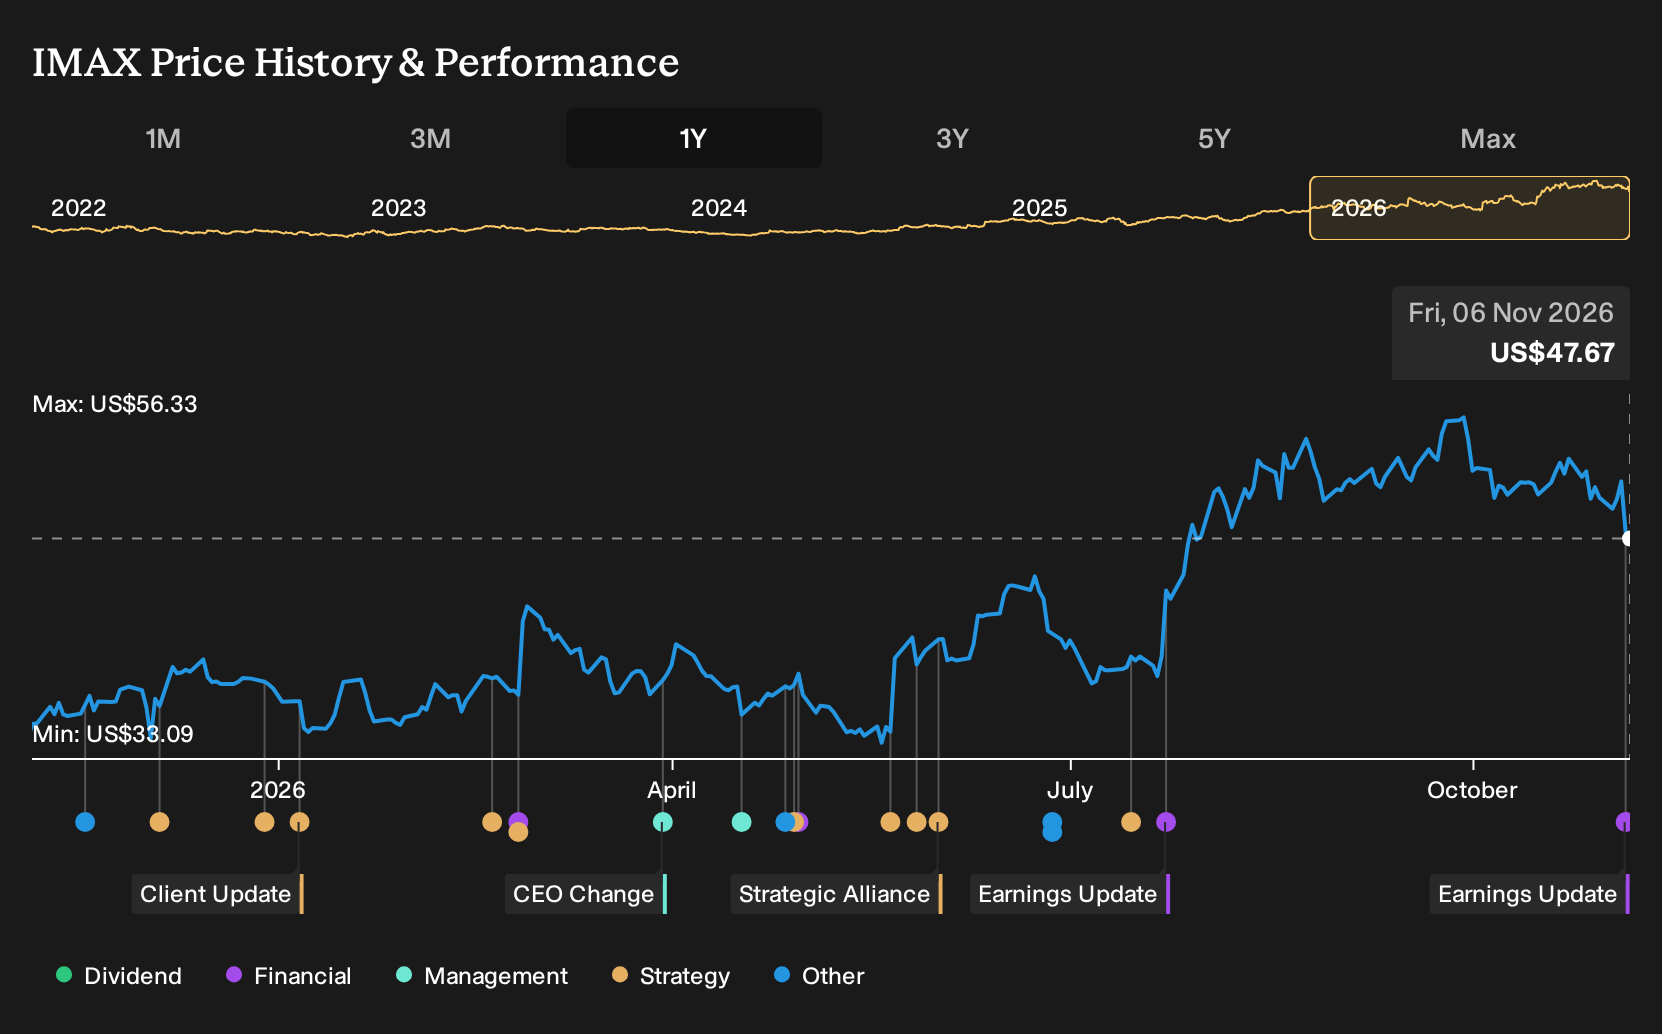
- IMAX reported third quarter 2026 results with revenue of US$174.55 million and net income of US$113.81 million, with basic earnings per share from continuing operations of US$2.07.
- The quarter highlighted how IMAX's premium format box office performance, strong Content Solutions activity, and rapid system signings can translate into high earnings and record profitability.
- We will look at how IMAX's investment narrative is affected by record quarterly earnings and what that means for longer term expectations.
IMAX Investment Narrative Recap
To own IMAX, you need to believe the premium large format model can keep filling high value seats and that the system network and content slate stay busy enough to support strong earnings. The record third quarter, with US$174.55 million in revenue and US$113.81 million in net income, reinforces that the platform can convert a strong release calendar into very high profitability.
The key near term catalyst is still system expansion and utilisation. Management has 105 new systems signed year to date, and the recent results show what high box office can do for margins. The biggest risk is unchanged. A softer slate or weaker cinema attendance would hit box office driven revenue, slow new installs and expose how dependent IMAX is on blockbuster cycles.
The most relevant update is IMAX lifting its 2026 EBITDA margin guidance to 50% or more, two years earlier than previously targeted, on the back of record quarterly performance. That guidance ties directly to what investors just saw in the third quarter numbers, where strong box office and Content Solutions activity flowed through cleanly to the bottom line.
For catalysts, this margin target sharpens the focus on execution around new screens and a heavier IMAX optimised pipeline. The firm is signing systems quickly, with 105 year to date and a pipeline of about 150 potential locations, and is leaning into blockbuster and local language titles. The risk is that such high profitability guidance leaves less room for disappointment if release schedules soften or attendance trends favour at home entertainment.
What The IMAX Analyst Case Is Really Asking You To Believe
Consensus forecasts around IMAX sketch out a business that is expected to grow into its current premium multiple rather than rely on another one off record quarter. Analysts are baking in 7.8% annual revenue growth over the next 3 years and a rise in profit margins from 9.8% today to 20.1% in that window. Together, these projections imply a company that becomes far more earnings heavy on every incremental dollar of box office and service income.
On the earnings line, the group expects profit to move from US$40.9 million today to US$104.5 million by 2029, which is roughly a 2.6x step up in absolute dollar terms and underpins the raised margin guidance investors just heard. That profile feeds into the current P/E math, where the stock reportedly trades on 70.3x today and would need to settle around 42.7x those 2029 earnings for the consensus price target to hold, still almost double the 21.7x P/E cited for the wider US Entertainment peer group.
Those same estimates plug into a revenue line of US$520.6 million by 2029 and earnings of US$104.5 million, with analysts using discount rates around 9% to frame what that might be worth in today’s dollars. Shareholders are effectively being asked to pay a premium valuation now for a future state that includes a denser IMAX screen footprint, higher utilisation of the installed base, and a more diversified mix of content and licensing income feeding through at much higher profitability.
IMAX's narrative projects US$520.6 million revenue and US$104.5 million earnings by 2029. This rests on 7.8% yearly revenue growth and an earnings increase of roughly US$63.6 million from US$40.9 million today.
Uncover why IMAX's fair value indicates a 24% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view leans hard into technology risk. Those more cautious analysts worry that IMAX’s complex projection hardware and new at home formats could chip away at the cinema premium, even while they were still pencilling in about US$531.7 million of revenue and US$113.5 million in earnings by 2029. That is already more optimistic on profit than consensus, yet it still supports a lower price target. This shows how far opinions can stretch. It helps to compare several narratives and decide which assumptions you find more realistic, especially now that fresh quarterly results are on the table and may prompt revisions.
Explore 2 other IMAX fair value estimates, including one that suggests it could be worth just $59.17!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis.
- A great starting point for your IMAX research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for IMAX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IMAX's overall financial health at a glance.
Looking For More Investment Ideas Beyond IMAX?
Once the IMAX story is clear in your mind, broaden the opportunity set with a few focused stock lists built around quality, valuation, and resilience. The Simply Wall St Screener can help you scan the market quickly and keep your watchlist fresh.
- If you want potential mispricing on your side, start with companies that combine strong fundamentals with attractive valuations through our 39 high quality undervalued stocks.
- For investors who care about balance sheet strength first, filter for businesses with robust finances using this list of solid balance sheet and fundamentals (24 results).
- If capital preservation is front of mind, narrow the universe to steadier profiles by reviewing a 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com