


EN
Did Raised Revenue Guidance Just Shift BigBear.ai's (BBAI) Investment Narrative?
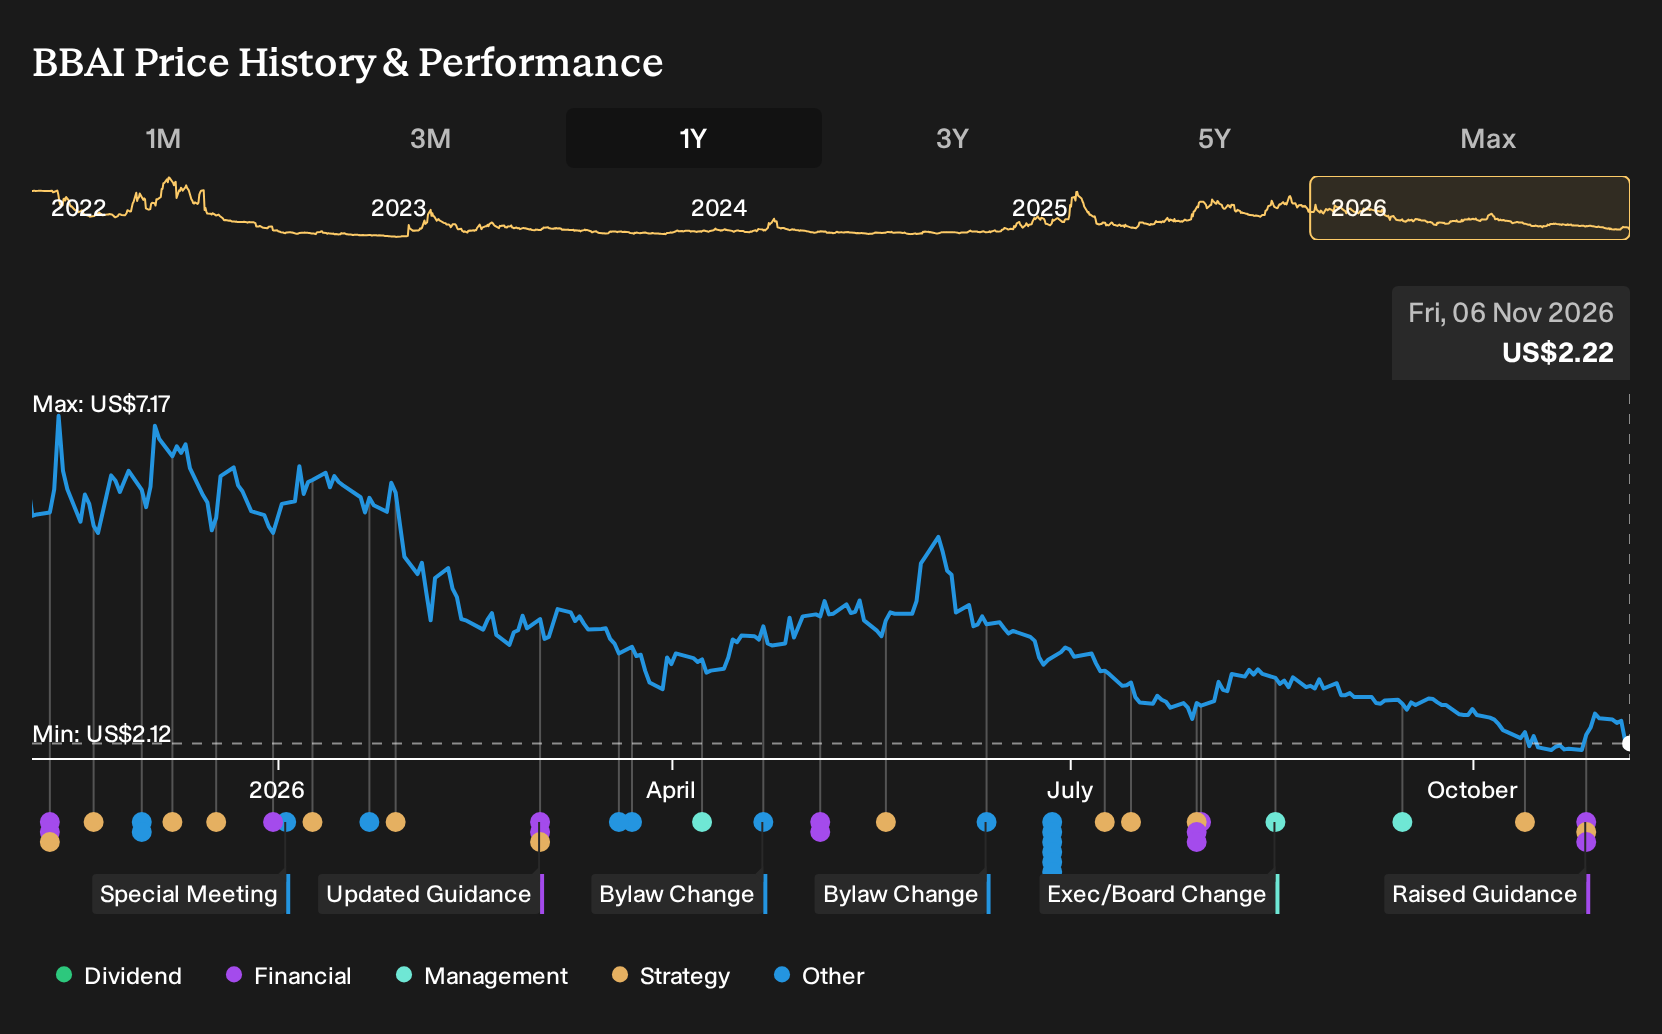
- BigBear.ai Holdings reported third quarter 2026 sales of US$43.58 million and a goodwill impairment charge of US$76.74 million, resulting in a net loss of US$91.85 million and basic loss per share from continuing operations of US$0.19.
- Despite the impairment and losses, BigBear.ai Holdings raised its 2026 revenue guidance to a range of US$150 million to US$165 million following contract wins and demand for secure, mission specific AI platforms.
- We will now examine how BigBear.ai Holdings' raised 2026 revenue guidance could reshape the existing investment narrative around contract driven growth.
See how BigBear.ai Holdings fits into the broader AI push by comparing it with hand picked 41 AI small caps that are already capturing demand for mission specific and secure platforms.
BigBear.ai Holdings Investment Narrative Recap
To own BigBear.ai Holdings, you need to believe the business can turn growing interest in secure, mission specific AI into steadier revenue and, over time, a path toward better earnings quality. The raised 2026 revenue guidance suggests management currently sees enough contracted work and pipeline visibility to support that view in the near term.
The short term swing factor is execution on awarded government and enterprise contracts, where timing and scope can move results meaningfully. The biggest immediate risk remains sustained losses and noncash charges like goodwill impairments, which keep pressure on margins and highlight the need for tighter cost discipline while funding R&D and acquisitions.
The raised full year 2026 revenue guidance to US$150 million to US$165 million sits at the center of this update. That move ties directly to recent contract wins and demand for secure AI platforms, which matter because this business has historically faced lumpy revenue tied to government procurement cycles and milestone timing.
For you as a shareholder, the key question is whether this higher range reflects a more durable shift in backlog conversion or just timing. If BigBear.ai Holdings converts its expanded contract backlog into consistent billings while holding the line on expenses, that could support the existing catalyst narrative, although the firm still reports sizeable losses and remains unprofitable.
BigBear.ai Holdings' current narrative is built on analysts expecting revenue to grow by 15.6% per year. From this, they project 2029 revenue of US$219.2 million and earnings of US$16.7 million in that same year, compared with a loss of US$180.2 million today that would need to swing by about US$196.9 million for those consensus earnings to be reached.
Uncover why BigBear.ai Holdings' fair value indicates a 46% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The alternate narrative hangs on contract momentum. Bullish analysts were already assuming revenue of about US$219.7 million and earnings of US$16.8 million by 2029, paired with a very high 160.4x P/E to reach their targets. After BigBear.ai Holdings' goodwill impairment and higher guidance, those upbeat views might shift, and you can compare them with your own expectations.
Explore 3 other BigBear.ai Holdings fair value estimates, including one that suggests as much as 58% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your BigBear.ai Holdings research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BigBear.ai Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BigBear.ai Holdings' overall financial health at a glance.
Looking for more investment ideas beyond BigBear.ai Holdings?
Once you have a view on BigBear.ai Holdings, it can help to compare that thesis with other opportunities that match your risk profile, income needs, or preference for balance sheet strength using the Simply Wall St Screener.
- If you want early stage upside with tighter fundamentals, start with a curated group of 9 elite penny stocks with strong financials that already show stronger financial underpinnings than typical micro caps.
- For readers focused on quality at a measured price, scan through a 39 high quality undervalued stocks that combine healthier cash flows with more robust financial positions.
- If capital preservation and resilience matter most to you, focus on a 29 resilient stocks with low risk scores that screen for companies with more resilient business profiles and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com