


EN
Why Omnicom Group (OMC) Is Back In The Spotlight
Omnicom Group (OMC) is back in focus after two developments: the appointment of Tom Schwenger to lead Omnicom Health marketing and fresh recognition as a leader in global media management.
Recent headlines around Omnicom Group have landed alongside a sharp 15.36% 30 day share price return and a 6.29% gain over the past week. The 1 year total shareholder return of 21.10% and 5 year total shareholder return of 49.80% point to momentum that has been building rather than fading.
Spot fresh momentum in Omnicom Group, then widen your watchlist with 39 high quality undervalued stocks that combine resilient cash flows with balance sheet strength.After a sharp run in Omnicom Group, recognition in media and a fresh healthcare hire pull the story in one direction, while ETF selling and higher expected interest costs tug in another. Does the current valuation still leave enough upside for the risk?
Most Popular Narrative: 15% Undervalued
On the most followed view of Omnicom Group, a fair value of $102 sits above the last close at $86.37. This puts current pricing at a discount while still acknowledging real execution risks.
The expanded cost reduction and portfolio pruning program, which now targets disposals of about US$3.5b to US$3.6b of largely lower growth revenue and gross cost synergies of US$1.5b by mid 2028, is designed to support higher Core Operations margins and EBITA growth as remaining businesses scale.
See why 43 investors see Omnicom Group as 15% undervalued.
Result: Fair Value of $102 (UNDERVALUED)
Still, the Omnicom Group story can shift quickly if higher borrowing costs bite harder than expected or if regional weakness in Asia Pacific and the Middle East and Africa persists.
Find out about the key risks to this Omnicom Group narrative.
Another Angle On Omnicom Group’s Valuation
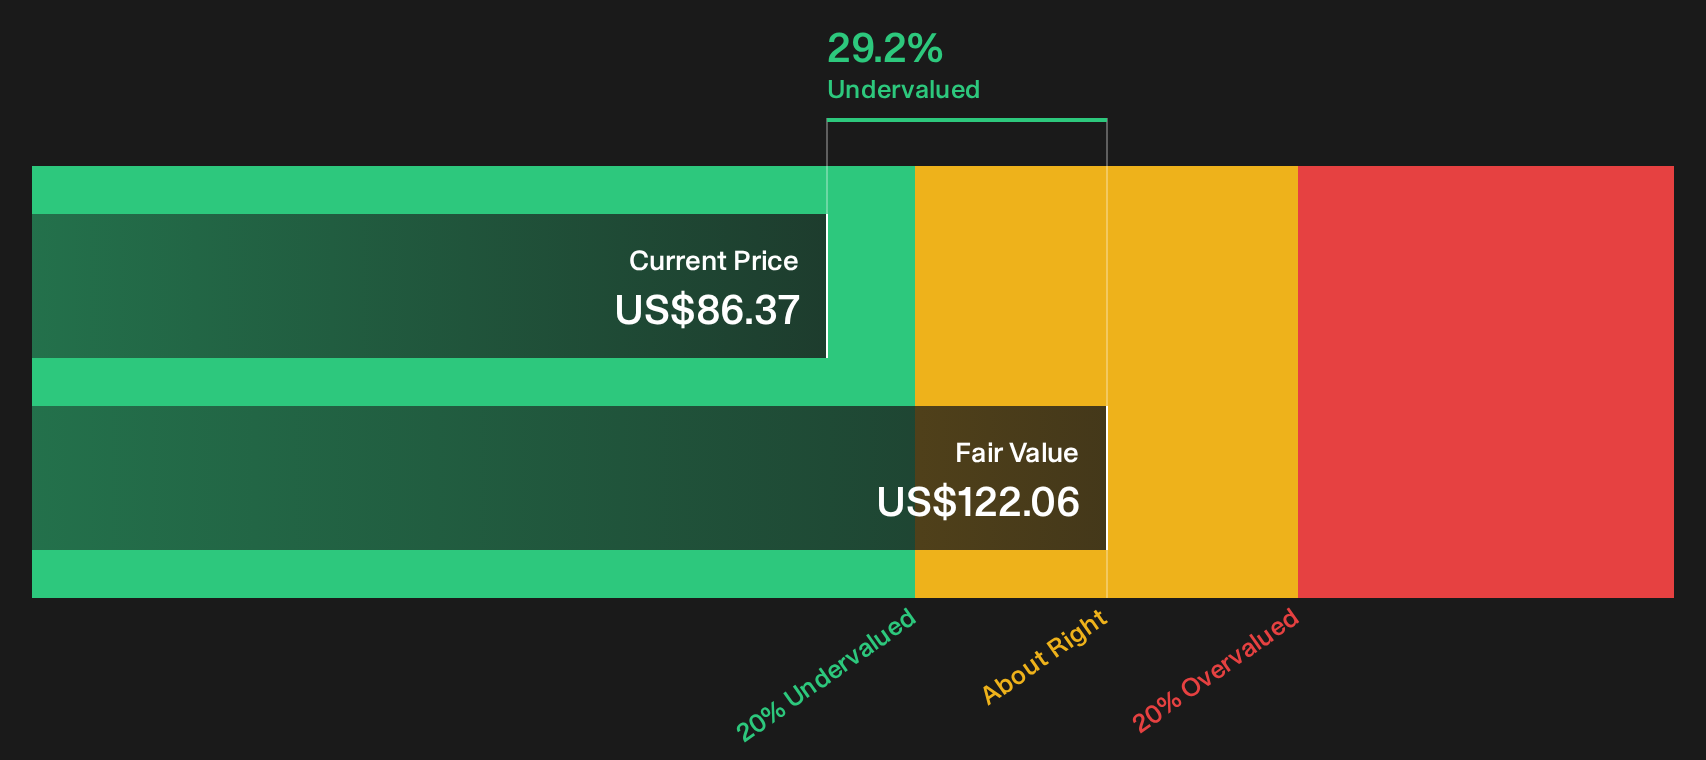
The SWS DCF model presents a different perspective on Omnicom Group. It suggests the shares trade about 29.2% below an estimated future cash flow value of $122.06, which points to an undervalued setup rather than a fully priced stock. Are cash flows telling you a different story compared with earnings multiples?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed feelings about Omnicom Group after that DCF view. If you want to move quickly and build your own stance from the ground up, start by weighing 2 key rewards and 5 important warning signs
Looking for more investment ideas beyond Omnicom Group?
If Omnicom Group has sharpened your focus, do not stop here. Fresh opportunities emerge constantly and the right filter can change your watchlist fast.
- Target dependable compounding by scanning for income opportunities in the 8 dividend fortresses that aim to pair cash payouts with underlying resilience.
- Spot resilient balance sheets early by running your next candidates through the list of solid balance sheet and fundamentals (24 results) before you commit serious capital.
- Hunt for future market favorites by starting with the 19 high quality undiscovered gems that many investors have not yet placed on their radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com