


EN
Should Raised 2026 Guidance Require Action From Legrand Stock Investors?
- Legrand reported nine month 2026 sales of €8,329.4m, net income of €1,067m and higher basic EPS from continuing operations compared with a year earlier.
- The group combined earnings progress with seven acquisitions in data center, power and connected health, and then raised its 2026 organic sales growth and margin targets.
- Next, the focus shifts to how Legrand's upgraded 2026 growth guidance may reshape the longer term investment narrative that investors have been using.
Scan beyond Legrand and line up other power, data center and infrastructure plays on your radar with the hand picked 42 power grid technology and infrastructure stocks.
Legrand Investment Narrative Recap
To own Legrand, you need to believe its pivot toward data centers, power infrastructure and connected health can offset softer construction-exposed activity and purchase cost pressure. The raised 2026 guidance points to management leaning into that mix shift. The key near term catalyst remains execution in AI driven data center projects, where content per megawatt is central to the story.
The biggest operational risk still sits in two places. First, that AI data center investment or content per megawatt ends up below current ambitions. Second, that weak European construction and higher input costs continue long enough to compress margins, especially as Legrand integrates recent acquisitions and aims for its margin targets.
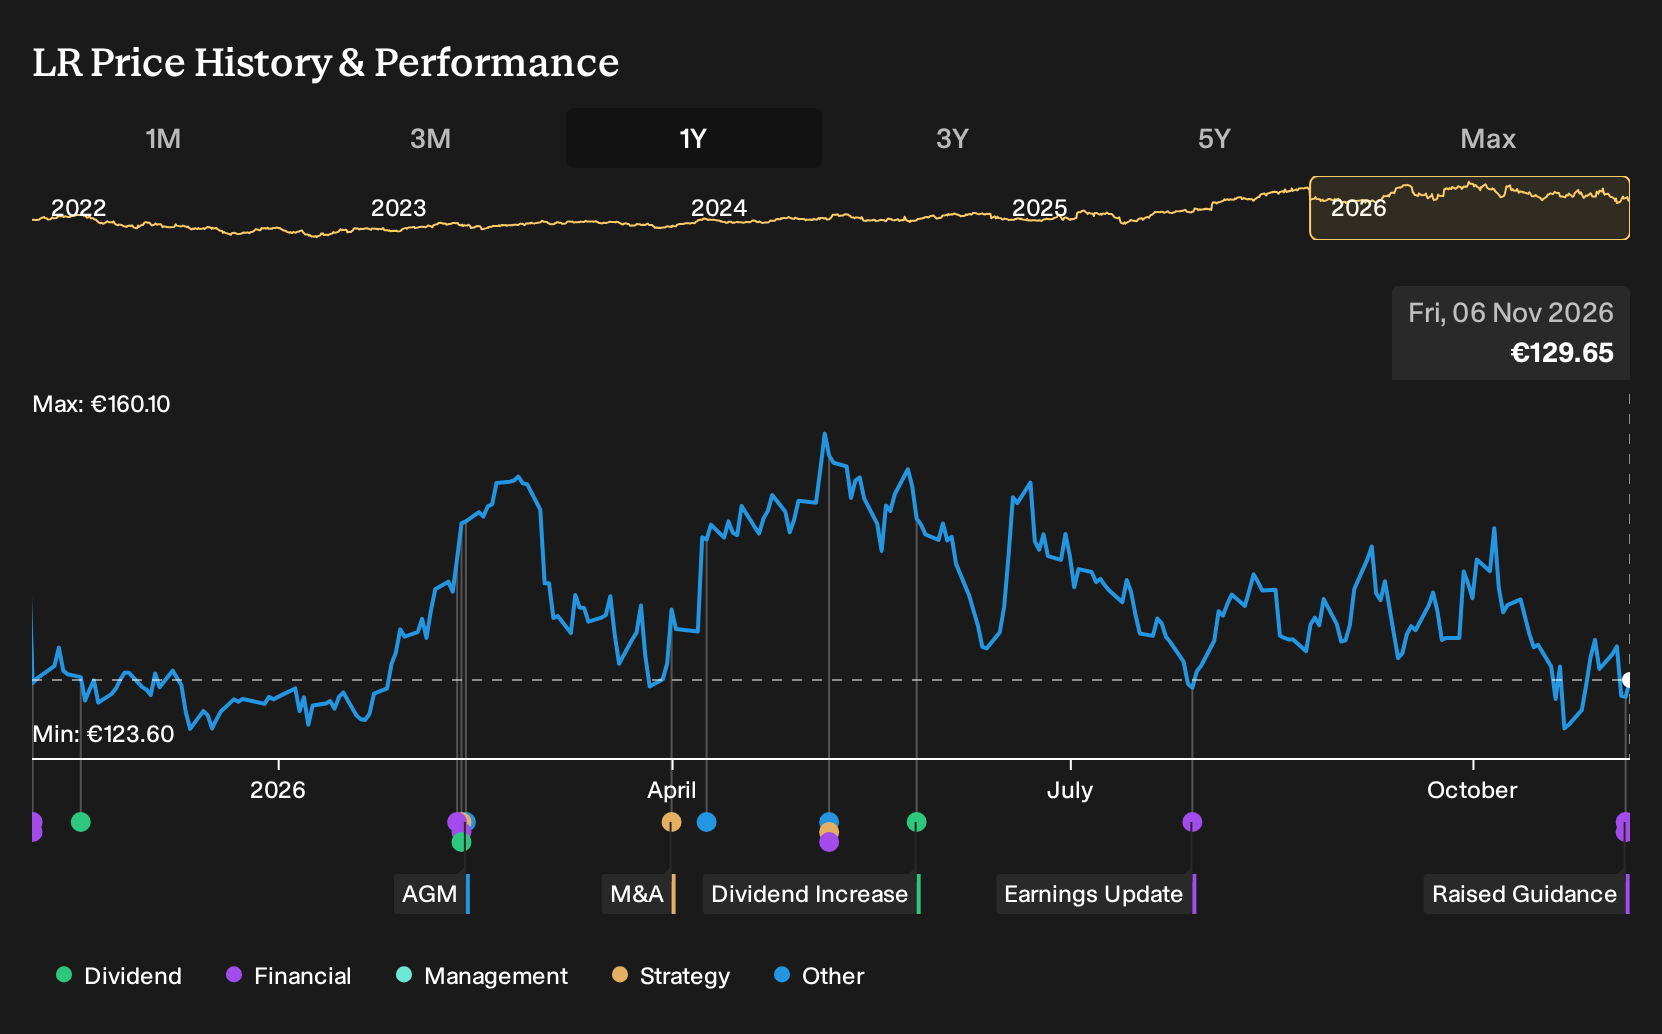
The most relevant new data point is Legrand lifting its 2026 sales growth target to 20% to 22% excluding currency effects. That update leans on strong nine month sales of €8,329.4m and net income of €1,067m, alongside an adjusted operating margin range of 20.5% to 21.0% of sales. For you, the question is how repeatable that mix looks.
If Legrand keeps integrating its seven recent deals in power distribution, data center infrastructure and connected health while staying within that margin band, it supports the idea that scope growth can complement organic demand. If cost inflation, weaker construction or slower AI data center rollouts bite harder, that same guidance range becomes the area to watch as an early warning signal.
What Legrand’s Consensus Targets Assume
Analyst models around Legrand are built on a clear set of revenue and profit assumptions that you can pressure test against your own view of AI data centers and grid investment. The core inputs matter more than the headline price targets because they spell out what the business would need to deliver over time.
On the top line, brokers are working off revenue growth of 11.7% a year over the next three years. That is paired with a projected lift in profit margins from 13.0% today to 14.3% by 2029, which would line up with the broader story of a richer mix in data center and power infrastructure exposure if it plays out.
On earnings, the consensus points to profit of €2.0b by 2029, compared with €1.3b today. That implies an increase of about €0.7b in annual earnings over the period, with the tight margin improvement doing some of the work and revenue expansion doing the rest.
Valuation work then links those operating targets back to what investors are being asked to believe about Legrand’s future trading multiple. The consensus framework assumes that by 2029 the group could be on about €14.1b of revenue and €2.0b of earnings, trading on a P/E of 29.0x versus roughly 27.5x today and below the cited 31.1x for the wider GB Electrical peer set.
This set of expectations also feeds into the average analyst price target of €168.67 against a current share price of €138.0, framed using a discount rate close to 9.7%. The range around that target, from €120.0 to €200.0, reflects different views on how fully Legrand can turn its data center, power grid and connected health exposure into the revenue growth, margin steps and earnings scale implied by those 2029 markers.
Legrand's current analyst narrative points to forecast revenue of €14.1b and expected earnings of €2.0b by 2029. That profile assumes yearly revenue growth of 11.7% and an earnings increase of about €0.7b from €1.3b today.
Uncover why Legrand's fair value indicates a 30% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You can also weigh a very different angle. The most pessimistic analysts worry that Legrand’s AI data center exposure amplifies downside if IT load growth cools. This is why they were only pencilling in about €13.5b of revenue and €1.8b of earnings by 2029 before this update. That gap shows how widely views can differ, so treat this new guidance as a prompt to compare several narratives, not just one.
Explore 4 other Legrand fair value estimates, including one that suggests as much as 17% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Legrand research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Legrand. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Legrand's overall financial health at a glance.
Looking For More Investment Ideas Beyond Legrand?
If Legrand has sharpened your interest in power, infrastructure and quality balance sheets, it can help to line it up against other opportunities using the Simply Wall St Screener.
- If resilience matters most to you, filter for companies with steadier risk profiles through the 212 resilient stocks with low risk scores.
- For those who want quality at a reasonable price, compare Legrand with a 225 high quality undervalued stocks that blend strong fundamentals with appealing valuations.
- If you prefer under the radar stories with solid financials, scan through a 588 high quality undiscovered gems that might not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com