


EN
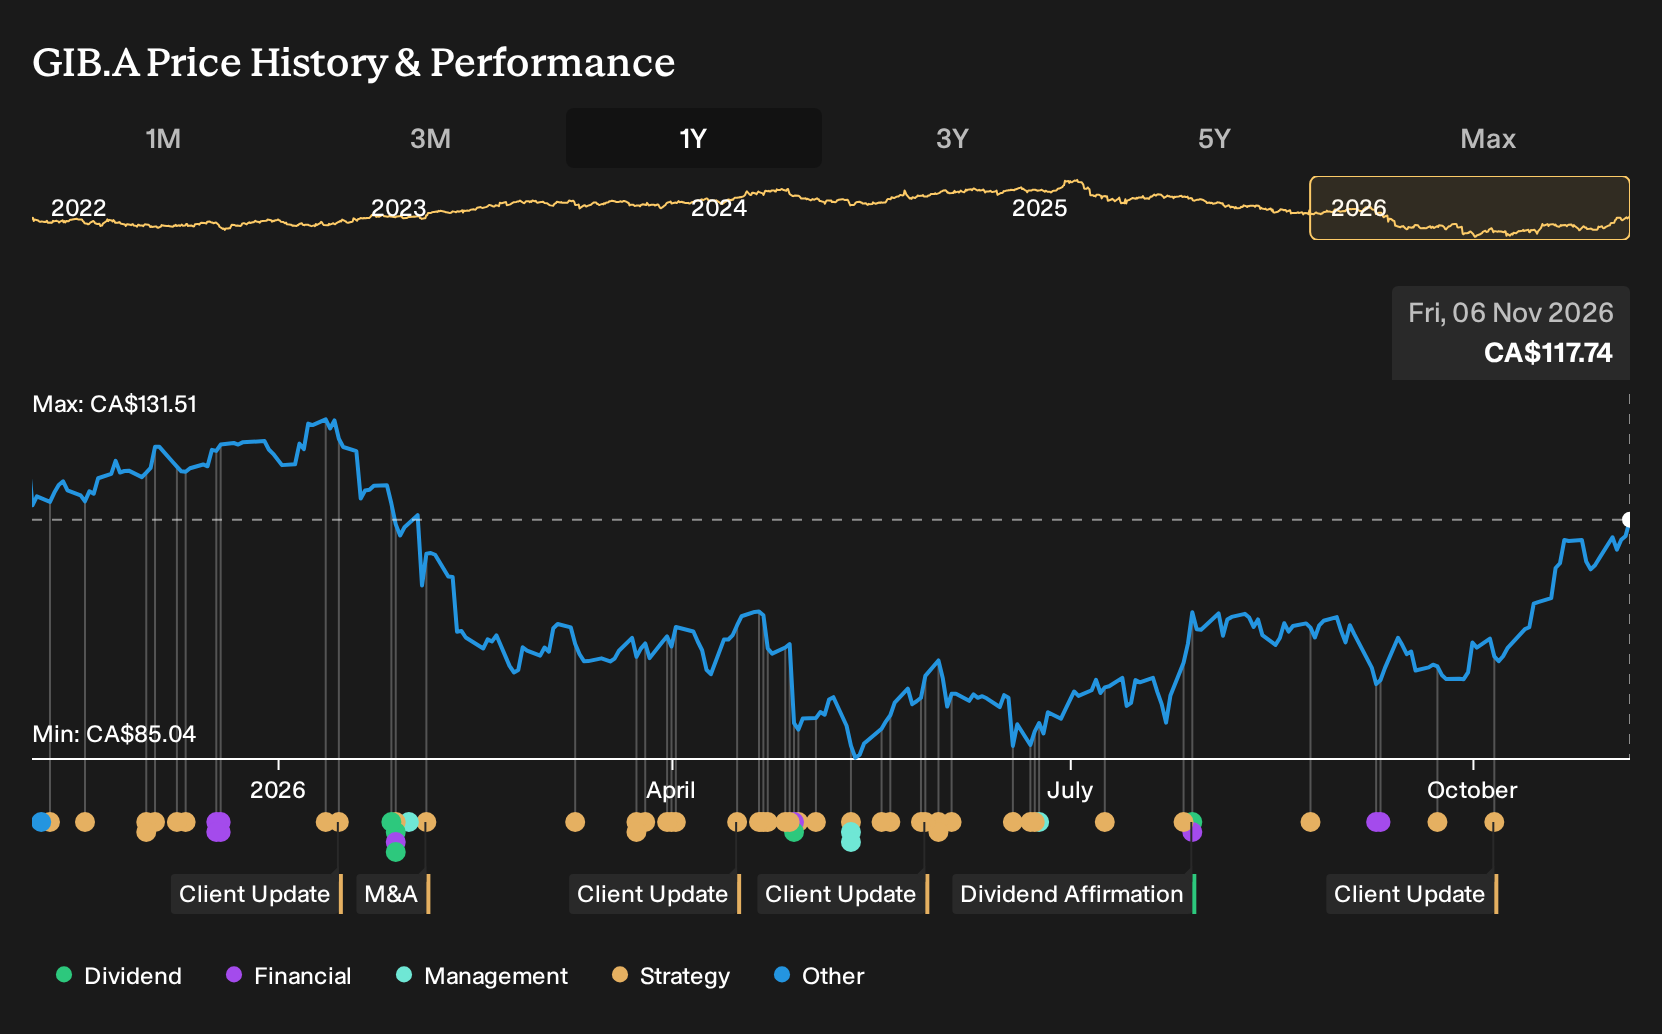
How Upcoming Earnings Will Impact CGI Stock Investors
- CGI plans to release its fourth quarter and fiscal 2026 results for the year ended September 30 on November 11, 2026, with management hosting a conference call the same morning to review performance and answer questions.
- Alongside heightened attention on its upcoming earnings, CGI Federal's Super Intelligence Workforce Development Coalition highlights how the business is tying AI-focused talent development to long term technology services demand from government and large enterprises.
- We now look at how CGI's upcoming fiscal 2026 earnings update could influence its investment narrative around technology services demand.
CGI Investment Narrative Recap
To own CGI, you need to believe the services model can keep translating digital transformation and AI demand into steady bookings, solid backlog conversion and disciplined delivery. The upcoming fiscal 2026 results look like the key near term catalyst because they will show how that thesis is holding up on margins, utilization and cash generation.
The biggest immediate risk is softer client decision making or public sector budget timing that drags on organic revenue and pressures net margins, especially where conditions are already tougher. The earnings release and call may shift sentiment around that risk, but the news flow so far does not materially change it.
The Super Intelligence Workforce Development Coalition that CGI Federal is leading is tightly linked to those catalysts. It reflects how deeply AI is being embedded into the consulting and managed services mix, which already includes a high share of AI enabled solutions. Every new managed services proposal now includes advanced AI by default.
For you as an investor, this coalition is most relevant as an execution signal. It ties talent pipelines, SI ready curricula and government relationships directly into longer term demand for AI heavy contracts. At the same time, it still sits against the same familiar risks around federal budgets, competitive rebids and the need to keep translating a large backlog into high quality earnings and cash flow.
CGI's analyst narrative projects CA$18.0b revenue and CA$2.2b earnings by 2029. This aligns with an assumed 3.1% yearly revenue growth rate and an earnings increase of about CA$0.5b, from CA$1.7b today to that 2029 consensus level.
Uncover how CGI's fair value indicates a 3% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on CGI leans hard into the risk that slower AI project rollouts keep revenue growth subdued. Those bearish analysts were only pencilling in about 1.7% yearly sales growth and roughly CA$17.2b of revenue by 2029 before this news. That is a much more cautious story. Use the upcoming earnings and SI coalition updates to compare several narratives, not just one.
Explore 4 other CGI fair value estimates, including one that suggests it could be worth just CA$120.69.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your CGI research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for CGI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CGI's overall financial health at a glance.
Looking For More Investment Ideas Beyond CGI?
Once you have a handle on CGI, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener is built for exactly that sort of side by side work.
- For investors hunting for possible mispriced opportunities with solid fundamentals, start with companies on our 6 high quality undervalued stocks and see how their metrics compare with what you see at CGI.
- If capital preservation and stability matter most to you, focus on businesses with stronger balance sheets and resilient fundamentals through our list of solid balance sheet and fundamentals (5 results) so you can stress test ideas against tougher conditions.
- Those aiming to build a more income focused portfolio can look at established payers on the 3 dividend fortresses and judge whether their yields and payout profiles suit your goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com