


EN
3 US Dividend Stocks for Steady Income When Rates Stay Higher
With the Fed leaning hawkish again and real wages struggling to keep up with inflation, steady cash payouts suddenly look a lot more interesting. Income-focused stocks that rely less on breakneck growth and more on durable dividend streams can feel like a shelter when rates and jobs data keep markets guessing. This article walks through three dividend payers exposed to these macro forces and explains where the risks and potential appeal may sit today.
The three stocks covered below are just a sample of this theme. The wider screen surfaces 25 more U.S. dividend payers in defensive areas where cash flow, balance sheet strength and income profiles may look just as compelling. If you want to go straight to the source and identify ideas that best match your risk and income targets, analyze the full US Defensive, Cash-Generating Dividend Stocks screener.
McCormick (MKC)
Overview: McCormick & Company sells herbs, spices, seasonings and condiments worldwide to households, restaurants and packaged food producers, supporting a defensive, dividend focused profile.
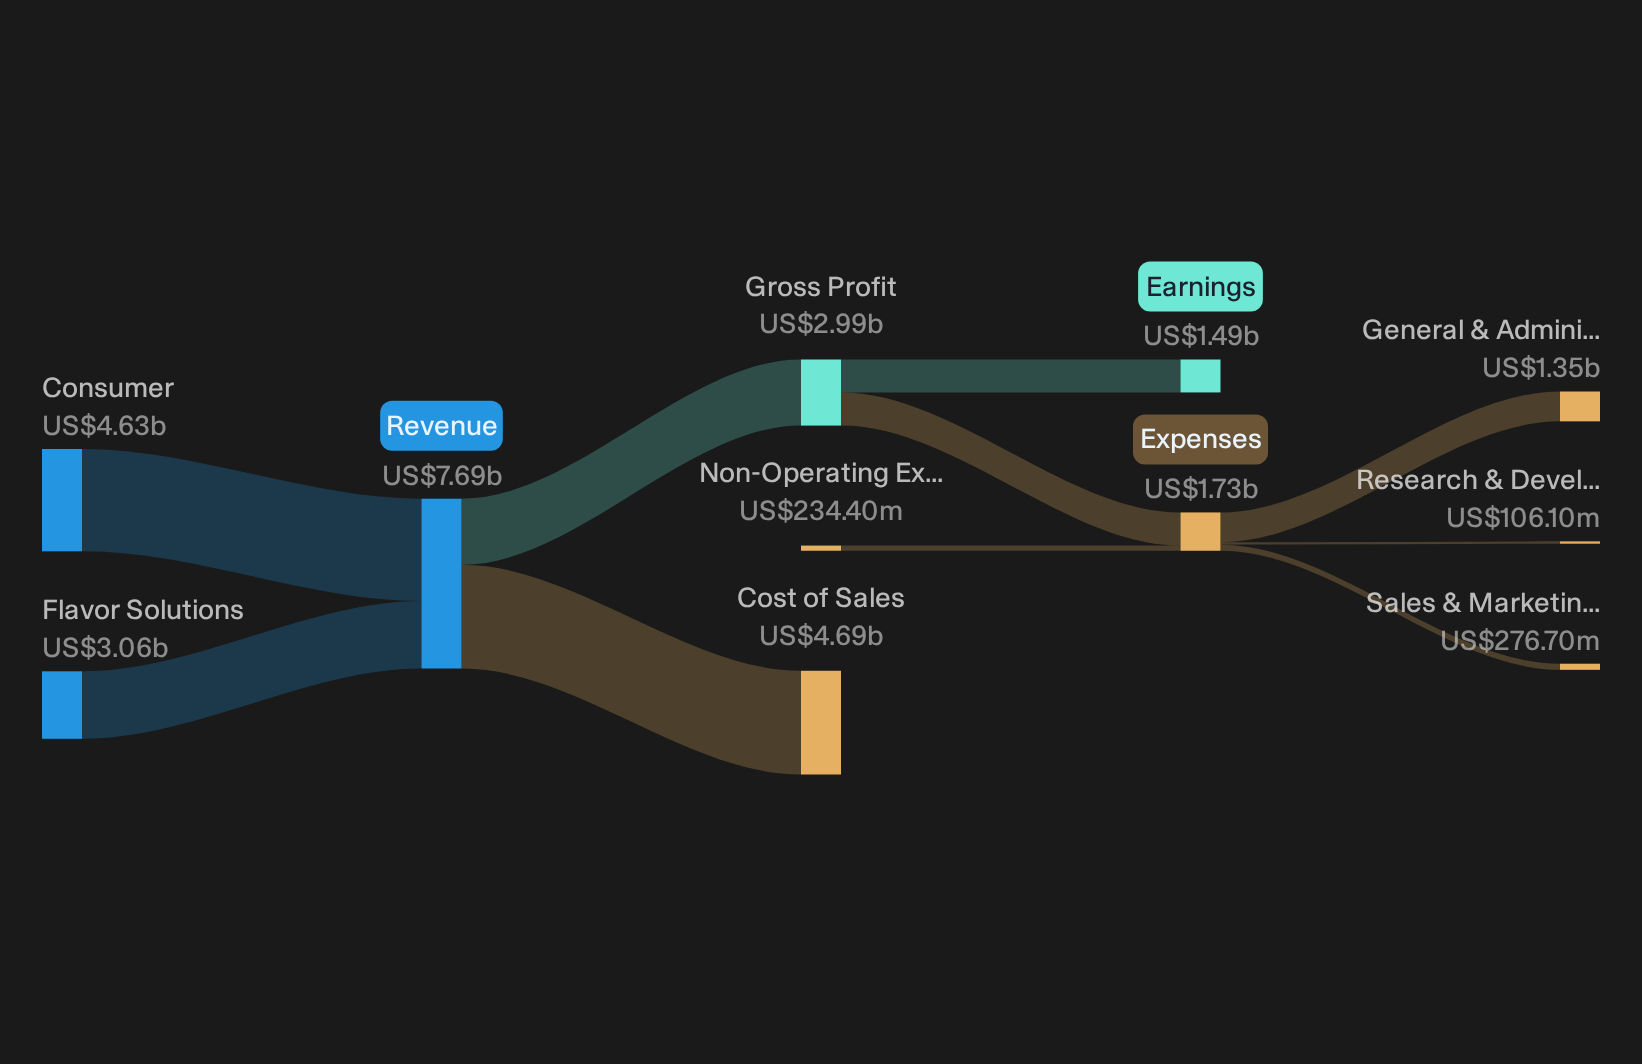
Operations: McCormick generates about US$4.6b from its Consumer segment and US$3.1b from Flavor Solutions, with additional EMEA revenue.
Market Cap: US$13.5b
McCormick fits this defensive, cash generating income screen because its everyday pantry brands help support dividend payouts when rates rise and growth stocks feel more volatile.
"Consumer EMEA has recorded 11 consecutive quarters of positive volume, with recent 5% organic growth supported by both volume and pricing, which points to a developing second consumer growth pillar for McCormick that can widen the revenue base and reduce earnings reliance on the U.S."
The real swing factor for income minded investors is how one future cost pressure shapes McCormick’s ability to protect cash rich margins.
That cost story is only half of it, and the rest sits inside the full narrative for McCormick with how McCormick could keep cash generation decoupling from raw material pressures.
Otter Tail (OTTR)
Overview: Otter Tail Corporation runs a regulated electric utility in the Upper Midwest alongside manufacturing and PVC pipe businesses serving a range of U.S. end markets.
Operations: Otter Tail generates about US$571.9 million from Electric, US$393.2 million from Plastics and US$344.9 million from Manufacturing operations.
Market Cap: US$3.4b
Otter Tail gives this dividend screen a classic utility flavor. Regulated power operations anchor cash flows, while manufacturing and plastics add extra income potential when higher rates unsettle growth heavy sectors.
"Continued execution of Otter Tail’s US$1.9b electric capital program, with a reaffirmed 10% rate base CAGR and nearly 1:1 conversion of that rate base growth into utility earnings, is expected to support future EPS."
The real test for Otter Tail’s dividend appeal is how one moving piece in its non utility portfolio ultimately shapes cash coverage.
That moving piece is exactly what the full narrative for Otter Tail unpacks, showing how Otter Tail’s earnings mix could quietly reshape dividend capacity and re rate potential.

Hershey (HSY)
Overview: Hershey makes chocolate, sweets, salty snacks and pantry items under well known brands, offering a classic consumer staples cash generator.
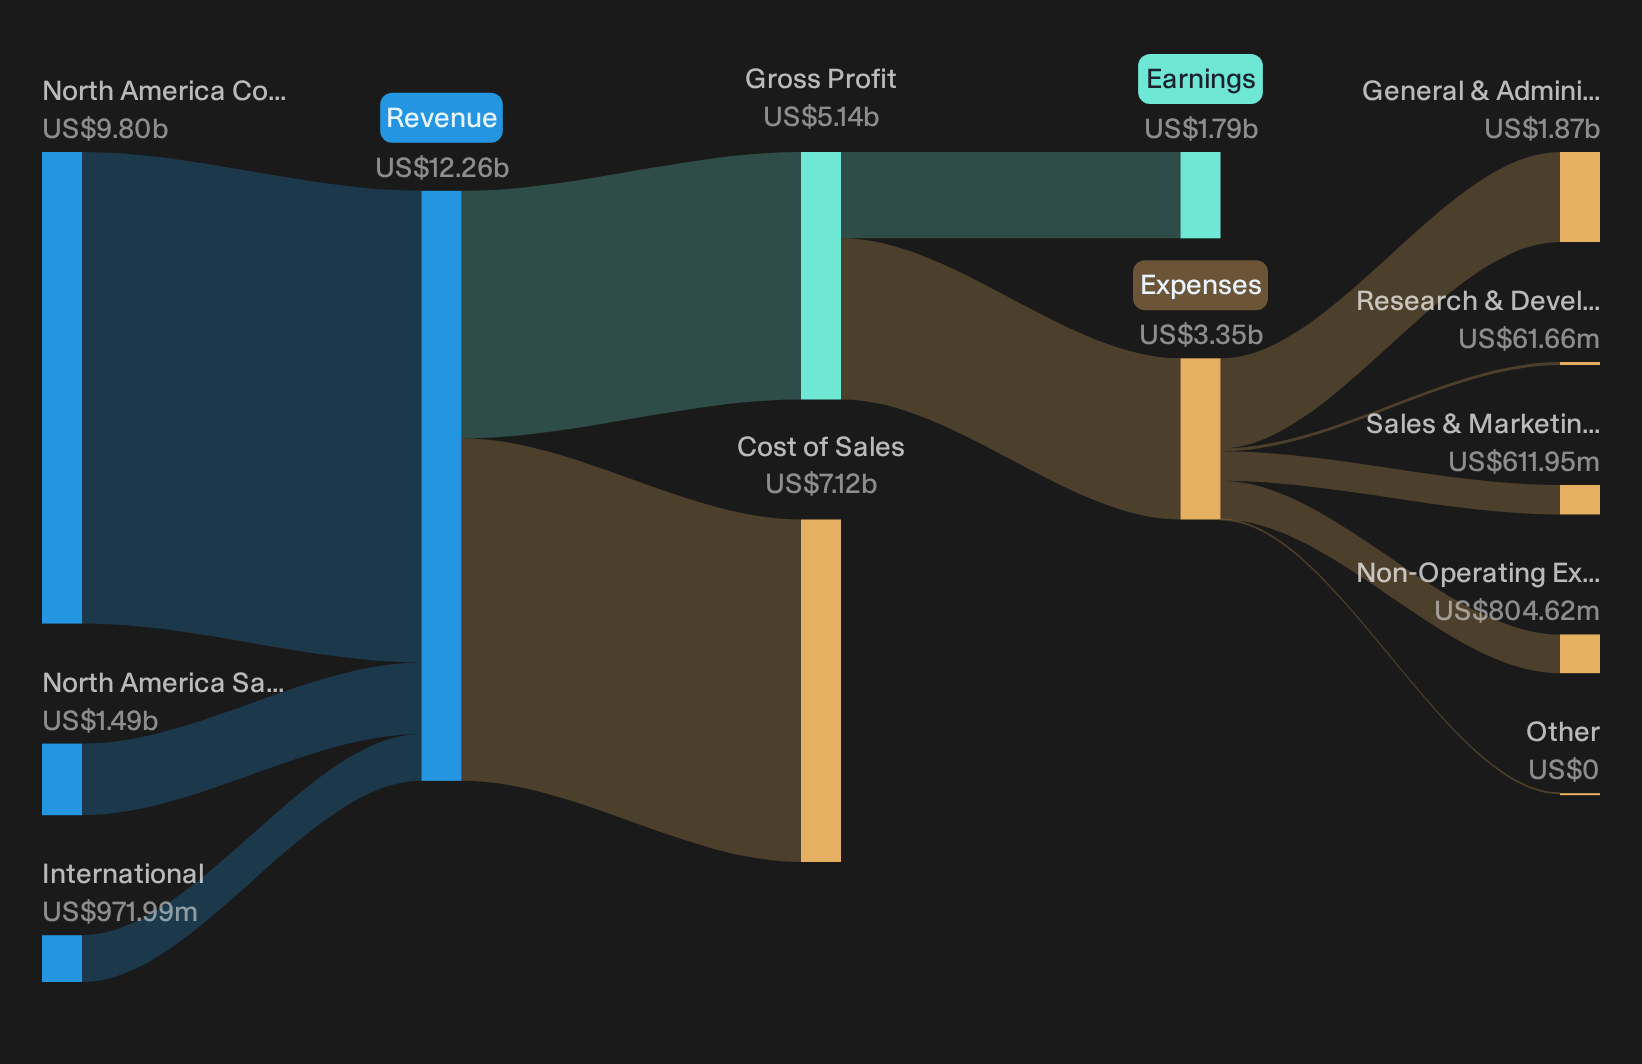
Operations: Hershey generates about US$9.8b from North America Confectionery, US$1.5b from North America Salty Snacks and US$1b from International markets.
Market Cap: US$35.7b
Hershey fits this defensive dividend screen because everyday treats and pantry staples can keep cash coming in even when rates rise and growth sectors swing around.
"The 2025 cocoa shock, which led to a ~60% GAAP EPS collapse driven largely by non-cash hedge mark-to-market, obscured an underlying cash engine that remained intact."
What really matters for long term income investors is how one quiet shift in Hershey’s cost and pricing balance ultimately lands on margins.
That quiet shift is exactly what the full narrative for Hershey unpacks, showing how Hershey’s pricing power, cocoa exposure and cash generation could be quietly decoupling from headline EPS noise.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout stories, dropping valuations and quiet momentum shifts often get caught early, then move once attention hits. Review these under the radar lists and consider your options.
- Identify cash generative companies with potential by scanning the curated 39 high quality undervalued stocks while the gap between quality and pricing is still visible.
- See where current earnings align with AI-related activity by reviewing the hand picked 41 profitable AI stocks that aren't just burning cash before sentiment shifts to the next theme.
- Explore possible infrastructure beneficiaries by scanning the focused 42 power grid technology and infrastructure stocks while these grid upgrades receive limited attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com