


EN
VinFast Auto (VFS) Delivery Surge Puts Its Valuation Story Back In Focus
VinFast Auto stock reacts to Q3 delivery surge and asset light shift
VinFast Auto (VFS) is back in focus after reporting third quarter 2026 operating results, highlighted by 82,580 global EV deliveries and a 116% year over year jump, alongside a move toward an asset light manufacturing model.
VinFast Auto’s share price has edged up over the past month, with a 1-day share price return of 0.93% and a 30-day share price return of 7.26%, while longer term performance remains weak, as shown by a 1-year total shareholder return that declined 5.25% and a 5-year total shareholder return that fell 66.63%.
This pattern hints that the delivery surge and shift toward an asset light approach are lifting short term sentiment, even as investors still price in longer running concerns about liquidity, cash burn and reliance on Vingroup support.
Scan how VinFast Auto compares to other electric vehicle players by reviewing a curated list of 29 resilient stocks with low risk scores that may better balance operational momentum with financial resilience.
VinFast Auto now trades in the shadow of a sharp delivery jump and a still weak multi year return record. Do you lean into the recent momentum, or wait for a clearer margin of safety before committing fresh capital?
Most Popular Narrative: 42% Undervalued
Analysts following VinFast Auto see a fair value of $5.57 per share versus the recent close around $3.25. This frames the stock as meaningfully discounted while hinging on a demanding execution story.
The transition to an asset light model in Vietnam through the spin off of domestic manufacturing assets and a long term cost plus production contract, together with reduced factory CapEx and reallocation of around US$500 million toward international opportunities, is aimed at improving gross margin and earnings quality as the cost base becomes more flexible.
See why 10 investors see VinFast Auto as 42% undervalued.
Result: Fair Value of $5.57 (UNDERVALUED)
Still, the VinFast Auto story leans heavily on continued Vingroup funding and a shift from very weak gross profitability. As a result, any stumble there could quickly challenge this undervalued thesis.
Find out about the key risks to this VinFast Auto narrative.
Another View: VinFast Auto looks expensive on sales
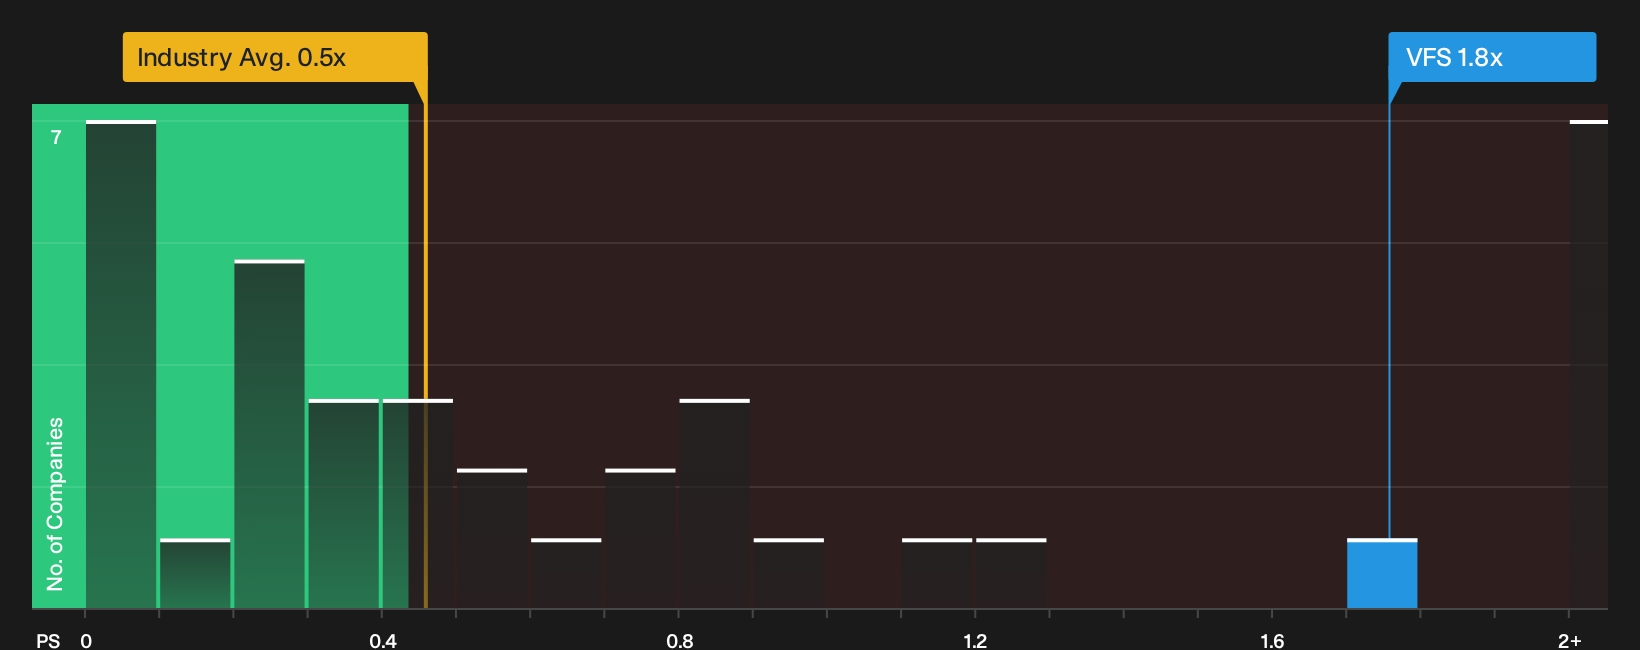
High fair value estimates paint VinFast Auto as 42% undervalued, yet its current P/S ratio of 1.8x sits well above both the US Auto industry at 0.5x and the peer average at 1.3x. That premium raises a simple question for you: Is the risk of overpaying worth the story?
To stress test that premium against hard numbers and see how it lines up with the fair ratio of 0x, take a closer look at our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on VinFast Auto after all that. If you want to move quickly and still keep your own judgment front and center, start by weighing the 1 key reward and 3 important warning signs.
Looking for more VinFast Auto sized investment ideas?
If VinFast Auto has your attention, broaden your opportunity set now and let high quality screeners surface candidates you might otherwise overlook.
- Target potential bargains first by scanning companies flagged as 39 high quality undervalued stocks that combine solid fundamentals with prices that have not fully reflected their profiles yet.
- Strengthen your downside protection by focusing on businesses in the list of solid balance sheet and fundamentals (24 results) which can sometimes better withstand funding pressure and economic shocks.
- Get ahead of the crowd by reviewing the 19 high quality undiscovered gems where strong financial traits have not yet attracted wide investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com