


EN
Record Earnings Might Change The Case For Investing In Nexstar Media Group Stock (NXST)
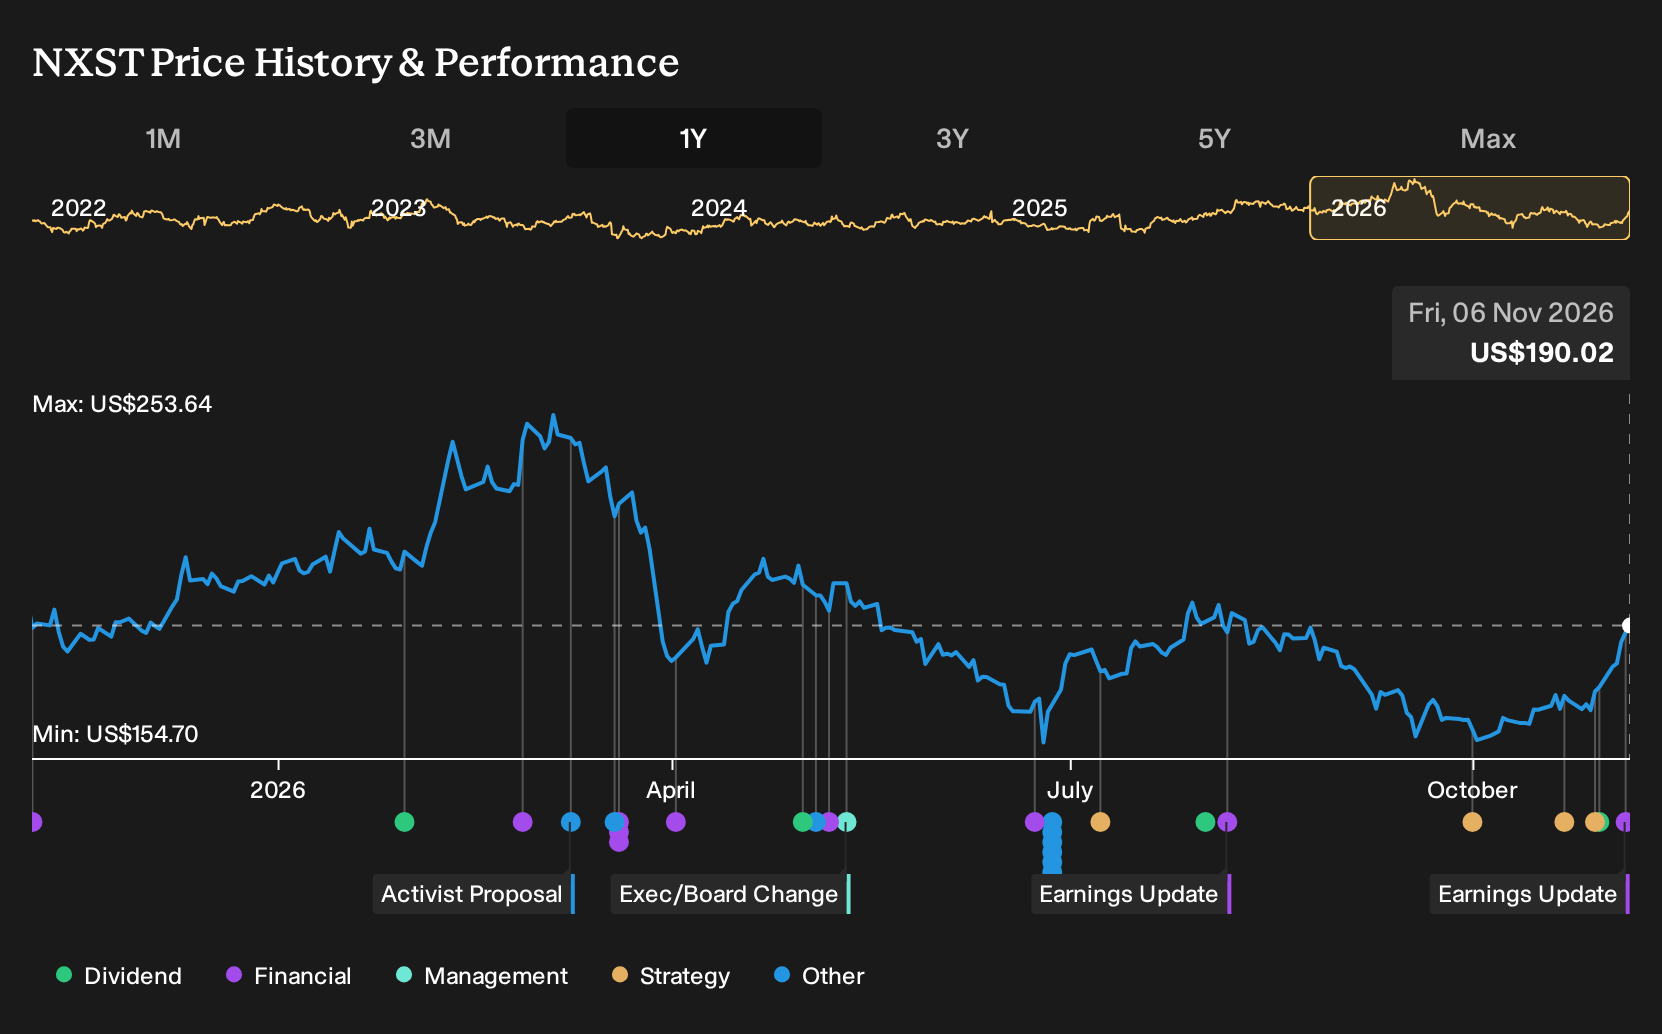
- Nexstar Media Group reported third quarter 2026 sales of US$2.133 billion and net income of US$255 million, with basic EPS from continuing operations of US$7.97.
- Stronger cash generation supported debt repayment, a US$1.86 quarterly dividend declaration, and fresh content investment, including wider UIL Texas high school football championship coverage across broadcast and streaming platforms.
- This article examines how Nexstar Media Group's record quarterly earnings may reshape the investment narrative built around scale, leverage and cash generation.
Scan how Nexstar Media Group's record quarter compares with other broadcasters and content plays that screen strongly on cash generation and balance sheet strength with the curated 39 high quality undervalued stocks list.
Nexstar Media Group Investment Narrative Recap
To own Nexstar Media Group, you need to believe its scale in local news, political advertising and digital can offset pressure from shrinking pay TV households and softer nonpolitical ad budgets. The third quarter beat, with US$2.133b in sales and US$7.97 in basic EPS from continuing operations, strengthens that case by showing the TEGNA integration feeding into higher earnings and cash generation.
The near term swing factor remains how effectively Nexstar converts this larger footprint into durable distribution fees and digital revenue, while managing leverage and interest costs that are not fully covered by earnings. Key risks stay intact, particularly reliance on cyclical political spend and structural pressure on traditional TV audiences, so this quarter helps the story but does not remove the core threats.
The fresh quarterly dividend declaration of US$1.86 per share ties directly into the current catalyst mix. Stronger cash flow from the record third quarter, and from the nine month period with US$5.522b in sales and US$539m in net income, gives Nexstar Media Group more room to keep rewarding shareholders while working down debt.
For you as an investor, that payout sits alongside Nexstar Media Group’s use of cash for debt repayment and content, such as the expanded UIL Texas high school football coverage. The dividend helps anchor the equity story around income and discipline, while execution risk still lives in integrating TEGNA, growing digital beyond linear headwinds and smoothing earnings between political cycles.
Nexstar Media Group's current analyst storyline points to revenue of US$8.1b and earnings of US$960.2m by 2029, based on an assumed 11.3% annual revenue growth rate and a move from US$166.0m of earnings today to that higher forecast. This implies an earnings increase of about US$794m over the period.
Uncover why Nexstar Media Group's fair value indicates a 30% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
One alternate view focuses on Nexstar Media Group’s growing sports commitments on The CW as the key risk. The most cautious analysts were only penciling in about US$5.2b of revenue and US$704.0m of earnings by 2029 before this record quarter. That is a far more pessimistic path than consensus. Use that gap as a prompt to explore several different narratives around the stock.
Explore 2 other Nexstar Media Group fair value estimates, including one that suggests it could be worth just $246.75!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Nexstar Media Group research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Nexstar Media Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nexstar Media Group's overall financial health at a glance.
Looking For More Nexstar Media Group Style Ideas?
If the Nexstar Media Group story has sharpened your thinking around cash generation, balance sheet strength and income, it can help to widen the lens and see which other businesses line up with the traits you care about most.
- For investors who want potential upside with quality filters already applied, review the 19 high quality undiscovered gems that rarely appear on headline lists but still clear solid fundamental hurdles.
- If capital preservation and steadier profiles matter most, scan the 29 resilient stocks with low risk scores to focus on companies that score well on resilience and lower overall risk.
- For readers who care about financial resilience before anything else, start with the list of solid balance sheet and fundamentals (24 results) and narrow the field to businesses with stronger funding and fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com