


EN
Earnings Miss Could Be A Game Changer For Payoneer Global (PAYO)
- Payoneer Global reported Q3 2026 sales of US$276.94 million and net income of US$14.92 million, with GAAP earnings per share at US$0.04, which fell short of market revenue and EPS expectations.
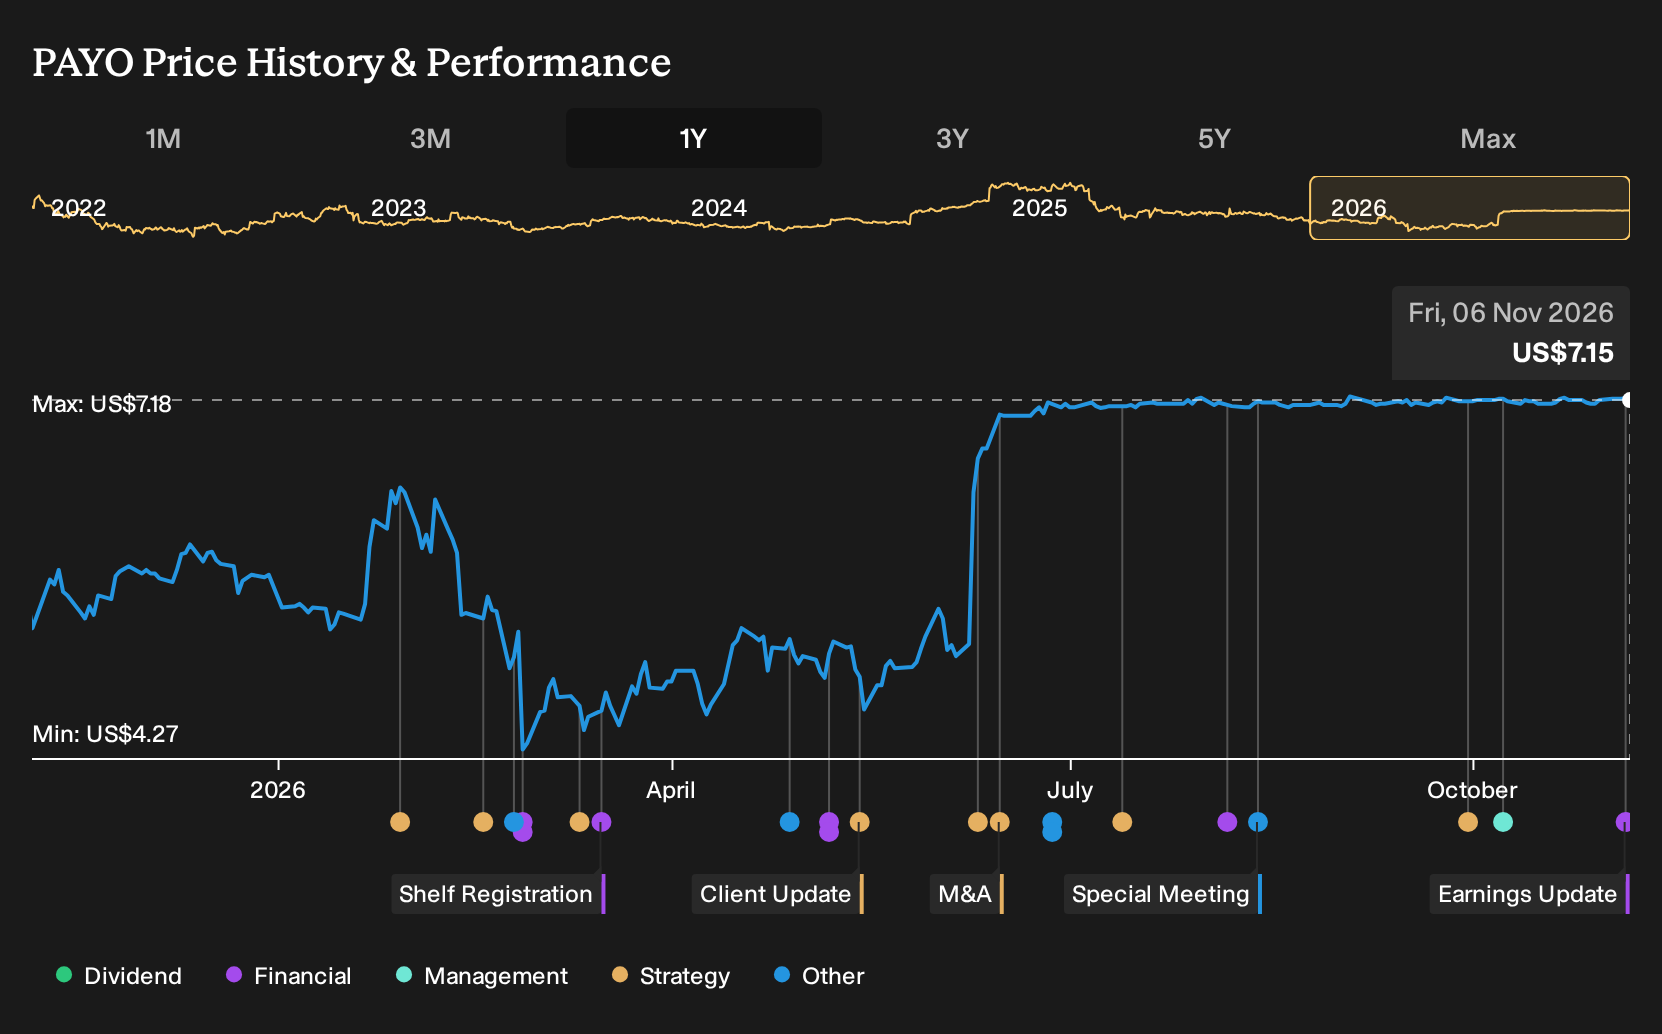
- Behind the earnings miss, Payoneer Global continued to grow its B2B payment volumes and secured new licenses in Canada and Israel, while advancing its planned merger with Nuvei.
- We now look at how Payoneer Global's earnings miss relative to expectations could reshape the existing investment narrative around the business.
Contrast Payoneer Global's earnings miss and merger plans with a curated set of payment and fintech peers by scanning the 19 high quality undiscovered gems, which are still flying under most investors' radar.
Payoneer Global Investment Narrative Recap
To own Payoneer Global, an investor needs to believe the cross border payments engine, especially higher margin B2B flows and value added services, can keep scaling despite competitive pressure. The Q3 2026 miss on revenue and EPS points more to timing than to a broken model, given that volumes and net income still moved in the right direction.
The most important near term catalyst remains execution on those richer B2B and enterprise use cases, along with new products such as the stablecoin wallet and a potential U.S. trust bank. The biggest risk is that these newer lines underperform or competitors compress fees faster, which would matter far more than one soft quarter.
The Q3 update matters most because it sits alongside Payoneer Global’s merger plan with Nuvei, which already has shareholder approval and is tracking toward a targeted mid 2027 close. This deal could reshape cost structure, product breadth and customer reach, all of which connect directly to the B2B and value added services thesis.
Progress on merger approvals, combined with fresh licenses in Canada and Israel, supports the idea that the operational story is about building a broader, fully regulated payments network. For you as a shareholder or potential buyer, the key questions now focus on execution in integration, regulatory timing and whether Payoneer Global can keep translating rising volumes into healthier margins.
Payoneer Global's current narrative assumes revenue reaches US$1.4b and earnings hit US$181.2 million by 2029, based on analysts modelling 10.0% yearly revenue growth and an earnings increase of about US$130.9 million from US$50.3 million today.
Uncover why Payoneer Global's fair value indicates a 3% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
One alternate view around Payoneer Global focuses on the Nuvei merger as the real catalyst. The most optimistic analysts were pencilling in US$1.5b of revenue and US$226.1 million of earnings by 2029 before this Q3 miss. You can treat those richer assumptions as a stretch case and compare how different forecasts might shift after this report.
Explore 4 other Payoneer Global fair value estimates, including one that suggests it could be worth as much as $7.40.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Payoneer Global research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Payoneer Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Payoneer Global's overall financial health at a glance.
Looking for more Payoneer Global investment ideas?
If the Payoneer Global story has you thinking about how to round out your watchlist, the Simply Wall St Screener can help you scan for other opportunities that match your approach rather than just your curiosity.
- For investors who want quality at a sensible entry point, start by checking a curated set of 39 high quality undervalued stocks that combine solid fundamentals with more attractive price tags.
- If capital preservation ranks high on your checklist, focus on resilience first and return second by reviewing a hand picked group of 29 resilient stocks with low risk scores that clear stricter risk filters.
- For those who care most about financial strength before anything else, concentrate on balance sheet robustness with this list of solid balance sheet and fundamentals (24 results) that filters for sturdier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com