


EN
What Ulta Beauty (ULTA)'s WHOOP Partnership Means For Shareholders
- WHOOP announced a retail partnership to bring its wearable health devices and insights to Ulta.com and select Ulta Beauty stores from March 2027. The collaboration aims to tap into Ulta Beauty's 47 million member loyalty base with hardware, accessories and in store experiences.
- Ulta Beauty is layering this WHOOP health offering on top of recent additions like DECORTÉ, KSecret, MARSHIQUE and RCMA Makeup. This broadens its assortment across wellness, prestige skin care and professional makeup while using its marketplace and store network to test demand at scale.
- We will look at how Ulta Beauty's investment narrative evolves as wellness deepens through the WHOOP rollout across stores and online.
Scan how Ulta Beauty's wellness push compares with other retailers building similar exposure by reviewing a curated group of list of solid balance sheet and fundamentals (24 results) in the sector.
Ulta Beauty Investment Narrative Recap
To own Ulta Beauty, you need to believe the retailer can keep turning its 47 million member ecosystem, expanding wellness assortment and marketplace into steady, profitable traffic across both stores and digital. The immediate swing factor is execution in core U.S. brick and mortar, since store productivity still underpins earnings even as e commerce grows.
The biggest near term risk is that Ulta Beauty layers too many projects on at once, from wellness and WHOOP to international and AI, which could lift SG&A and supply chain costs faster than revenue. The WHOOP announcement looks directionally helpful for wellness, but is not yet a material shift to the overall risk reward profile.
The WHOOP partnership is the announcement that most directly links to the current wellness catalyst. It adds wearable health hardware and memberships into Ulta Beauty's aisles and Ulta.com, sitting alongside supplements, rest and renew products and broader wellness events. For you, the question is whether this actually deepens baskets or just adds complexity.
Operationally, WHOOP pushes Ulta Beauty a step further into higher ticket, tech enabled wellness where returns will hinge on attachment to existing categories, loyalty engagement and UB Media. Execution risk rises as the retailer manages training, in store experiences and inventory for a new product type, while still contending with heavier competition and ongoing promotional pressure in beauty.
Ulta Beauty's current analyst narrative forecasts US$15.1b in revenue and US$1.4b in earnings by 2029. This is based on analysts modeling 5.2% yearly revenue growth and an earnings increase of about US$200m from current earnings of roughly US$1.2b.
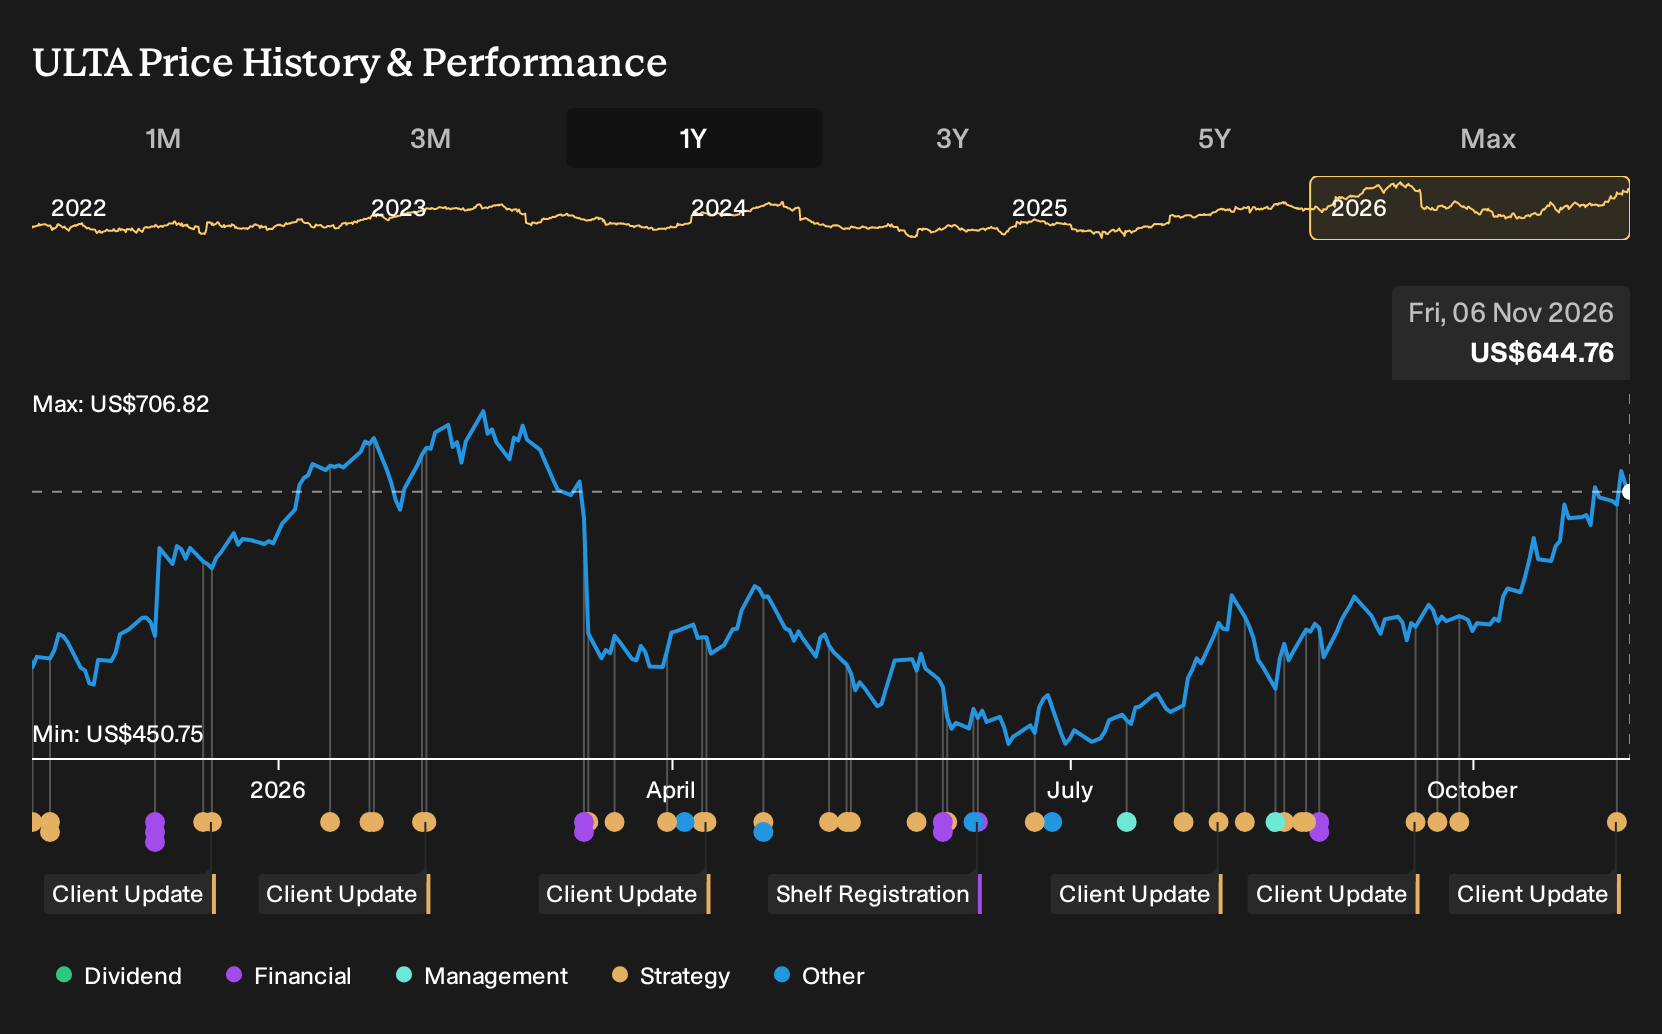
Uncover why Ulta Beauty's fair value indicates a valuation gap that is roughly in line with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts already framed Ulta Beauty as undervalued, assuming revenue could reach about US$15.4b and earnings about US$1.5b by 2029. You now have this WHOOP wellness partnership sitting on top of that more aggressive earnings story. Those higher conviction voices may sharpen or rethink that view as the wellness thesis evolves.
Explore 6 other Ulta Beauty fair value estimates, including one that suggests it could be worth as much as $636.96.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ulta Beauty research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ulta Beauty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ulta Beauty's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ulta Beauty?
Once you have a view on Ulta Beauty, the next step is to line it up against other potential opportunities. A simple way to do that is to scan a broader set of companies that match the kinds of qualities you care about, whether that is balance sheet strength, income potential, or mispriced quality.
- If you want stocks that aim for lower volatility and sturdier finances, start with a focused list of 29 resilient stocks with low risk scores that screen for resilience before growth.
- If value is your priority, compare Ulta Beauty with a curated pool of 39 high quality undervalued stocks that combine quality fundamentals with a price that may not fully reflect them.
- If you prefer to look where fewer people are paying attention, scan a hand picked set of 19 high quality undiscovered gems that highlight lesser followed companies with solid underpinnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com