


EN
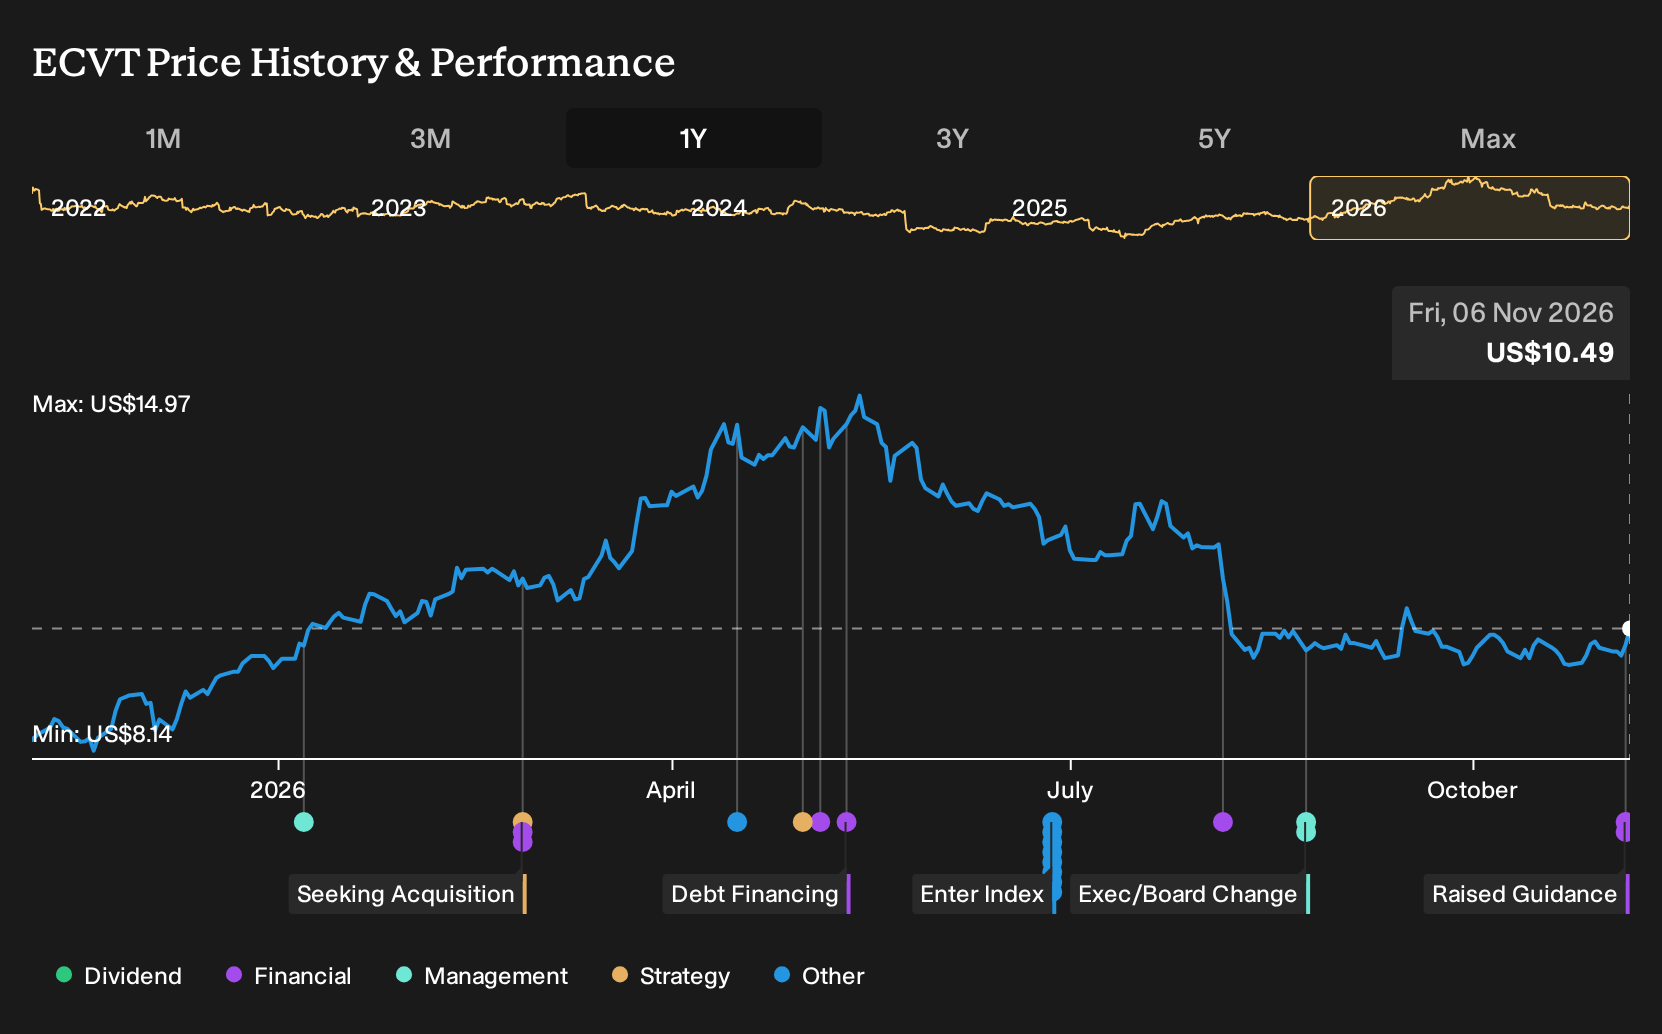
How Raised Guidance At Ecovyst Stock Has Changed Its Investment Story
- Ecovyst reported Q3 2026 sales of US$308.6 million, net income of US$18.2 million, and positive basic earnings per share after a prior year loss.
- The business lifted full year 2026 sales guidance to a range of US$1,050 million to US$1,070 million, which highlights management’s confidence in its sulfur solutions platform and recent operational execution.
- The focus now shifts to how Ecovyst's raised full year sales guidance may reshape the existing investment narrative around sulfur solutions.
Ecovyst Investment Narrative Recap
To stay invested in Ecovyst, you need to believe the sulfur solutions buildout can continue to translate into steadier earnings and cash generation as the network of sites and logistics matures. The latest Q3 report, with positive net income and earnings per share after a prior year loss, supports that execution story in the near term.
The key short term catalyst is delivery against the raised 2026 sales and adjusted EBITDA guidance while absorbing higher sulfur prices that are described as largely neutral to profit. The biggest operational risk is that heavy 2026 capital spending and working capital needs could erode free cash flow, especially if projects slip or sulfur price volatility persists.
The most relevant update is Ecovyst lifting 2026 sales guidance to US$1,050 million to US$1,070 million and raising adjusted EBITDA expectations to US$208 million to US$212 million. This sits alongside nine month sales of US$773.6 million and net income of US$30.3 million compared with a loss a year earlier.
For you as an investor, the raised outlook is closely linked to the sulfur solutions expansion thesis, including Waggaman and Calabrian integration and Gulf Coast logistics projects. Execution on those assets, together with planned capital expenditure and share repurchases of up to US$20 million in the second half of 2026, will likely influence how the story around leverage, cash flow and earnings quality develops from here.
Ecovyst's narrative projects US$1.2b revenue and US$144.5 million earnings by 2029. This assumes 11.5% yearly revenue growth and an earnings increase of about US$118.7 million from US$25.8 million today.
Uncover why Ecovyst's fair value indicates a 45% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view around Ecovyst focuses on demand risk. The most cautious analysts were concerned that higher sulfur prices could choke off volumes and leave Ecovyst underusing its expanded network. They were working off slower 9.4% annual revenue growth and about US$1.1b of sales by 2029. Those pre earnings assumptions may evolve, so treat this as one of several viewpoints to explore.
Explore another Ecovyst fair value estimate, including one that suggests it could be worth just $15.17!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ecovyst research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ecovyst. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ecovyst's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ecovyst?
If the Ecovyst story has sharpened your thinking about earnings quality, balance sheets, and cash generation, it can be useful to line it up against a broader watchlist built with the Simply Wall St Screener.
- For investors who want staying power over spectacle, scan a curated set of resilient companies in the 29 resilient stocks with low risk scores that keep overall risk scores in focus.
- If value is your priority, weigh Ecovyst's profile against a broader field by reviewing the 39 high quality undervalued stocks that combine solid fundamentals with attractive pricing.
- Income focused investors can round out their research by comparing Ecovyst with a hand picked group of 8 dividend fortresses built around higher yields and stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com