


EN
Does Confirmed Guidance Change The Bull Case For Melexis Stock (ENXTBR:MELE)?
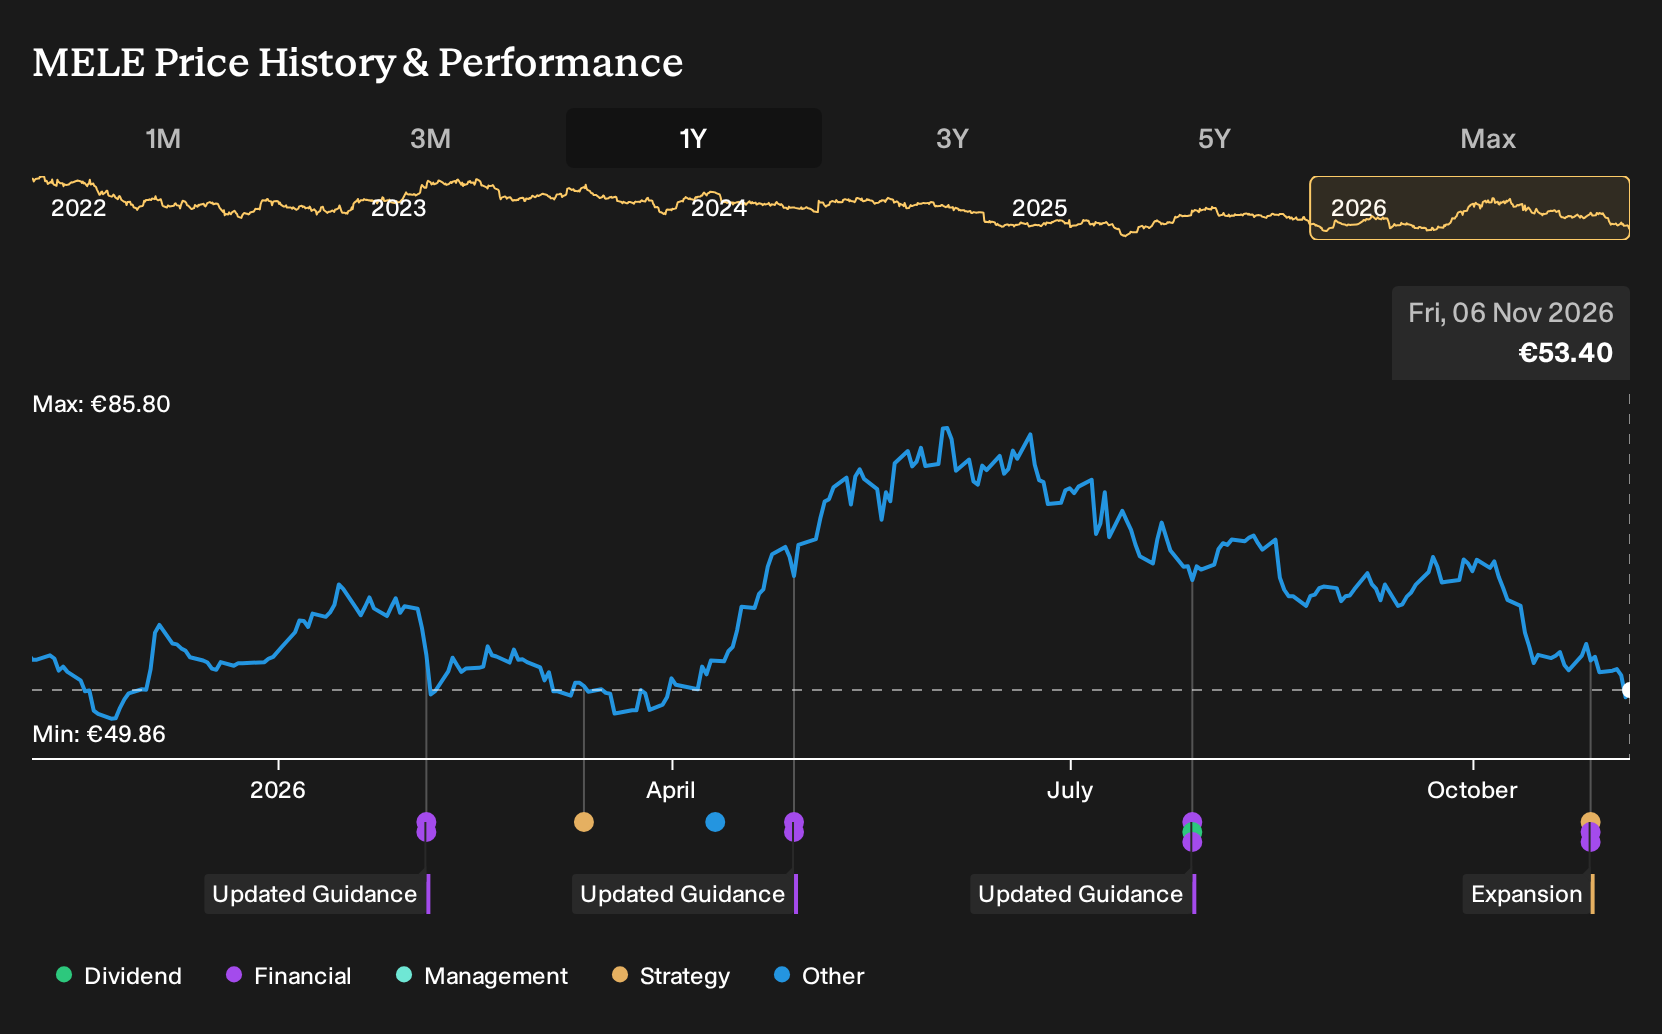
- Melexis reported third quarter 2026 sales of €223.71 million and net income of €31.32 million, confirmed second half 2026 guidance for €445 million to €455 million in sales with an operating margin around 18%, and recently opened a new engineering and sales office in Pune, India.
- The Pune expansion targets demand in 2 wheelers, vehicle electrification, solar and smart metering. This links Melexis’ earnings outlook to end markets where semiconductor content per device can be structurally higher.
- We will now look at how Melexis’ confirmed guidance and India expansion could influence the existing investment narrative around electrification.
Scan Melexis alongside peers riding similar themes in electrification, smart energy and mobility by checking our hand picked list of 225 high quality undervalued stocks.
Melexis Investment Narrative Recap
To own Melexis, you need to believe that demand for automotive and industrial semiconductors tied to electrification, sensing and smart energy remains a durable theme. The confirmed second half 2026 outlook for €445 million to €455 million in sales with an operating margin around 18% signals that management still sees enough order visibility to run the business within that range.
The short term swing factor is how quickly end market orders normalise while the sector works through elevated inventories. The key risk is that slower sell through or sharper price pressure, especially in China, pushes Melexis to trim volumes or pricing, which would weigh on margins and delay any improvement in earnings quality.
The Pune office opening is the announcement that most directly ties to the electrification story around Melexis. Management is building local engineering and commercial capacity in India around 2 wheelers, EV related content, solar and smart metering. These are all areas where semiconductor value per unit can be meaningful and closely linked to long term electrification demand.
For you as an investor, this expansion sets up a tangible execution test. Orders flowing from Indian two wheeler and energy customers could help offset slower platform ramps elsewhere and diversify away from more competitive regions. If uptake in these applications disappoints or local rivals push pricing harder than expected, the intended contribution to mix and profitability may simply not show up.
How Melexis’ Long Term Assumptions Tie Back To Electrification
Analyst expectations around Melexis give a sense of how much earnings power the electrification story is assumed to support over time. The projections combine top line expansion, higher profitability and a slightly leaner share count, all discounted back using an 11.9% rate from the Simply Wall St report.
On the revenue side, the consensus view is for 9.2% yearly growth over the next three years. That kind of pace implies consistent demand across vehicle electrification, sensing and smart energy, with the Pune build out sitting alongside existing platforms rather than replacing them. If end market orders in areas like 2 wheelers or solar underperform, it would be harder for Melexis to track that path without relying more on price or mix.
Earnings today are quoted at €104.0 million, with analysts expecting profit to reach €212.0 million by 2029. That is roughly a 2x increase in earnings from the current level, and it hinges on margins expanding from 12.2% to 19.2% over the same three year window. For investors, the link back to electrification is straightforward: higher value content per vehicle or per smart energy device needs to show up clearly in profitability for this margin lift to hold.
In valuation terms, the consensus framework assumes that by 2029, Melexis would be generating about €1.1b in revenue and €212.0 million in earnings. The market would then be paying a P/E of 18.9x on those earnings, down from 22.3x today and below the cited 22.2x multiple for the wider GB Semiconductor industry. If the shift toward India and other growth vectors delivers less scale or pricing power than expected, the gap between this implied multiple and actual trading levels could widen.
These assumptions also include a small 0.2% annual decline in shares outstanding over the next three years. That effect is modest compared with the role of revenue and margin in the analyst framework, but it still feeds through to earnings per share. For an investor tracking Melexis, it means the bigger swing factors sit in execution on electrification projects and product mix rather than in financial engineering.
Melexis is also being framed against a price target of €71.23 per share, with the most optimistic analysts at €92.0 and the most cautious at €55.0, versus a current share price of €57.5. That spread reflects differing views on how quickly automotive and industrial customers absorb new electrified platforms and sensing content. It also highlights that the same Pune expansion and broader electrification exposure that support the more optimistic case are seen as more uncertain by others, especially given supply chain inventories and pricing pressure in regions such as China.
Melexis' narrative projects €1.1b revenue and €212.0 million earnings by 2029. This framework incorporates 9.2% yearly revenue growth and roughly a 2x earnings increase from €104.0 million today.
Uncover why Melexis' fair value indicates a 33% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You are not the only one asking whether the Pune expansion and confirmed H2 2026 guidance really shift the dial for Melexis. The lowest analysts build their story around weaker pricing power and more modest outcomes. They were only pencilling in €1.1b of revenue and €167.9 million of earnings by 2029 before this news, which is a far more cautious path. Those views can adjust as fresh information arrives, so treat them as one reference point and compare several angles before you decide how this update fits your own electrification thesis.
Explore 3 other Melexis fair value estimates, including one that suggests it could be worth just €71.23.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgement.
- A great starting point for your Melexis research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Melexis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Melexis' overall financial health at a glance.
Looking for more Melexis-sized investment ideas?
If the Melexis story has you thinking about where else electrification, capital discipline and balance sheet strength might show up, it can help to widen the lens and scan a broader list of companies with similar traits.
- For investors who want potential mispricing combined with solid fundamentals, scan a hand picked pool of companies screened as 225 high quality undervalued stocks.
- If resilience matters more to you than fast growth, focus on businesses flagged as having relatively lower risk profiles through the 212 resilient stocks with low risk scores.
- To emphasise financial strength and liquidity, filter for companies with sturdier finances by using the list of solid balance sheet and fundamentals (193 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com