


EN
Should Margin Pressure Fears Require Action From Cisco Stock Investors?
- Cisco Systems expanded its partner and cloud portfolio, adding Cisco IQ for Partners, new incentives, AI focused tools and quantum resilient networking products to tie more revenue to software, telemetry and lifecycle services around AI era infrastructure.
- The same push into AI hardware, cloud control platforms and richer partner incentives brings higher hardware mix and cost pressure that could weigh on gross margins, which has become a key concern in recent research commentary.
- We will now look at how Cisco Systems' investment narrative could shift given fresh concern around AI related gross margin pressure.
Scan how Cisco Systems’ AI networking push compares with peers by running the same filter used to surface 52 AI infrastructure stocks that could see momentum as AI buildouts continue.
Cisco Systems Investment Narrative Recap
For Cisco Systems, the core belief is that AI era networking, security and software subscriptions can keep expanding even as hardware intensity puts strain on gross margin. The short term swing factor is how well upcoming earnings and guidance on November 12 line up with expectations for AI driven orders and subscription traction, especially after the recent share price pullback.
The biggest risk right now is that a heavier hardware mix, higher component costs and hyperscaler AI pricing pressure keep eroding margin faster than software, telemetry and services scale. The new partner incentives and AI centric tools are important, but on their own they do not yet change that margin equation in a material way.
The most relevant operational update tied to this debate is Cisco Cloud Control with Cisco IQ for Partners and the broader partner program refresh. These tools give resellers and service providers more telemetry, lifecycle hooks and deal level economics, which relates directly to the push toward recurring software and support tied to AI infrastructure.
If partners lean into Cisco IQ, MCP servers and the richer 360 Partner Program incentives, the setup could reinforce the main catalyst investors focus on: converting US$9.3b of hyperscale AI orders and broader enterprise refresh demand into steadier subscription and services revenue. Execution risk is material, especially if gross margin pressure from AI hardware and memory costs persists while this software heavy model scales.
Cisco Systems’ narrative incorporates analyst estimates that point to US$83.4b in revenue and US$20.1b in earnings by 2029. These figures are built on an assumed 9.6% yearly revenue growth rate and an earnings increase of about US$6.8b from US$13.3b today.
Uncover why Cisco Systems' fair value indicates a 46% potential upside to its current price, a discount that could narrow quickly as sentiment resets.
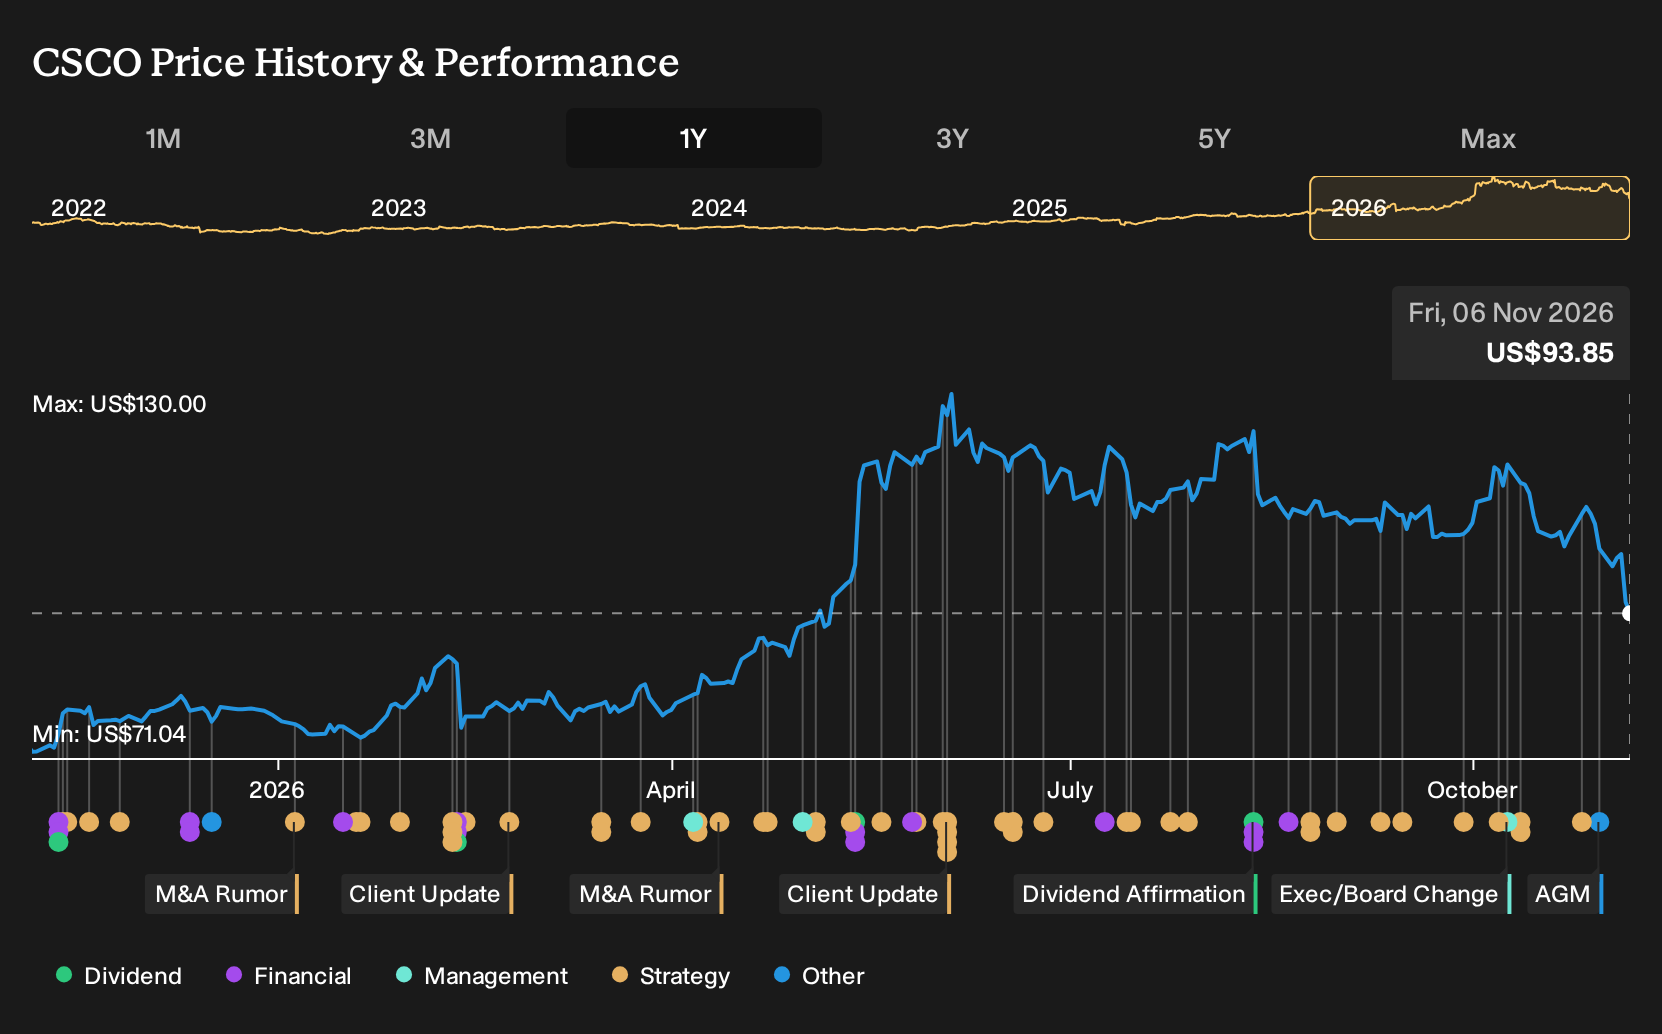
Exploring Other Perspectives
One alternate view focuses on AI hardware concentration risk rather than margin pressure. Under this lens, you worry that Cisco Systems leans too heavily on a handful of hyperscalers. The more cautious analysts model about US$78.0b in 2029 revenue and US$19.3b in earnings, and use a lower 28.8x P/E. Those forecasts sat in place before this partner focused AI update, so it is worth comparing them with the new information and deciding which storyline feels closer to your own expectations.
Explore 5 other Cisco Systems fair value estimates, including one that suggests it could be worth just $110.56.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cisco Systems research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Cisco Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cisco Systems' overall financial health at a glance.
Looking for more investment ideas beyond Cisco Systems?
Once you have formed a view on Cisco Systems, it often helps to compare that thesis with other companies that have very different drivers, risk profiles and income potential.
- If you are drawn to higher risk and potential high reward situations, scan through 9 elite penny stocks with strong financials that meet strict financial quality filters rather than pure speculation.
- For investors who want quality at a measured price, review the 39 high quality undervalued stocks that combine stronger fundamentals with more modest valuations.
- If consistent income is a priority, focus on the 8 dividend fortresses that pair elevated yields with an emphasis on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com