


EN
Skyward Specialty Insurance Group (SKWD) Stock Looks Fully Priced As Third Quarter Results Impress
Skyward Specialty Insurance Group has delivered a powerful share price run in recent years, which naturally raises the question of whether the current valuation is still grounded in its earnings power. With the stock recently closing at US$60.35, the key issue for you is how much of the company’s profit profile is already reflected in that price.
- Over the past 3 years the stock has returned 97.7%, which puts real pressure on the question of whether the present earnings base can carry that kind of re-rating.
- Management has highlighted profitable underwriting with a combined ratio below 100% and solid returns on equity, which can support a view that earnings quality rather than just top line volume is driving the story.
- There is a second opinion on Skyward Specialty Insurance Group worth weighing. See what analysts think Skyward Specialty Insurance Group's shares could be worth.
The issue now is whether Skyward Specialty Insurance Group’s current share price is adequately supported by the earnings it is generating today.
If you want to test the same earnings question that hangs over Skyward Specialty Insurance Group across a wider set of candidates, take a look at 39 high quality undervalued stocks.
Does Skyward Specialty Insurance Group Look Fairly Valued on Earnings?
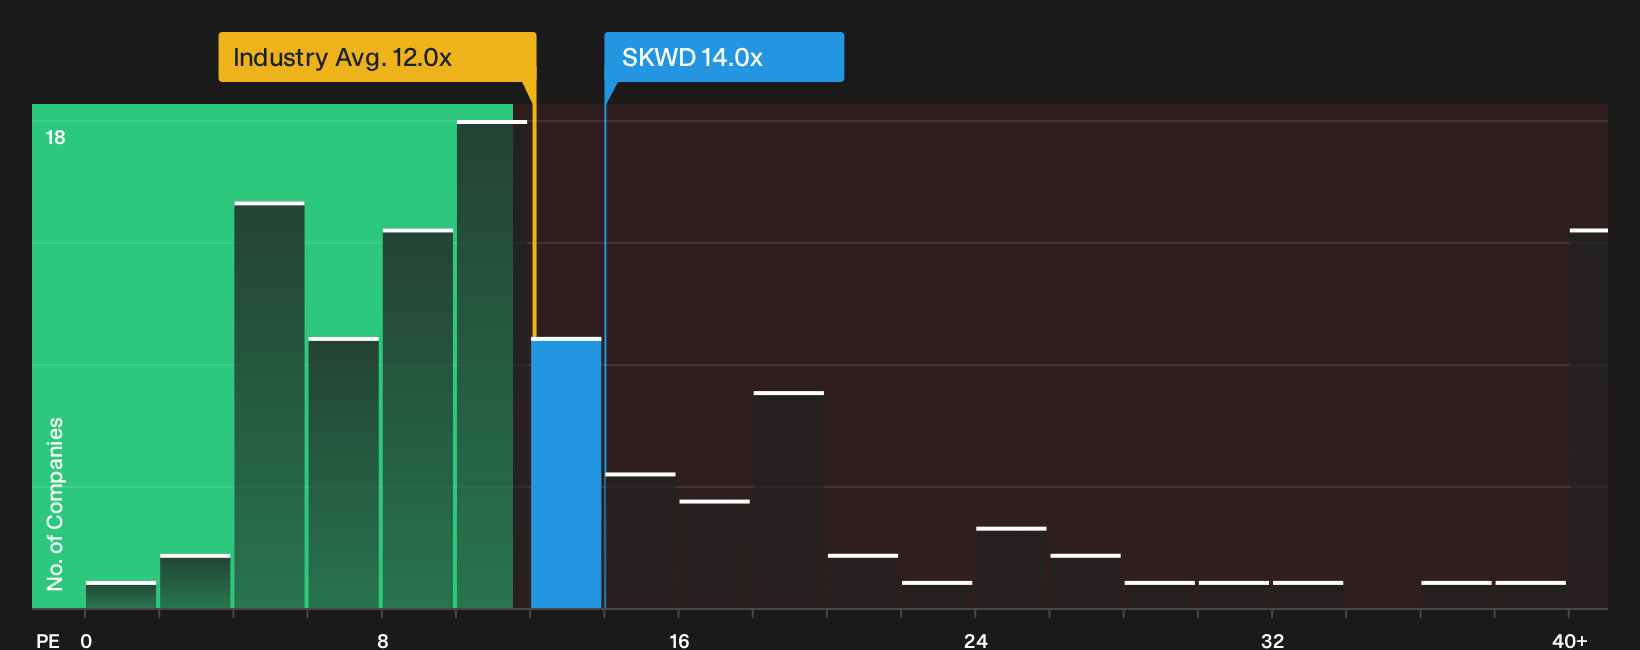
The P/E ratio fits Skyward Specialty Insurance Group well because investors focus heavily on its earnings track record and underwriting discipline. On this measure, the stock trades on a P/E of about 14.0x, a modest premium to the insurance industry average of roughly 12.0x and more than double the peer group level near 6.3x. The excess returns model points to a tailored fair P/E that is close to where the shares change hands, so the current earnings multiple sits in the same general zone as what that framework would suggest.
Because the recent third quarter report flagged a combined ratio of 89.9% and a 20.4% operating return on equity, the market appears willing to pay somewhat more per dollar of profit for Skyward Specialty Insurance Group than for a typical insurer. Even with that support from reported profitability, the present valuation still leaves you judging whether this premium earnings tag feels justified by the sustainability of those economics and your own risk tolerance. Explore the numbers behind Skyward Specialty Insurance Group's P/E valuation.
The Skyward Specialty Insurance Group Narrative: What Would Justify Today's Price?
Narratives for Skyward Specialty Insurance Group pick up where the valuation question leaves off and spell out which paths for future growth, margins and earnings would need to hold for today’s price to look either restrained or stretched. Each scenario links a fair value to a concrete thesis about Skyward Specialty Insurance Group's potential catalysts and key risks, so you can track over time which version of the story is actually unfolding.
Community views on Skyward Specialty Insurance Group split between those who see more to come from its specialty and fee income story and those who think a lot is already priced in.
Bull case: 14% undervalued
"The Apollo Lloyd's platform is growing fee generating gross written premiums and underwriting fee income on a capital light basis, and management reiterates guidance for full year net underwriting fee income..."
Discover why this Narrative puts Skyward Specialty Insurance Group at 14% undervalued.
Bear case: 6% overvalued
"Although technology, machine learning and Agentic AI are helping reduce the expense ratio and speed up underwriting, management acknowledges that these investments are expensive and must be made ahead of realized benefits..."
Explore why this Narrative puts Skyward Specialty Insurance Group at 6% overvalued.
Before acting on Skyward Specialty Insurance Group's valuation, weigh who is steering it
Price and earnings only tell part of the story for Skyward Specialty Insurance Group, because the people making capital calls and how they are rewarded can tilt your risk in ways this analysis has not addressed. See who runs Skyward Specialty Insurance Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com