


EN
Has J. M. Smucker (SJM) Become Overvalued After Its 35% Rise?
J. M. Smucker has had a strong run in 2026, which puts fresh focus on whether the current share price still matches the earnings power behind the brand portfolio. With the stock now reflecting a year of solid gains, investors are starting to ask if the earnings multiple is doing too much of the heavy lifting.
- The share price is up 35.1% year to date, which raises the stakes on whether current earnings can carry that kind of move.
- Uncrustables topping US$1b in sales and moving into a refrigerated format can support expectations for future earnings and cash generation if volumes and pricing hold up.
- There is a second opinion on J. M. Smucker worth weighing. See what analysts think J. M. Smucker's shares could be worth.
For investors, the debate is whether J. M. Smucker's current earnings profile is strong enough to justify where the shares trade today.
If you are weighing J. M. Smucker's 35.1% year to date move against its earnings, it can help to compare that question with 39 high quality undervalued stocks.
Has J. M. Smucker Run Too Far on Earnings?
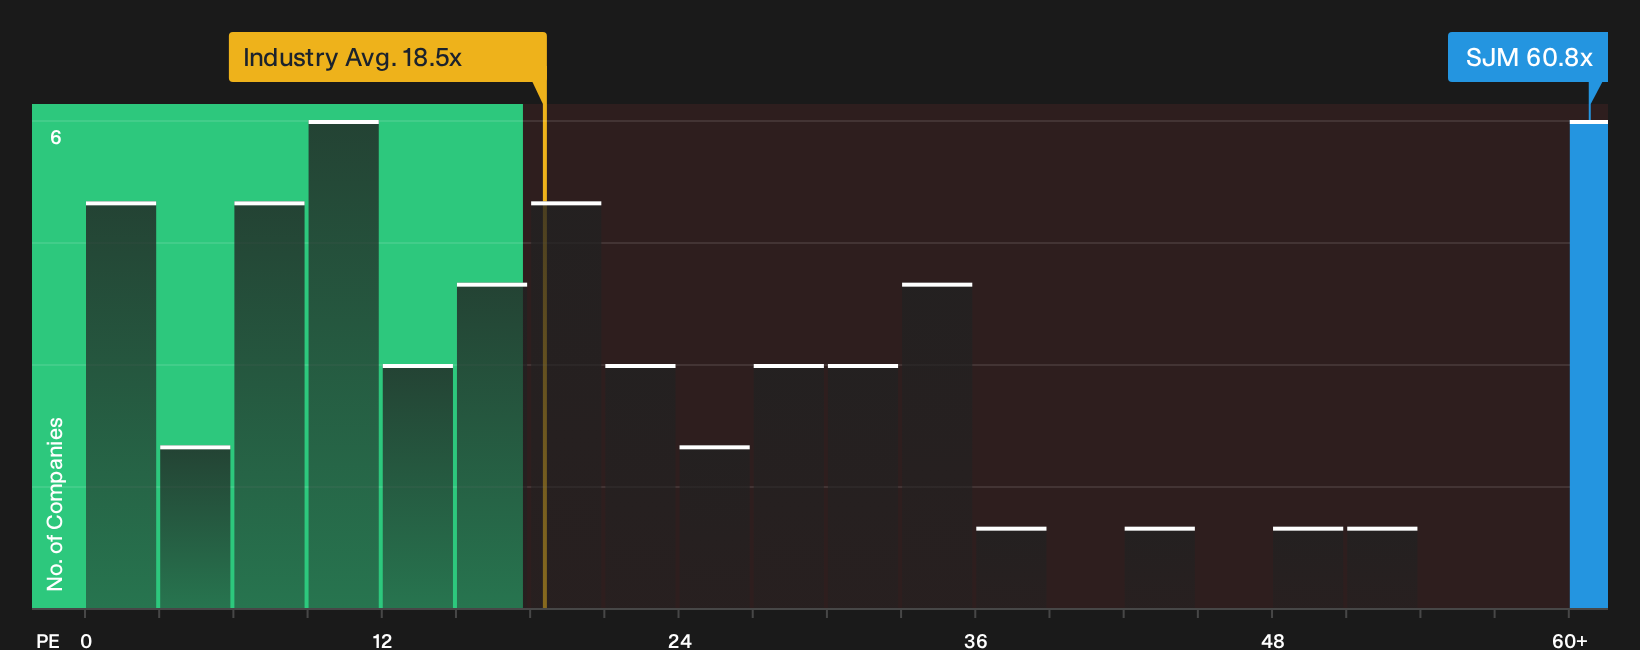
For a brand-heavy food group like J. M. Smucker, a P/E ratio gives a clean read on what investors are willing to pay for each dollar of earnings. On that yardstick, the stock trades on roughly 60.8x, which is far above both the Food industry average of about 18.5x and the peer group at roughly 23.1x.
Because the current multiple sits well above what a tailored fair P/E would suggest, the shares screen as overvalued on this measure. The premium hints that the market is already assigning a rich price to the portfolio, including Uncrustables, even as the new refrigerated launch and the legal dispute around copycat products keep that brand in the headlines. Anyone buying J. M. Smucker at today’s level is paying a high price for its earnings stream relative to sector norms and peer expectations. Explore the numbers behind J. M. Smucker's P/E valuation.
The J. M. Smucker Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for J. M. Smucker leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the valuation to move meaningfully higher or lower from today's price, and they sit on the platform's Community page. Each one connects its number to a clear view on how J. M. Smucker's growth, margins and risk profile might evolve, which you can come back to as fresh information is released.
Bulls in the J. M. Smucker community lean heavily on cash generation from growth brands, while bears focus on whether margin pressure and execution risks cap what the stock is worth.
Bull case: 8% undervalued
"The main factor that has to go right is that J. M. Smucker converts momentum in core growth brands and ongoing cost discipline into sustained free cash flow around the current US$1.1 billion level..."
Discover why this Narrative puts J. M. Smucker at 8% undervalued.
Bear case: 8% overvalued
"The assumed bearish price target for J. M. Smucker is $120.66, which represents up to two standard deviations below the consensus price target of $142.12..."
Explore why this Narrative puts J. M. Smucker at 8% overvalued.
The J. M. Smucker valuation still leaves one key issue unresolved
Price and earnings are only half the story for J. M. Smucker, because our broader checks also raise specific risk flags that investors may want to review before deciding what the valuation really means. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com