


EN
G Mining Ventures (TSX:GMIN) Gains On Gold And Output, Is The Upside Already Priced In?
G Mining Ventures (TSX:GMIN) moved into focus after a 13.97% share price jump on November 4, 2026, as rising gold prices aligned with higher output from its Tocantinzinho mine in Brazil.
Recent trading shows that momentum around G Mining Ventures has picked up again, with a 1 day share price return of 4.61% and a 7 day gain of 24.73%, even though the 30 day and 90 day share price returns declined 2.30% and 6.05% respectively.
For investors looking beyond the latest move, the share price return year to date of 23.68% sits alongside a 1 year total shareholder return of 68.01%. The 3 year and 5 year total shareholder returns are reported at more than 8x and 11x respectively, indicating that the latest jump comes on top of an already strong longer term track record.
Ride this momentum in G Mining Ventures by comparing it with a hand picked 33 elite gold producer stocks that are also reacting to the move in gold prices and production stories.G Mining Ventures now carries a track record and a story around Tocantinzinho that many investors would call strong. After this latest surge, the real tension is whether that quality is already fully reflected in the price.
Most Popular Narrative: 26% Undervalued
The most followed narrative pegs fair value for G Mining Ventures at CA$63.46, compared with the last close of CA$47.21. This helps put the recent share price surge into context for anyone weighing potential upside against execution risk.
The TZ mine is operating with total cash costs of $748 per ounce and all in sustaining costs of $1,155 per ounce in 2025, which are described as peer leading. Management aims to keep focusing on productivity and cost management, which could help protect margins and earnings if industry wide cost pressures persist.
See why 14 investors see G Mining Ventures as 26% undervalued.
Result: Fair Value of CA$63.46 (UNDERVALUED)
Still, the bullish narrative around G Mining Ventures can be knocked off course if gold prices weaken for a long stretch or if Oko West construction runs into delays or cost overruns.
Find out about the key risks to this G Mining Ventures narrative.
Another View On G Mining Ventures’ Valuation
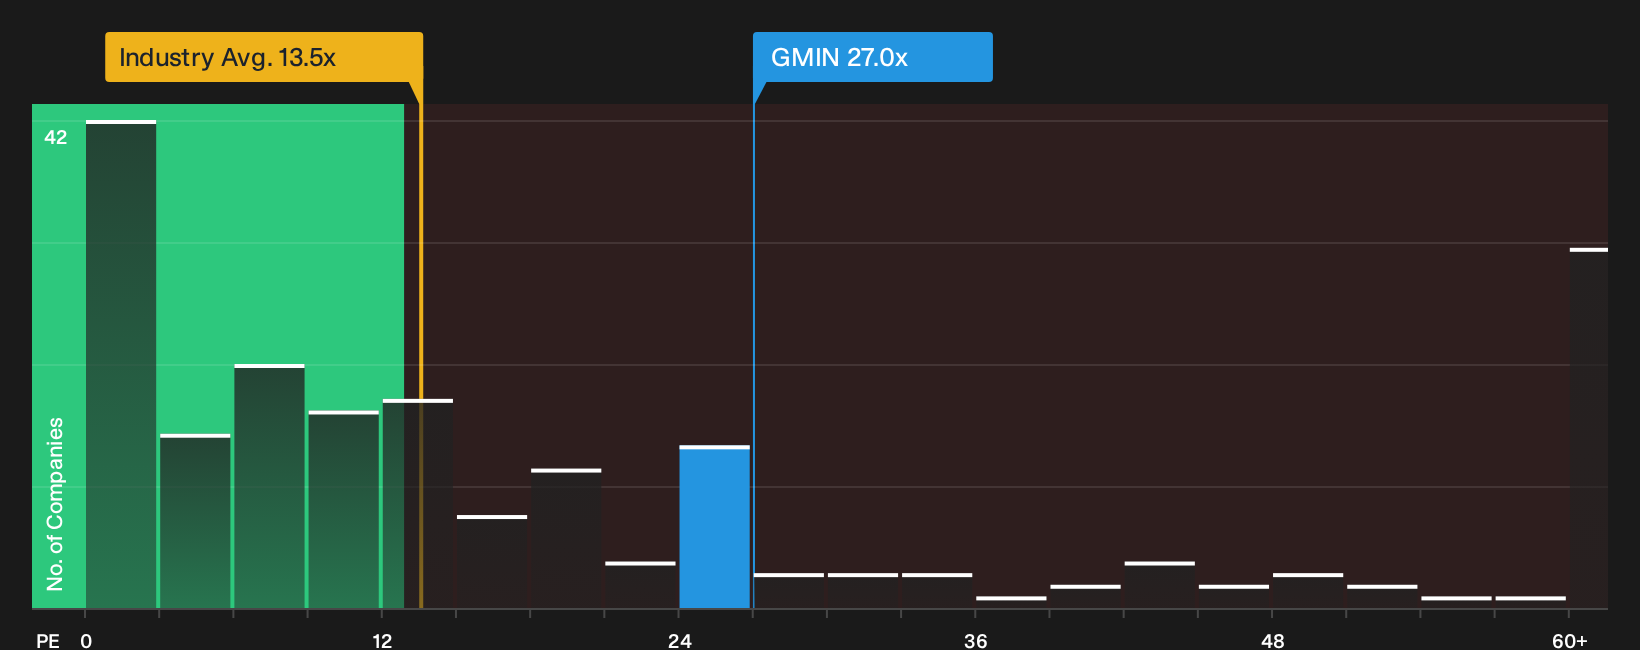
The story looks different once price multiples are brought into the picture. G Mining Ventures trades on a P/E of 27x, compared with 12.5x for peers and 13.5x for the Canadian Metals and Mining group, while the fair ratio is estimated at 22.5x. That kind of gap suggests investors are already paying up for the growth story, so the real question is whether you are comfortable paying a richer tag than both sector and fair ratio imply.
Before leaning too heavily on any single metric, it helps to see how the rest of the numbers stack up in the full valuation breakdown. You can then weigh that against your own expectations for gold prices, project execution and future cash generation. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Still unsure whether the recent enthusiasm around G Mining Ventures reflects your own view, or feels a step ahead of the fundamentals? Move quickly, pull up the full data set, then weigh the upside story against the caution flags in 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond G Mining Ventures?
If G Mining Ventures has your attention, do not stop here. Use the Simply Wall St Screener to spot other opportunities before they move without you.
- Target potential bargains by scanning a curated 6 high quality undervalued stocks that combines quality fundamentals with prices that may not fully reflect them yet.
- Strengthen your downside protection by focusing on a list of solid balance sheet and fundamentals (5 results) so you are not relying only on optimism for returns.
- Get ahead of the crowd by reviewing a 7 high quality undiscovered gems that have strong numbers but still sit off most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com