


EN
Did Chip Design Platform Deal Just Shift Synopsys (SNPS) Investment Narrative?
- Synopsys announced an agreement with the European Chips Joint Undertaking to supply its electronic design automation tools through the European Chips Design Platform, giving startups and mid sized chip companies across Europe access to front end and back end design flows, IP, training, funding and prototyping support.
- The arrangement deepens Synopsys' role in AI and high performance computing oriented chip projects in Europe by tying its tools directly into a publicly backed program that aims to reduce design barriers for emerging semiconductor ventures.
- We will now look at how Synopsys' investment narrative ties into this new European Chips Design Platform access for younger chip designers.
Scan beyond Synopsys and explore other chip and AI hardware enablers that could benefit from similar demand tailwinds through our hand picked 52 AI infrastructure stocks.
Synopsys Investment Narrative Recap
To own Synopsys, you need to believe its EDA tools, IP portfolio and Ansys simulation platform remain central to how complex chips are built, particularly for AI and high performance computing. The biggest near-term swing factor is whether Ansys integration and cost actions support the margin lift that management is targeting without disrupting execution.
The new European Chips Design Platform deal connects Synopsys more deeply with early-stage European projects, but it does not change that core near-term catalyst. The largest current risk still lies in IP, where slower progress, together with restructuring noise and litigation costs, could keep margins and free cash flow under pressure.
The upcoming fourth-quarter and fiscal 2026 earnings release on 8 December 2026 now sits alongside the European Chips Design Platform agreement as a key check-in point. That update will show how the combined Synopsys and Ansys portfolio is tracking on revenue, and how much of the planned US$400 million in cost synergies is flowing through expenses.
For you as an investor, the conference call is where execution on catalysts becomes more visible. Listen for detail on EDA demand tied to AI and multi-die designs, progress in higher-value Design IP work and any change in outlook for restructuring charges or litigation. Those operational data points matter more than short-term share price moves.
Synopsys' narrative projects US$13.6b revenue and US$2.6b earnings by 2029. This assumes 13.1% yearly revenue growth and an earnings increase of about US$1.5b from US$1.1b today.
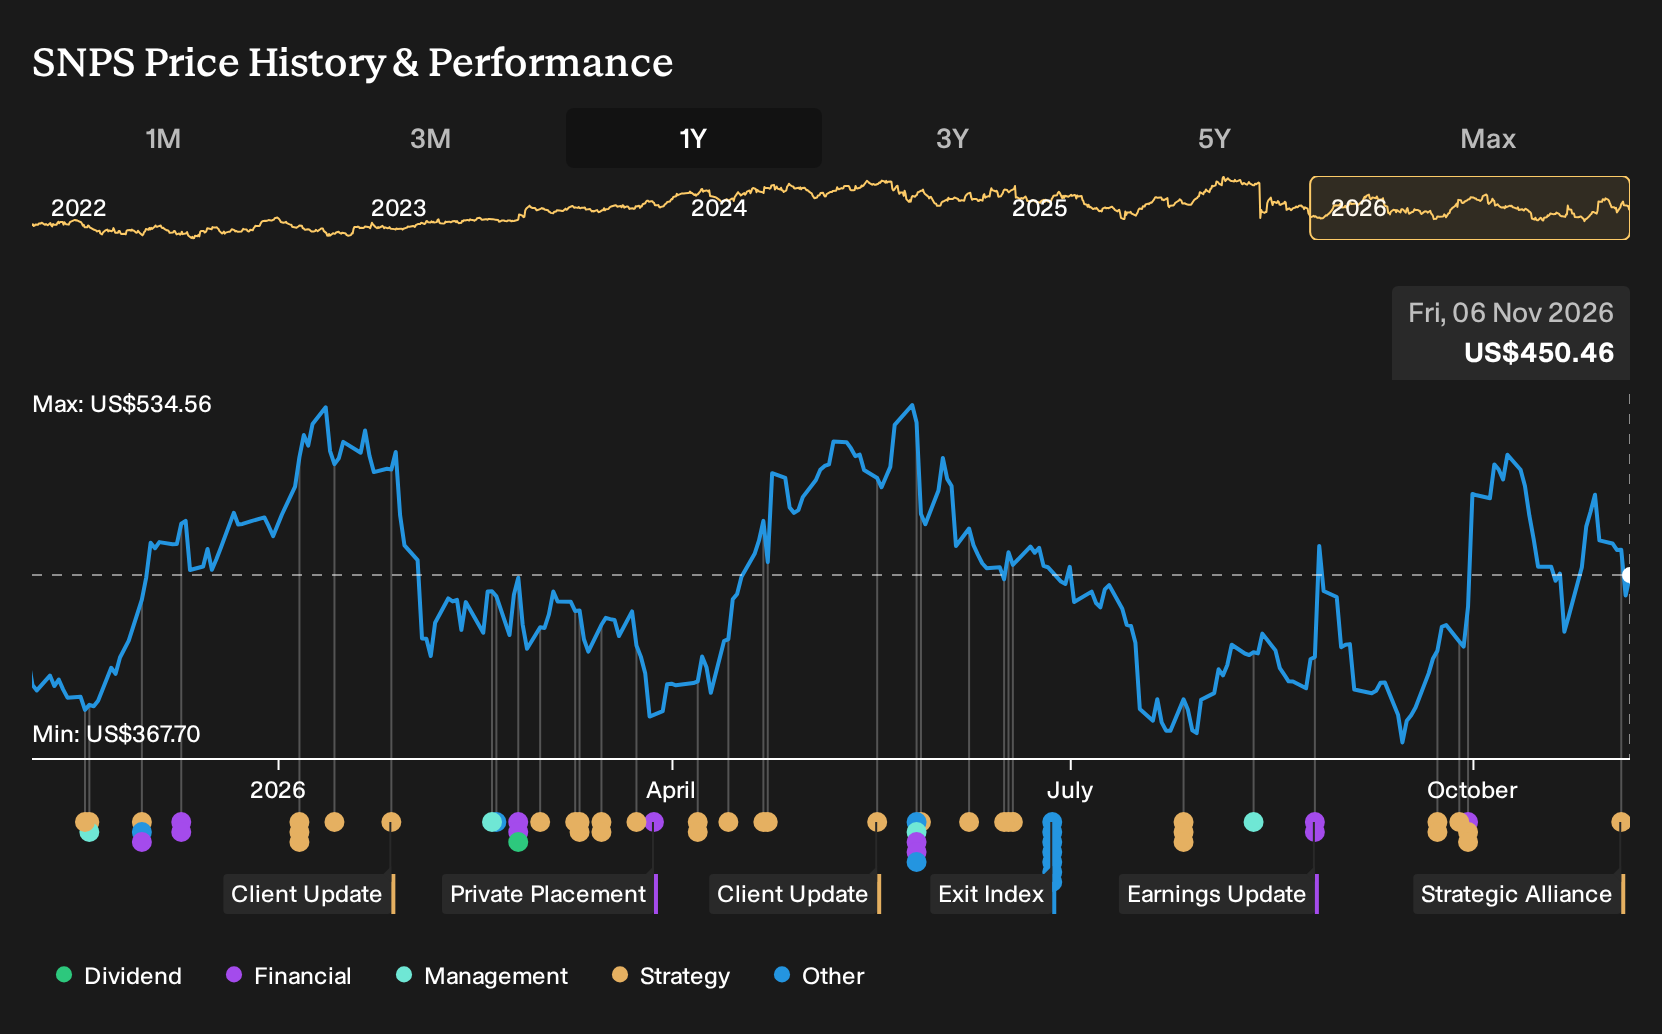
Uncover why Synopsys' fair value indicates a 30% potential upside to its current price. This gap could narrow faster than many investors expect.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$386 to US$584 per share, so private investors there already show a wide gap on Synopsys. When you layer in the Ansys integration risks, IP uncertainties and the new European Chips Design Platform exposure, you get very different potential return paths. Explore those contrasting views.
Explore another Synopsys fair value estimate, including one that suggests there may be as much as 30% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Synopsys research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Synopsys. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Synopsys' overall financial health at a glance.
Looking For More Investment Ideas Beyond Synopsys?
Once you have a view on Synopsys, it helps to widen the lens. Different types of companies respond differently to the same macro backdrop, and using a structured screener can surface opportunities that fit the risk and return profile you actually want, not the one your social feed is serving you.
- If you want potential upside along with a margin of safety, focus on quality at a discount and scan through our 39 high quality undervalued stocks.
- For steadier income and a focus on resilience, concentrate on payout strength and coverage by reviewing our 8 dividend fortresses.
- When capital preservation sits at the top of your list, start with financial strength and funding flexibility using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com