


EN
Why SCHOTT Pharma KGaA (XTRA:1SXP) Is Back In The Spotlight
SCHOTT Pharma KGaA (XTRA:1SXP) came under pressure after RBC Capital Markets cut its rating to sector perform, citing a stretched valuation recovery and uncertainty around future GLP-1 related order volumes.
The downgrade came during a weak stretch for SCHOTT Pharma KGaA, with the share price down 13.0% over the past week and 13.5% over the last month. However, the year-to-date share price return of 47.8% and 1-year total shareholder return of 22.4% still point to earlier momentum that has been fading as GLP-1 order risks move into focus.
Spot potential alternatives to SCHOTT Pharma by scanning a curated group of defensive healthcare names, screened for resilient fundamentals, in our 212 resilient stocks with low risk scores.SCHOTT Pharma KGaA still looks like a solid specialist in injectable drug packaging, yet the recent pullback and GLP-1 order questions shift the focus to valuation. Is that quality now being offered at a reasonable price?
Most Popular Narrative: 13% Undervalued
The most followed narrative currently places SCHOTT Pharma KGaA’s fair value at €24.92, compared with the last close at €21.75. This puts the recent selloff in a different light for anyone focused on long term cash flows and capacity build out.
Expansion of vial, syringe and cartridge capacity in the U.S., Switzerland and Hungary, including the BARDA backed investment of over US$60 million in Pennsylvania and the ongoing HVS projects in Europe, positions SCHOTT Pharma KGaA to capture local for local demand and support future revenue and EBITDA as utilization improves.
See why 5 investors see SCHOTT Pharma KGaA as 13% undervalued.
Result: Fair Value of €24.92 (UNDERVALUED)
Still, the SCHOTT Pharma KGaA story can change quickly if Drug Delivery Systems margins stay compressed or if GLP 1 related order visibility weakens further.
Find out about the key risks to this SCHOTT Pharma KGaA narrative.
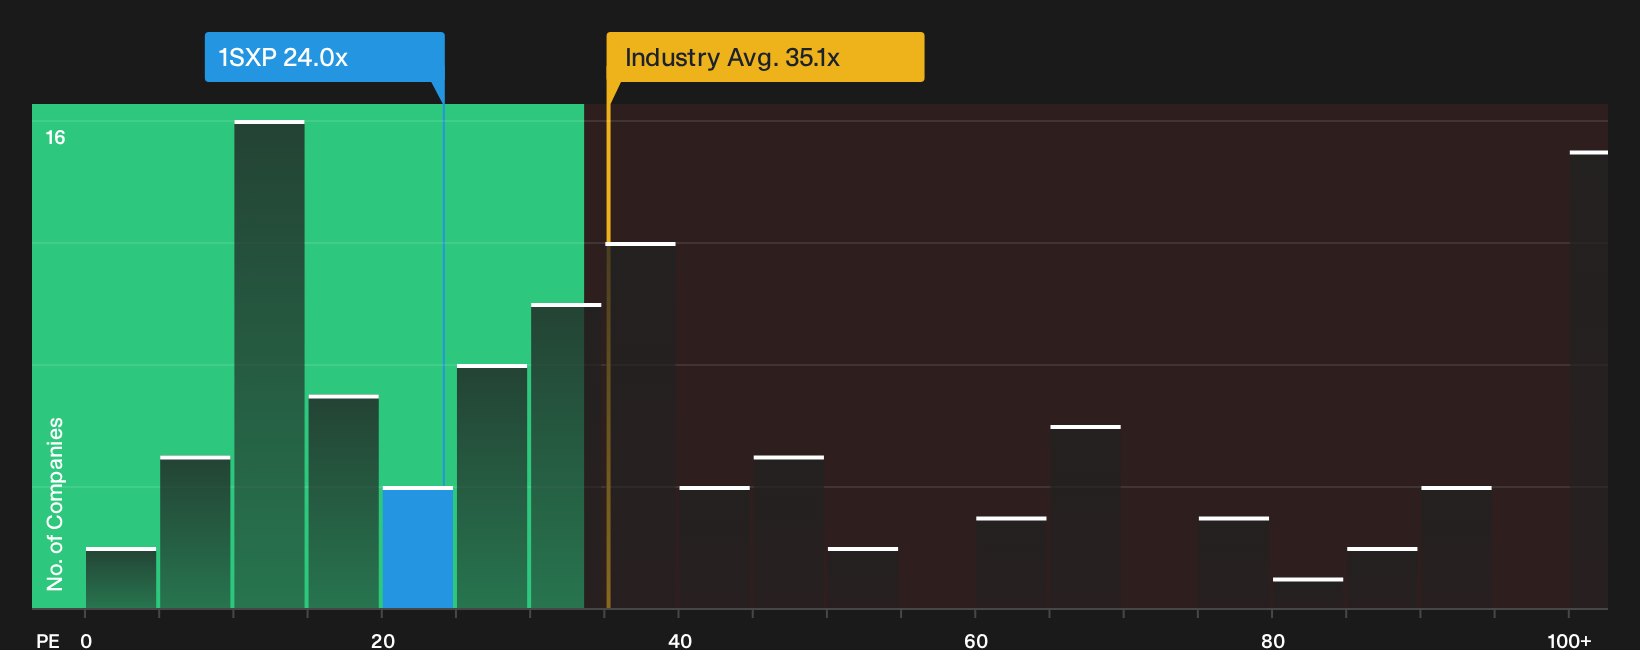
Another View: What SCHOTT Pharma KGaA’s P/E Is Telling You
The earlier story leaned on future cash flows. A simpler lens uses the current P/E of about 24x, which screens as good value against global Life Sciences peers on 35.1x and a closer peer set near 36.4x. Set that against a fair ratio of 18.4x, and the gap starts to look like a trade off between paying up for quality and accepting some valuation risk. Which side of that line are you more comfortable on as GLP 1 order visibility shifts?
To unpack how that P/E gap could evolve over time, and whether the current price lines up with earnings power, take a closer look at our valuation breakdown, including the fair ratio context, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Views on SCHOTT Pharma KGaA in this article may sound confident, yet the real edge comes from testing the data yourself and moving quickly. To weigh those potential upsides against the uncertainties, start by reviewing the 2 key rewards.
Looking for more investment ideas beyond SCHOTT Pharma KGaA?
If SCHOTT Pharma KGaA is on your radar, do not stop there. A few minutes with the right screeners can surface opportunities you would otherwise miss.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (193 results) that filters for companies built to handle shocks.
- Hunt for quality at a discount by reviewing the 225 high quality undervalued stocks and see which businesses trade below what their fundamentals might justify.
- Build a cash flow focused watchlist through the 232 dividend fortresses and spot stocks offering higher yields supported by underlying financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com