


EN
Verisk Analytics (VRSK) Earnings Beat Puts Its Valuation Narrative Back In Focus
Verisk Analytics (VRSK) just paired a third quarter earnings beat with higher adjusted EPS, 7.4% organic revenue growth and margin expansion, and then reinforced that message with a higher dividend and fresh share repurchases.
The recent report lit a fire under Verisk Analytics’ share price, with a 1 month share price return of 21.3% and a 7 day gain of 4.2%, even after a 3.3% pullback on the day of the release. That short term surge contrasts with a softer picture in the rearview mirror, where the total shareholder return has declined 3.7% over 1 year and 12.1% over 3 years. This suggests the latest rally reflects a reset in how investors are weighing the company’s cash generation, AI driven product rollout and perceived risk, rather than a long uninterrupted winning streak.
Scan how Verisk Analytics’ AI driven insurance tools fit into a wider opportunity set by comparing it with 41 profitable AI stocks that aren't just burning cash riding similar earnings and product momentum.
After that sharp reset in Verisk Analytics’ share price, the practical question for you is simple. Does the current tag still leave enough upside in the risk reward to justify fresh money going in?
Most Popular Narrative: 166% Overvalued
Esteban’s widely followed narrative puts Verisk Analytics’ fair value at $76.85, far below the recent $204.59 close, which frames the current rally in a very different light for anyone focusing on long term cash flows.
Verisk Analytics is a regulatory-grade data toll on the US property & casualty insurance industry, monetized through ~83% subscription revenue with ~92% client retention. VRSK's narrow-moat franchise produces FCF with an unusually high degree of predictability, durable enough to justify a 15× exit multiple at a 35% margin of safety. The 2022 to 2025 portfolio simplification (Energy, Argus, 3E, Marketing Solutions all divested) has produced a cleaner pure-play with structurally higher margins (Adj EBITDA 56.2% in 2025 vs. 53.5% in 2023) and a shrinking share count (~19% reduction since 2019). What the investor is paying for here is a regulatory annuity with an embedded MSD price-and-volume escalator, and walking away from any thesis premised on this becoming a HSD-to-DD revenue compounder.
See why 7 investors see Verisk Analytics as 166% overvalued.
Result: Fair Value of $76.85 (OVERVALUED)
Still, Verisk Analytics faces real swing factors, including any setback to its subscription retention and the risk that divestments could weaken its data advantage.
Find out about the key risks to this Verisk Analytics narrative.
Another View On Verisk Analytics’ Valuation
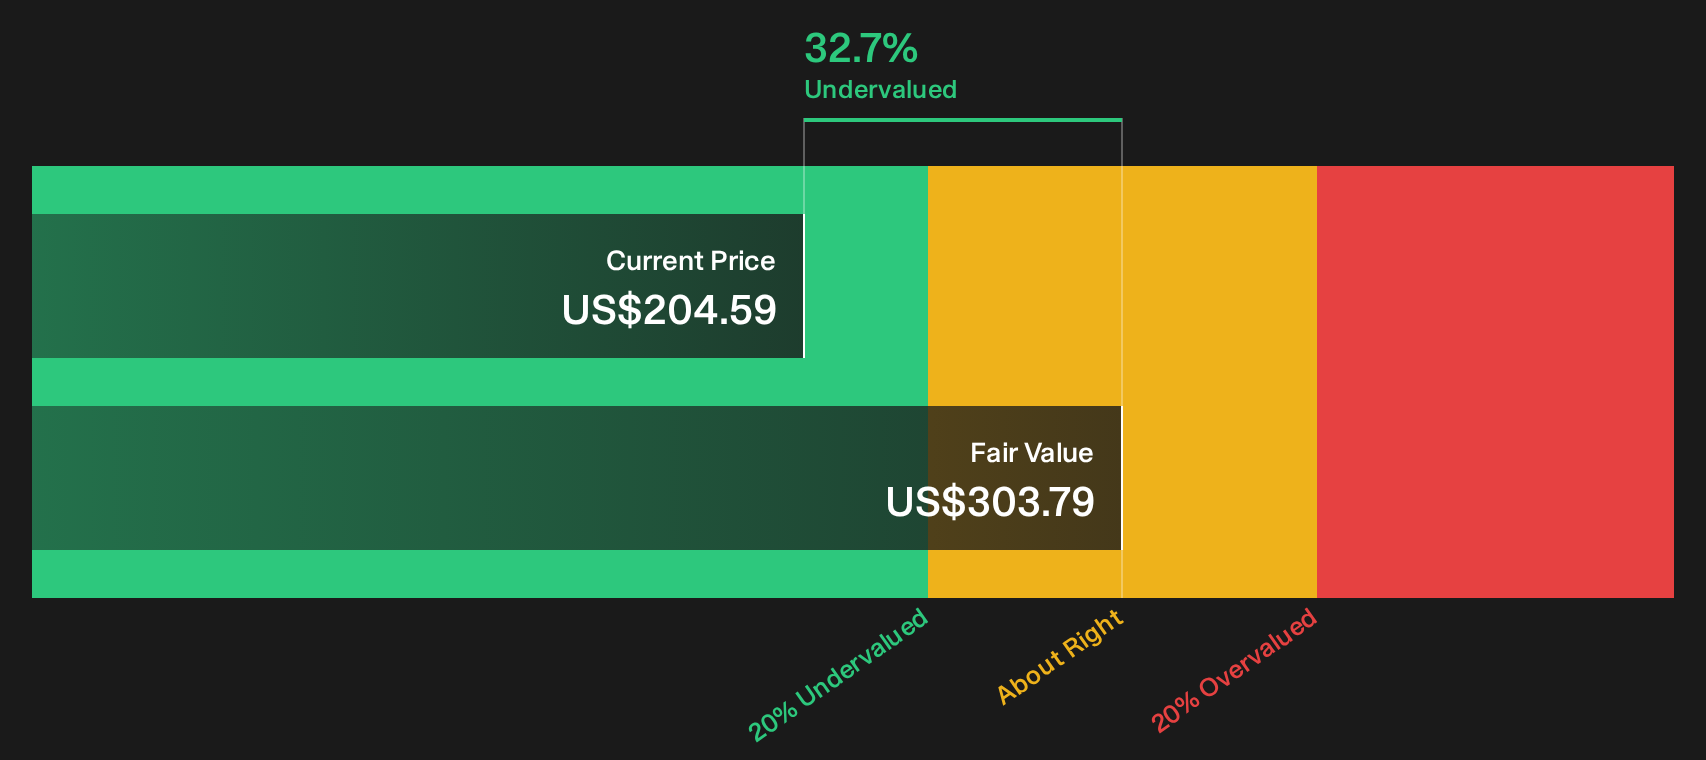
Esteban’s narrative points to Verisk Analytics being heavily overvalued, yet our DCF model presents a very different picture. At $204.59, the stock is trading at about a 33% discount to an estimated future cash flow value of $303.79. This suggests investors are being compensated for taking on execution and balance sheet risk. Which perspective aligns more closely with how you price risk?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment in this piece is split, with both upside potential and clear pressure points on Verisk Analytics now on the table, so move fast and test the numbers yourself. To weigh those trade offs directly, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Verisk Analytics?
If Verisk Analytics sharpened your focus on quality and risk, do not stop here. Broader context across other opportunities can make your next decision far stronger.
- Hunt for quality at a discount by scanning a 39 high quality undervalued stocks list built to spotlight companies with strong fundamentals trading below their implied worth.
- Build a steadier income base by reviewing a curated group of 8 dividend fortresses that may help anchor your portfolio when sentiment swings.
- Prioritise resilience by screening a 29 resilient stocks with low risk scores that tilts toward businesses with sturdier balance sheets and lower risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com