


EN
Are Earnings Cuts Altering The Investment Case For Tyson Foods Stock?
- Tyson Foods is facing weaker earnings expectations, with analysts cutting projections for current and next fiscal year profit and revenue, while the company still runs a broad protein portfolio across beef, chicken, pork and prepared foods.
- The sharp downgrade in projected quarterly earnings to $0.65 per share, a 43.5% year over year decline, highlights pressure on Tyson Foods' underlying profitability despite its scale and brand presence.
- We will now look at how Tyson Foods' investment narrative could be affected by these sharply reduced earnings expectations and outlook.
Balance out Tyson Foods' pressured outlook by scanning a hand picked 39 high quality undervalued stocks that currently combine stronger fundamentals with more resilient earnings profiles.
Tyson Foods Investment Narrative Recap
To own Tyson Foods, an investor needs to believe the shift toward Prepared Foods and Chicken can steadily reduce reliance on the more volatile Beef segment. The current pressure on earnings expectations puts more weight on execution in these higher margin categories and on maintaining volumes with key retail and foodservice customers.
The near term swing factor is whether operational efficiency and product mix can offset weaker Beef profitability and softer quarterly profit per share. The biggest risk remains prolonged cattle supply tightness and any further cuts to guidance. The recent earnings reset reinforces that risk rather than changing it in a material way.
The most relevant recent development is the sharply lower projection for current quarter earnings of US$0.65 per share, a 43.5% year over year decline. That figure crystallises how much short term profit pressure Tyson Foods is absorbing while still funding brand support, R&D and its chicken genetics rollout.
This earnings reset also arrives after Tyson Foods flagged the possibility of a sizeable Beef operating loss in FY 2026 and trimmed its broader outlook. Together, these updates keep the focus on whether Prepared Foods and Chicken can carry more of the load and on how management executes the ongoing beef plant restructuring without further hits to profitability.
Tyson Foods' current narrative centers on analysts expecting revenue of US$56.2b and earnings of US$2.5b by 2029. This implies relatively flat top line trends and an earnings increase of about US$1.9b from US$574.0m today.
Uncover why Tyson Foods' fair value indicates a 6% potential upside to its current price, which could narrow quickly.
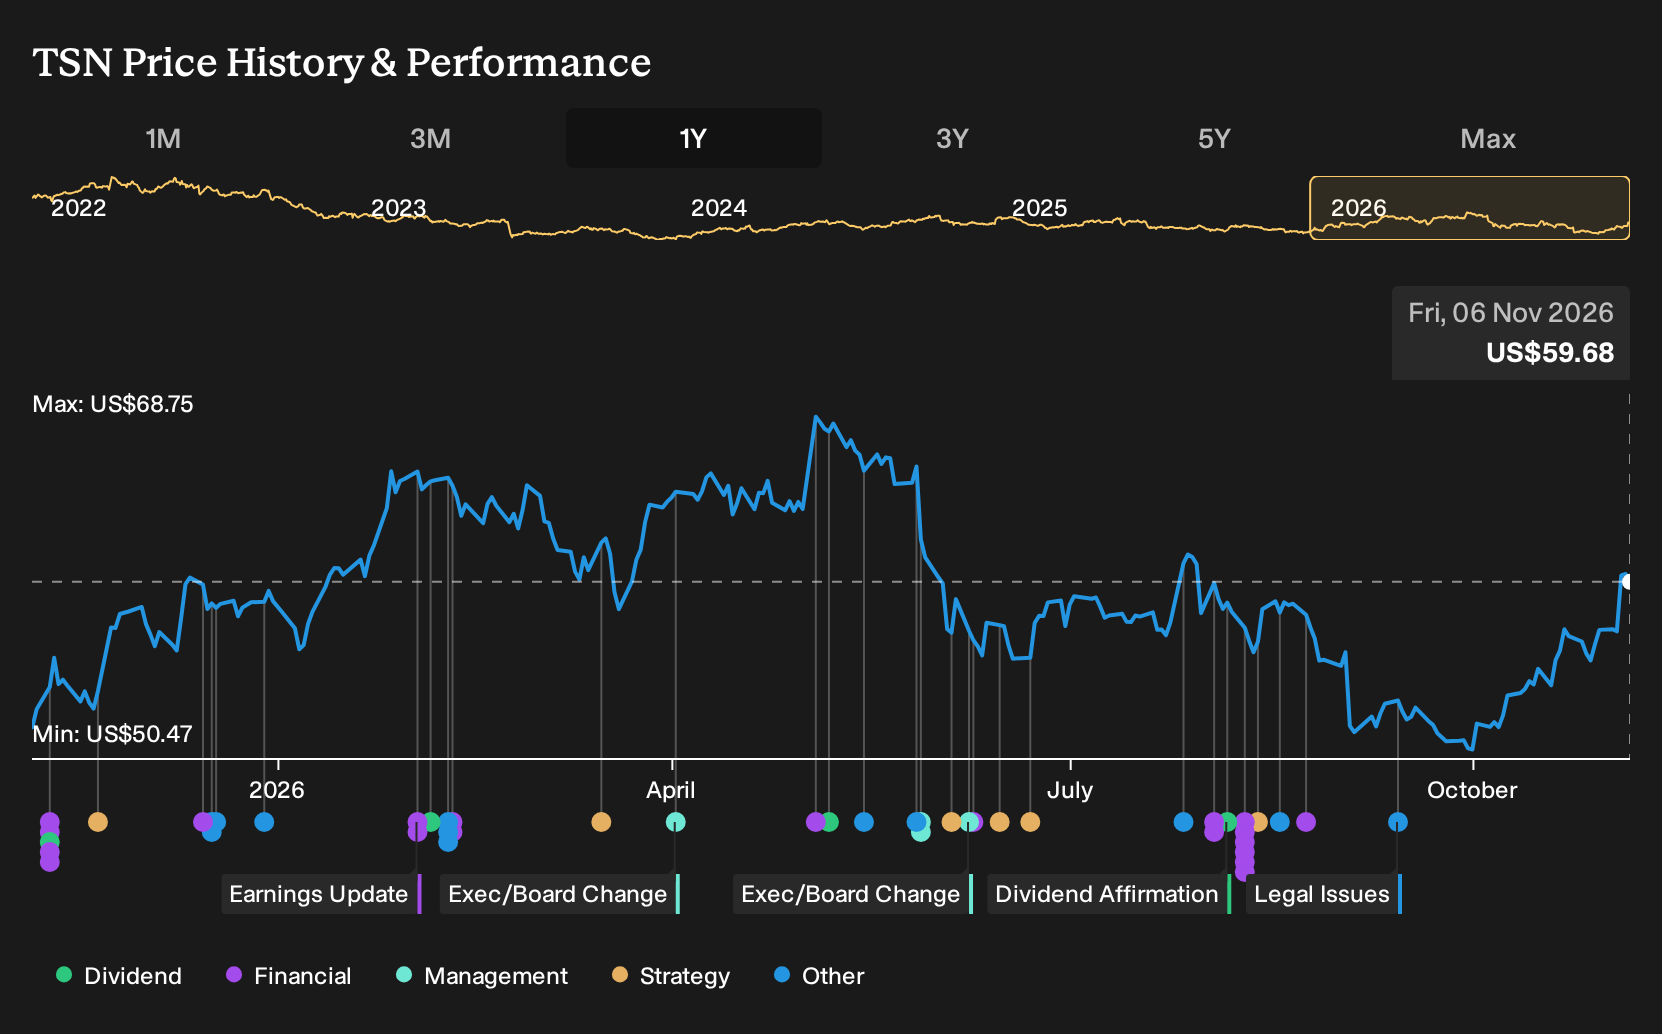
Exploring Other Perspectives
Some of the lowest Tyson Foods forecasts lean into a very different risk. Those analysts were already modelling revenue drifting to about US$50.7b by 2029 and earnings of roughly US$2.1b. That is more cautious than consensus, and the latest earnings reset may push you to reassess which storyline feels closer to reality.
Explore 3 other Tyson Foods fair value estimates, including one that suggests it could be worth just $63.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgement.
- A great starting point for your Tyson Foods research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Tyson Foods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tyson Foods' overall financial health at a glance.
Looking For More Ideas Beyond Tyson Foods?
If Tyson Foods has you rethinking where earnings resilience and balance sheet strength really sit in your portfolio, it can help to line it up against other companies with very different profiles using the Simply Wall St Screener.
- For investors who want income to feel more predictable, scan for companies that currently offer 8 dividend fortresses and compare their payout profiles with Tyson Foods.
- If capital preservation and steadier fundamentals matter most to you, focus on businesses highlighted in our 29 resilient stocks with low risk scores and see how their risk checks stack up.
- When you are hunting for quality that is not yet widely followed, use the screener to surface 19 high quality undiscovered gems that might complement or even rival Tyson Foods in your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com