


EN
Upgraded Sales Outlook Altering The Investment Case For Vicat Stock?
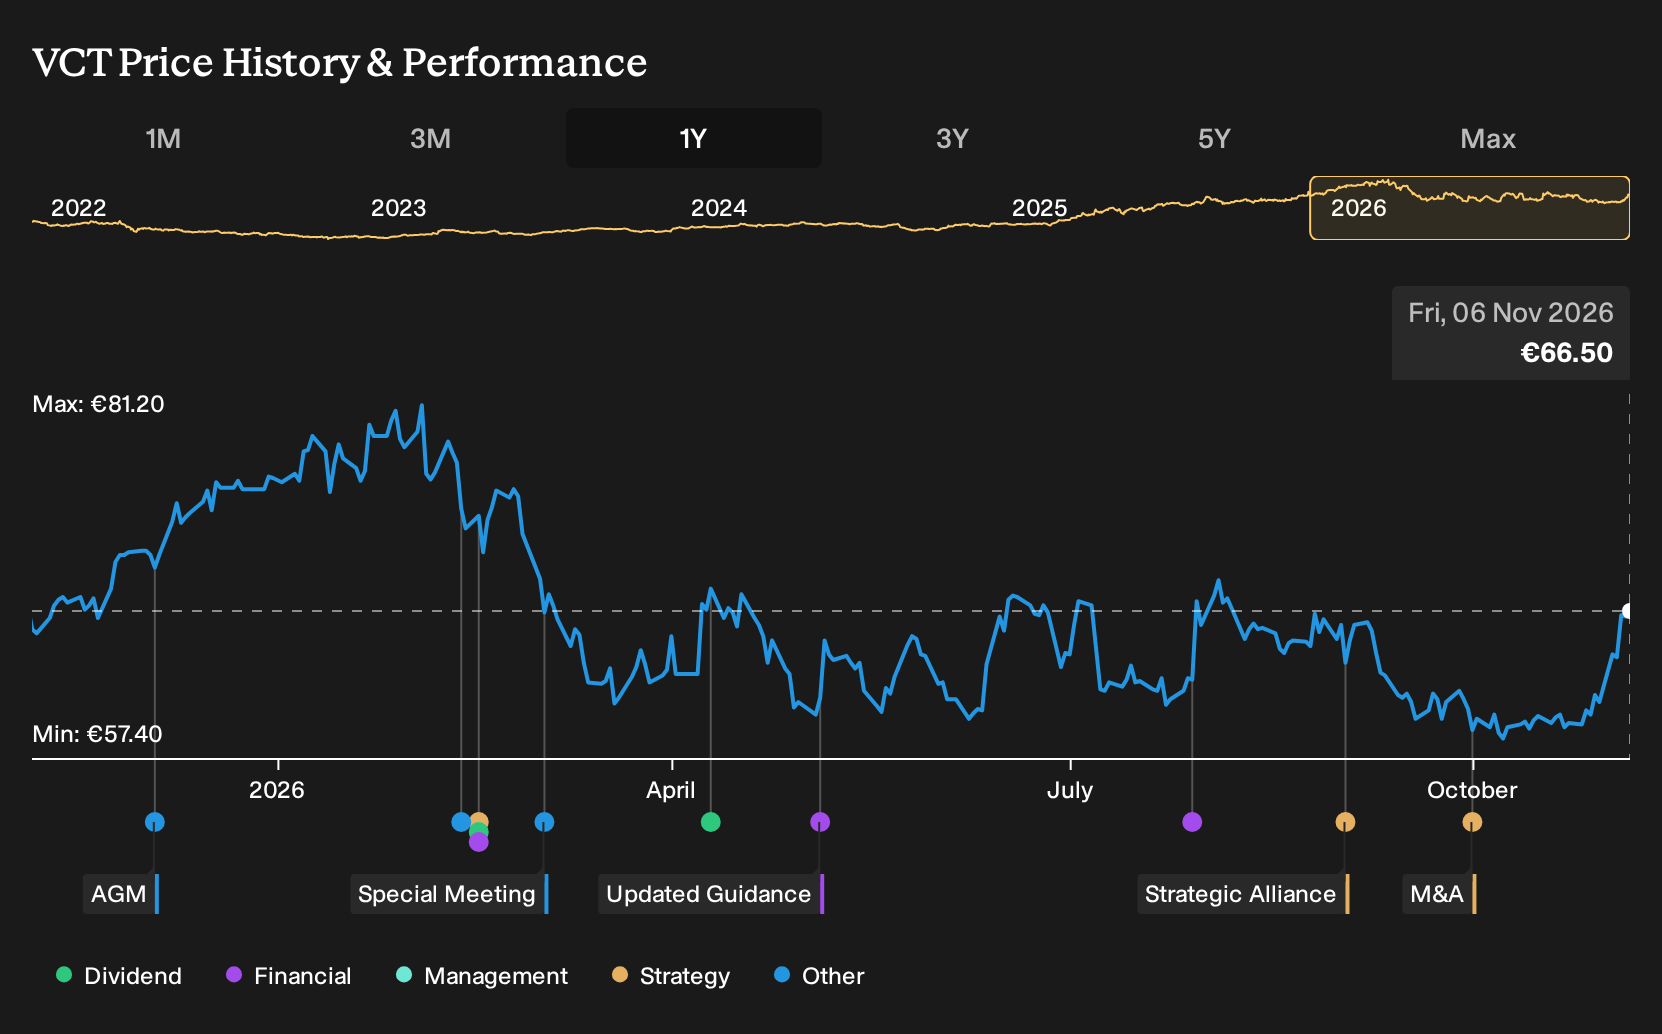
- Vicat reported solid Q3 2026 sales, citing a recovery in the United States and demand in emerging markets, and proposed acquiring CEMEX's ready mix concrete and aggregates operations in Southeast France while upgrading full year sales guidance but keeping EBITDA targets unchanged.
- The combination of stronger trading momentum and a planned expansion of the French materials footprint signals that Vicat is pursuing growth projects while still framing performance through the lens of profit discipline.
- We will now look at how Vicat's investment narrative could be influenced by its upgraded 2026 sales outlook.
Scan for other building materials stocks that show similar sales momentum and disciplined profit targets using our hand picked 225 high quality undervalued stocks as a starting point.
Vicat Investment Narrative Recap
For Vicat, the core belief is that a cement and concrete group with a heavy emerging market mix can keep compounding earnings through efficiency projects and disciplined capital use. The Q3 2026 sales upgrade fits that story, because it points to healthier activity in the United States and faster growth regions, while management still talks in terms of profit focus.
In the short term, the key swing factor is whether stronger demand outside France can offset soft domestic cement volumes and higher energy and transport costs. That risk has not gone away. The unchanged EBITDA guidance underlines that the near term question is margin resilience rather than how fast reported sales grow.
The proposed acquisition of CEMEX's ready mix concrete and aggregates operations in Southeast France is the announcement that links most directly to this update. It pushes Vicat further into downstream materials in a market where cement volumes remain weak and where management is already trying to protect profitability through pricing and cost work.
For you as a shareholder, the interest lies in how cleanly this deal is executed and integrated. Extra French exposure could add scale and logistical benefits, but it also increases sensitivity to any prolonged downturn in that market and to energy and transport inflation, which are already flagged by the group as important risks.
Vicat's current analyst scenario points to revenues of €4.4 billion and earnings of €324.1 million by 2029, based on a forecast revenue growth rate of 3.3% per year and an increase in earnings from €289.7 million today to €324.1 million, which implies an earnings increase of about €34.4 million by that same year.
Uncover why Vicat's fair value indicates a 27% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some pessimistic analysts focus on one aspect of the Vicat story that you might overlook: slower French project ramp-up. Their pre-news models only pencilled in revenue of about €4.3b and earnings near €316.2m by 2029. That view is less enthusiastic about major tunnels and infrastructure projects, which illustrates how far opinions can differ and why this latest update could shift expectations in very different ways.
Explore 3 other Vicat fair value estimates, including one that suggests it could be worth just €70.00.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Vicat research is our analysis highlighting 6 key rewards that could impact your investment decision.
- See our latest analysis for Vicat. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vicat's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vicat?
If Vicat is on your radar, it can help to line it up against other companies with different strengths, income profiles, and risk levels. That broader context gives you a clearer sense of where the opportunity really sits in your portfolio.
- For investors hunting for income resilience, scan companies that aim to back sizeable payouts with sturdy finances through our 232 dividend fortresses.
- If capital preservation matters most to you, focus on businesses that our models score as more resilient using the 212 resilient stocks with low risk scores.
- To widen the opportunity set beyond well known large caps, look at financially sound smaller companies that screens flag as overlooked using the 588 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com