


EN
The Bet Orange Polska Holders Made Before An 87% Jump
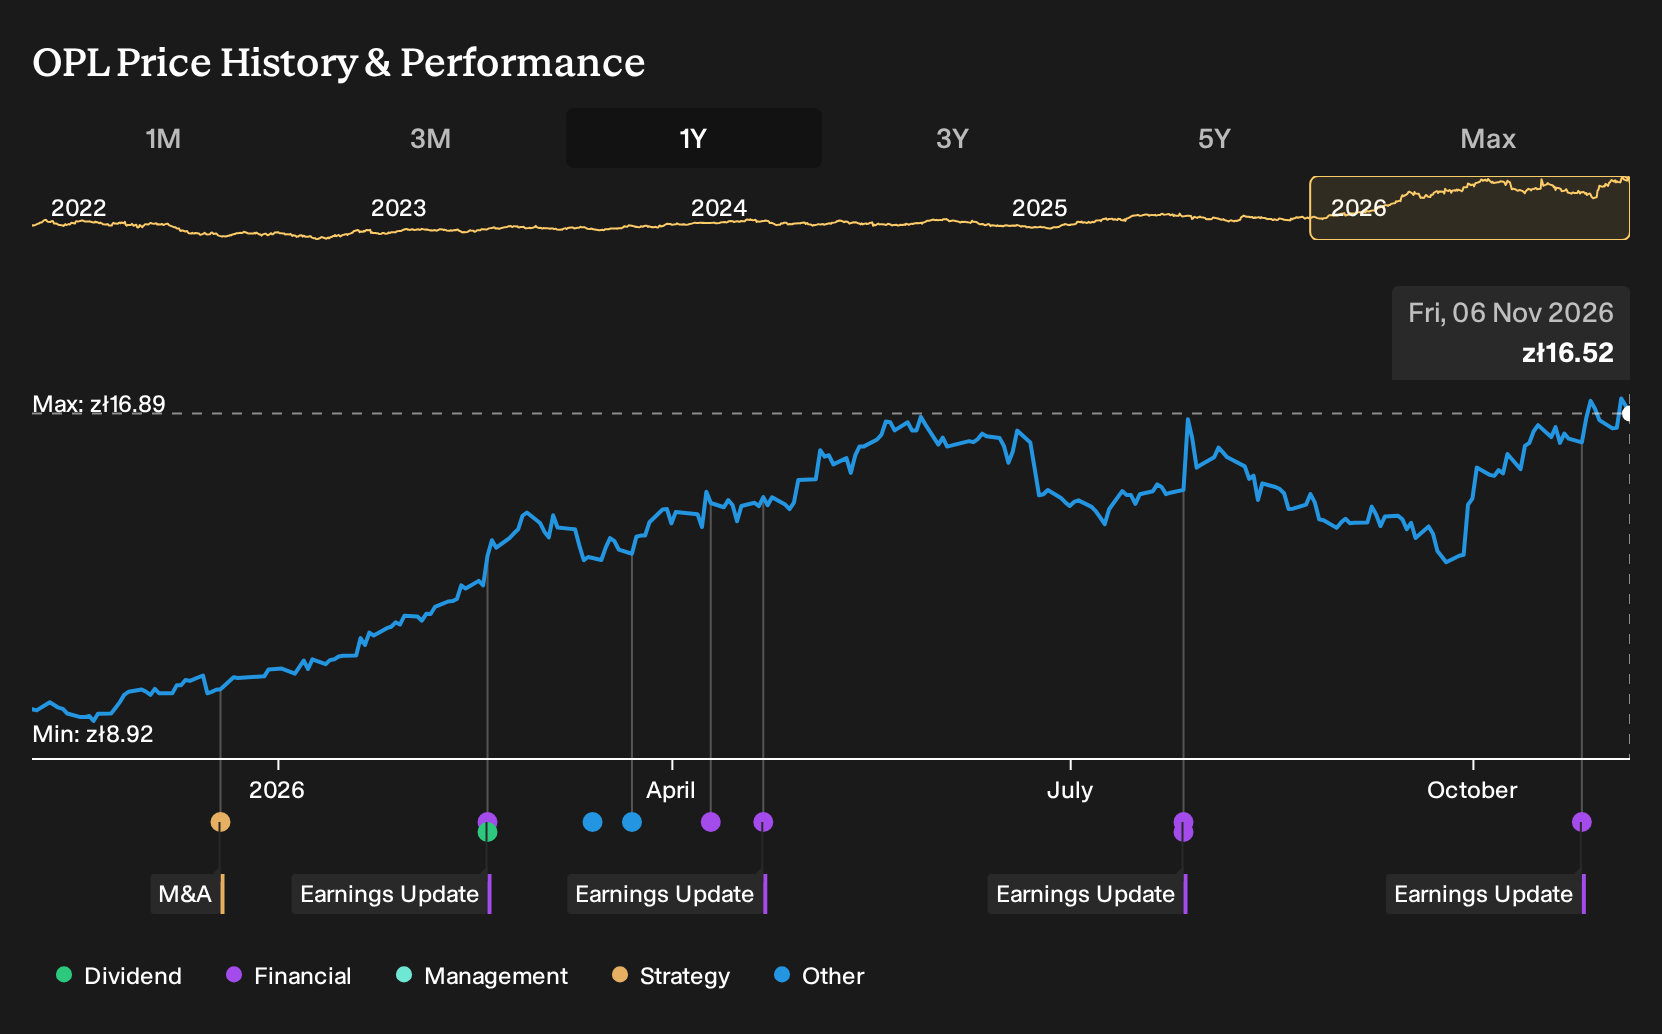
If Orange Polska had been on your watchlist instead of in your portfolio, the scale of the missed gain might feel uncomfortable. For Orange Polska shareholders, the return over the past year was 87.2%, including dividends. That outcome invites a harder question. Back on 6 November 2025, with analysts split between fiber driven acceleration and demographic drag, what could have helped you judge whether aggressive digitalization and network investment would outweigh legacy revenue pressure?
The easy part of this move is behind Orange Polska. Zero in on 225 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On Orange Polska
The shares cost PLN9.21 at the start of the period, and investors in Orange Polska were effectively choosing between two well developed stories.
The bullish view saw a Fair Value of PLN10.8, a price implied by forecasts, built on accelerating fiber rollout, 5G expansion, and higher margin ICT and cybersecurity contracts supporting earnings and cash generation.
The cautious camp worked off a Fair Value of PLN6.1, based on concerns that Poland's aging, shrinking population and pressure on legacy voice and SMS revenue could cap subscriber growth and strain free cash flow.
What The Results Changed For The Orange Polska Debate
The cleanest new fact for Orange Polska investors came from the Q3 2026 report. Revenue reached PLN3,592m versus PLN3,329m a year earlier, net income moved from PLN228m to PLN328m, and net margin rose from 6.8% to 9.1%. That pattern supported the optimistic case that higher margin digital and network services could lift profitability.
The lesson is simple. When a thesis turns on digitalization paying for heavy capital spending, track net margin alongside sales. For any telecom stock, check whether better fiber and 5G usage is actually showing up in a steadily higher margin over several reporting periods.
What Orange Polska's Price Already Assumes After An 87% Run
Orange Polska now trades at PLN16.52, with this Narrative’s Fair Value sitting below that quote. The argument is not that the business is broken, but that expectations for recurring EBITDAaL and organic cash flow already build in a lot of continued execution.
The key question for anyone paying today’s price is what must keep working. A buyer has to judge whether postpaid ARPU gains, convergence, large contracts and flat indirect costs can all stay on track without material stumbles.
"The main thing that has to go right is that Orange Polska needs to keep turning strong core telecom, IT&IS and wholesale performance, together with flat indirect costs, into recurring EBITDAaL and organic cash flow growth. The current numbers, including guidance for low to mid single digit revenue growth, EBITDAaL growth above 6% and organic cash flow of at least PLN 1.2b in 2026, imply a share price that already reflects continued execution without major setbacks."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Find Your Own Contrarian Opportunity
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 20% below our estimate - uses advanced-node manufacturing capacity that major chip designers increasingly rely on for AI workloads.
- Company 2 - 42% below our estimate - converts shorter brownfield tieback cycles into higher margin subsea orders and longer services contracts.
- Company 3 - 29% below our estimate - expands AI and cloud infrastructure so subscription and usage-based services run on the same platform.
That is three of the list. See every one of the 193 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com