


EN
Is Withheld Guidance Altering The Investment Case For Fair Isaac Stock?
- Fair Isaac reported past fiscal 2026 results with quarterly revenue of US$657.05 million and net income of US$174.96 million, alongside full year revenue of US$2.53b and net income of US$834.97 million.
- Beyond the headline numbers, Fair Isaac is reshaping its mortgage and software franchises through bespoke pricing, new FICO Platform offerings and expanded adoption of scores such as FICO Score 10T across major lenders.
- We will now see how Fair Isaac's record fiscal 2026 earnings, along with withheld guidance, could reshape the longer term investment narrative.
Scan beyond Fair Isaac and see how other credit and software driven lenders are priced by checking the hand picked 19 high quality undiscovered gems that share similar fundamentals.
Fair Isaac Investment Narrative Recap
To own Fair Isaac, you need to believe the credit scoring and platform franchises stay relevant as regulation and competition reshape mortgage economics. The short term swing factor is how bespoke mortgage pricing and withheld fiscal 2027 guidance affect confidence in Scores and software revenue durability. Record fiscal 2026 revenue of US$2.53b and net income of US$834.97 million give management room to keep investing in FICO Platform and AI tools.
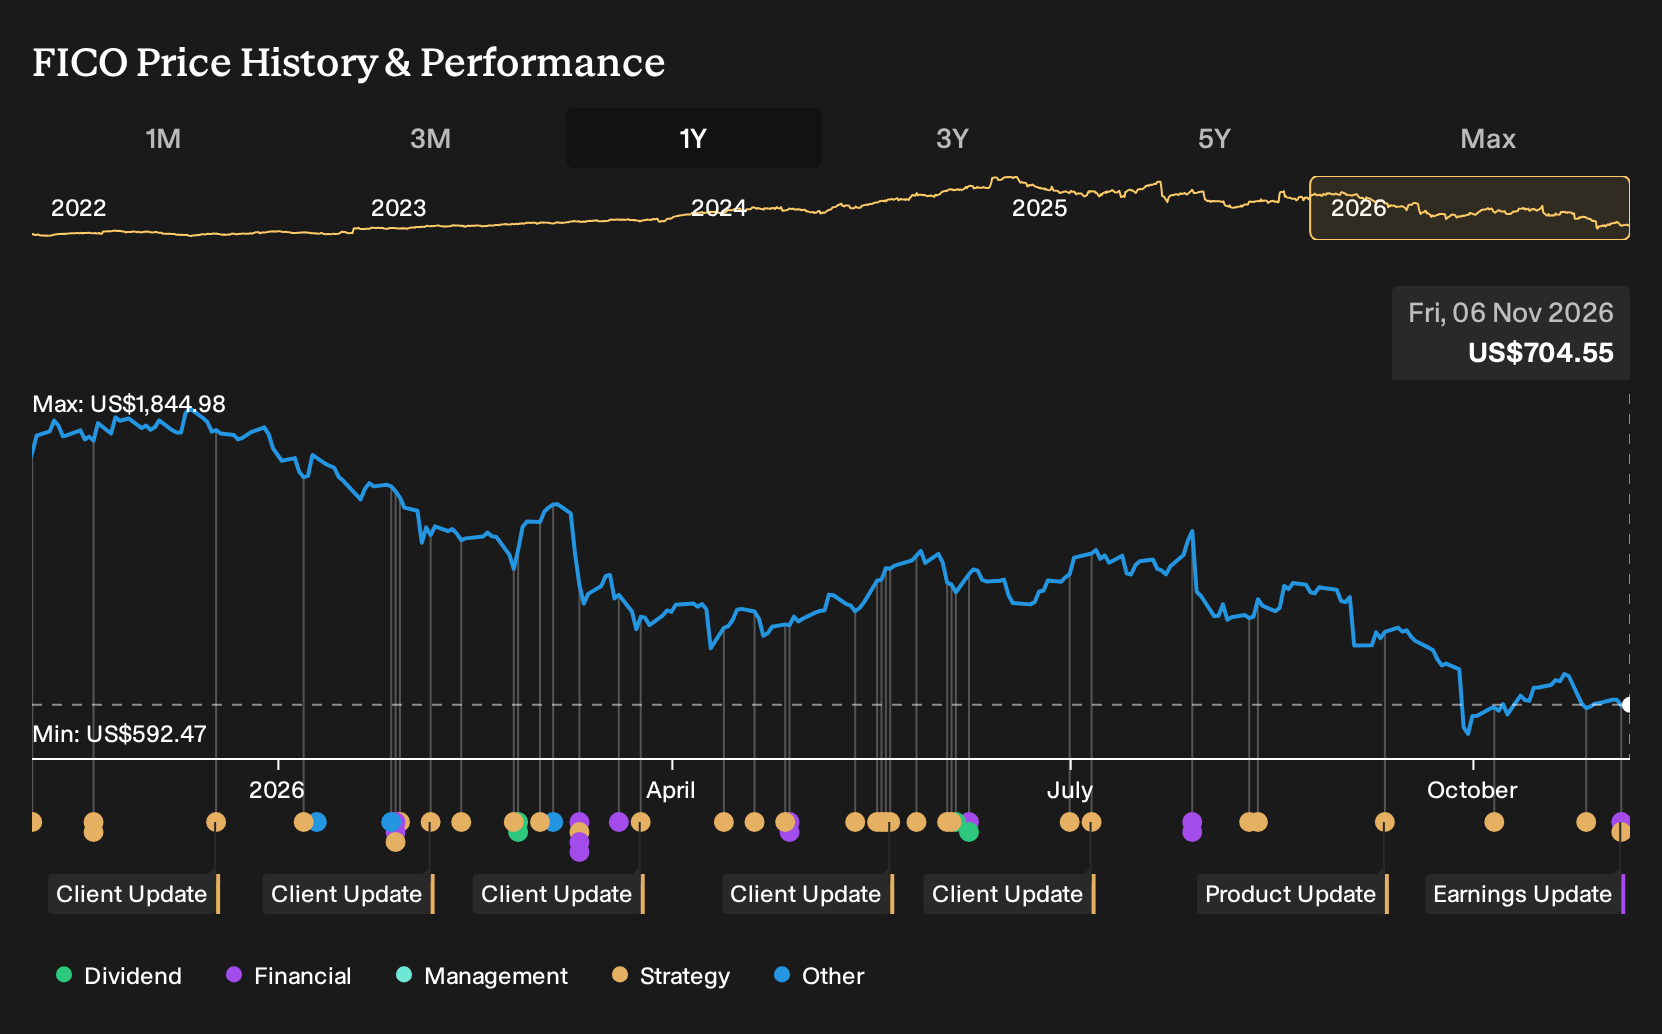
The flip side is clear. Mortgage score pricing pressure, plus Fair Isaac’s use of multi billion dollar debt for buybacks, leaves less margin for error if cash flows soften. With shares down about 60% over 1 year and volatile over 3 months, sentiment already reflects those concerns. The latest earnings do not remove these risks but they do show the current operating model still supports high net profit levels.
The FICO Preferred Program update is most relevant to this earnings story. DHI Mortgage, LoanDepot, Paramount Residential Mortgage Group and CMG Financial have signed on, joining lenders like Guild Mortgage and PennyMac. These participants commit to pulling FICO Scores across their mortgage operations, with access to both Classic FICO Score and FICO Score 10T. That keeps Fair Isaac embedded in large origination flows while mortgage pricing moves to custom deals.
Operationally, that enrollment supports the key catalyst investors focus on. Broader use of FICO Score 10T and related models can help offset regulatory pressure on classic mortgage scores by reinforcing Fair Isaac’s role in day to day underwriting decisions. The same trend cuts both ways. If lenders meaningfully shift volume to rival scores despite Preferred participation, the main risk around mortgage pricing and volumes becomes more pronounced even with record fiscal 2026 results.
Fair Isaac Consensus Forecasts In Context
Analysts are effectively sketching a higher earnings profile for Fair Isaac over the next few years, but with only moderate changes to the business mix. The consensus view folds in steady use of the FICO Platform, ongoing mortgage score pressure and a more leveraged balance sheet without assuming a sharp break from the current model.
On the top line, the group of covering analysts is building in annual revenue growth of 8.2% over the next three years. That pace reflects an expectation that software subscriptions and decisioning tools keep doing more of the heavy lifting as traditional mortgage scoring faces tougher competition and new pricing structures.
Earnings today are pegged at US$815.0 million, and the same analyst set projects profit of US$1.0b by 2029. That implies an earnings increase of about US$185.0 million from current levels, even as margins are expected to edge lower from 34.1% now to 33.9% in three years as investment and competitive pressure feed into the income statement.
Fair Isaac's narrative projects US$3.0b revenue and US$1.0b earnings by 2029. This requires 8.2% yearly revenue growth and an earnings increase of about US$185.0 million from current earnings of US$815.0 million.
The analyst framework also assumes a shrinking share count, with forecast share repurchases reducing shares outstanding by 7% per year across the next three years. For readers, that means a larger portion of future profit per remaining share if those buybacks occur at or below the analysts’ implied value, and if earnings arrive close to the consensus path.
To tie these assumptions into a valuation, the models use a discount rate of 9.5% to 9.53% and a 2029 P/E multiple of 20.8x on the US$1.0b earnings estimate. That prospective multiple sits below the cited 31.4x P/E for the broader US software peer group in the report, which suggests analysts are baking in a discount for Fair Isaac relative to sector averages despite the record fiscal 2026 results.
Uncover why Fair Isaac's fair value indicates a 33% potential upside to its current price, which could narrow quickly if sentiment around Fair Isaac shifts.
Exploring Other Perspectives
One alternate view puts the FICO Platform upsell story front and center. Bullish analysts, before this news, were sketching US$3.5b revenue and US$1.2b earnings by 2029, compared with the baseline US$3.0b and US$1.0b. That is a much more optimistic take. Your job is to decide whether these pre news assumptions still fit after record 2026 results and new Preferred Program wins.
Explore 6 other Fair Isaac fair value estimates, including one that suggests as much as 89% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Fair Isaac research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Fair Isaac. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fair Isaac's overall financial health at a glance.
Looking for more investment ideas beyond Fair Isaac?
Fair Isaac might be at the center of your watchlist right now, but your next strong idea could come from an entirely different corner of the market. Use the Simply Wall St Screener to compare quality, balance sheet strength and return profiles in a consistent way rather than chasing headlines stock by stock.
- If you want to focus on quality at a sensible price, start by scanning a curated 39 high quality undervalued stocks that combines fundamentals with appealing valuations.
- If capital preservation matters just as much as upside potential, filter for a 29 resilient stocks with low risk scores and see which businesses have more resilient profiles.
- If balance sheet strength is a priority, narrow your search to a list of solid balance sheet and fundamentals (24 results) that already clears a fundamental quality bar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com