


EN
CECO Environmental (CECO) Heads Into Q3 Earnings As Backlog Strength Keeps Fair Value In Focus
CECO Environmental (CECO) heads into its Q3 2026 earnings release on 9 November with attention on its order backlog, record bookings, and demand tied to power generation, natural gas infrastructure, and semiconductor projects.
Over the past month, CECO Environmental’s share price has dropped 47.1%, including a 17.1% fall in the last session, as investors reset expectations ahead of Q3 results. This comes despite a much stronger picture over the long haul, with a 5-year total shareholder return above 4x the starting point.
Scan beyond CECO Environmental and line up other industrial plays under pressure with record backlogs by reviewing the 39 high quality undervalued stocks.
The selloff leaves CECO Environmental trading far below analyst and intrinsic value estimates, while still backed by a sizable backlog. Does that reset turn the recent slide into a more attractive entry point or a value trap?
Most Popular Narrative: 66% Undervalued
Against a last close of $37.66, the most followed narrative pegs CECO Environmental’s fair value at about $111.86, framing the recent slide as a sharp gap between price and estimated worth.
Backlog that has grown for 12 consecutive quarters to more than $1.8 billion and a sales pipeline that has expanded from about $1.5 billion in 2021 to over $8.5 billion by Q2 2026 give CECO Environmental a wide set of identified opportunities that can feed future revenue and provide potential operating leverage.
See why 12 investors see CECO Environmental as 66% undervalued.
Result: Fair Value of $111.86 (UNDERVALUED)
Still, the CECO Environmental story can break if large power and gas projects slow or if higher-than-expected leverage keeps interest costs biting into earnings.
Find out about the key risks to this CECO Environmental narrative.
Another View On CECO Environmental’s Valuation
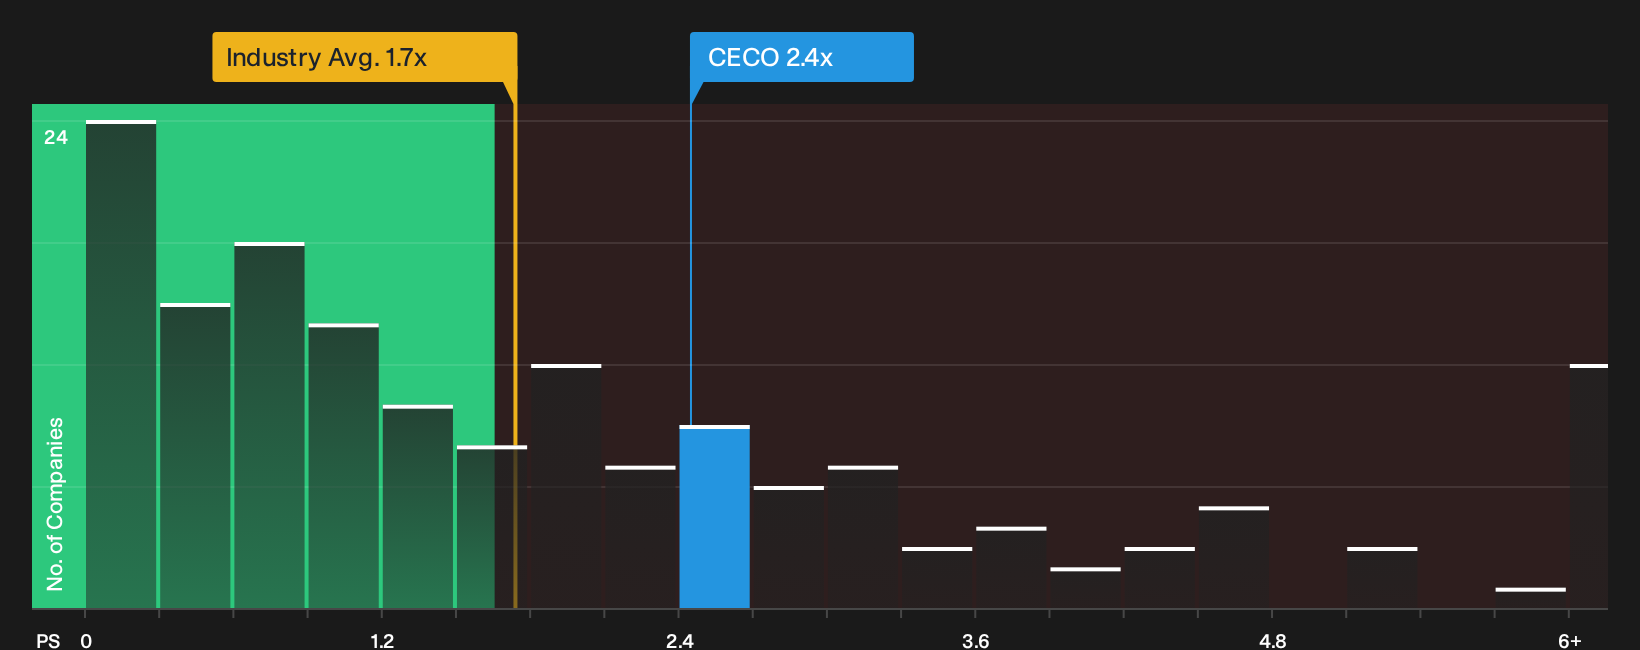
On the flip side of the 66% implied discount to fair value, CECO Environmental screens as expensive on a simple P/S check. Its 2.4x P/S is higher than the 1.7x US Machinery industry average, even though it sits below peers at 2.7x and a fair ratio of 4.3x. That mix of premium to the sector, discount to peers, and wide gap to the fair ratio leaves a basic question. Is this a mispriced opportunity or just extra valuation risk in a volatile stock?
See what the numbers say about this price by digging into our valuation breakdown with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals often create the best questions, and CECO Environmental is no exception, so move quickly and compare the bullish and cautious arguments with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CECO Environmental?
If CECO Environmental has your attention but you want a broader watchlist, use focused screens to spot other opportunities before the crowd catches on.
- Target potential mispricings by scanning a curated pool of quality companies trading below estimated worth through the 39 high quality undervalued stocks.
- Build a portfolio with income in mind by reviewing a 8 dividend fortresses that may suit investors who prioritise steady cash payouts.
- Guard against downside shocks by zeroing in on a 29 resilient stocks with low risk scores that emphasises resilient balance sheets and more stable risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com