


EN
How Earnings Beat Will Impact Hartford Investors
- Hartford Insurance Group reported third quarter 2026 revenue of US$7,220 million and net income of US$1,323 million, with both basic and diluted earnings per share higher than a year earlier, and released nine month figures showing higher revenue and profit compared with the prior period.
- The insurer paired these earnings with a 12% lift in its quarterly dividend to US$0.67 per share and a completed Equitable Employee Benefits acquisition, which together highlight management’s focus on returning cash to investors while expanding Hartford Insurance Group’s benefits platform and distribution reach.
- The company’s stronger earnings and higher dividend may influence how some investors view Hartford Insurance Group within a broader investment narrative.
Scan how Hartford Insurance Group's stronger earnings and higher dividend compare with other insurers by reviewing a hand-picked 29 resilient stocks with low risk scores that prioritize resilient balance sheets and steadier risk profiles.
Hartford Insurance Group Investment Narrative Recap
To own Hartford Insurance Group, you need to be comfortable with a business that leans heavily on underwriting discipline, technology in small commercial and a long record of growing earnings over time rather than rapid top line expansion. The latest quarter showed higher revenue and net income, which supports that story but does not fully address the long term risk that analysts see around declining forecast earnings.
The near term swing factor still sits in underwriting results and catastrophe activity, because a run of severe events could compress those improved net margins quickly. Competitive and regulatory pressure in Personal Insurance also remains a real watchpoint, since weaker written premium there could offset progress in commercial lines if pricing or customer retention come under more strain.
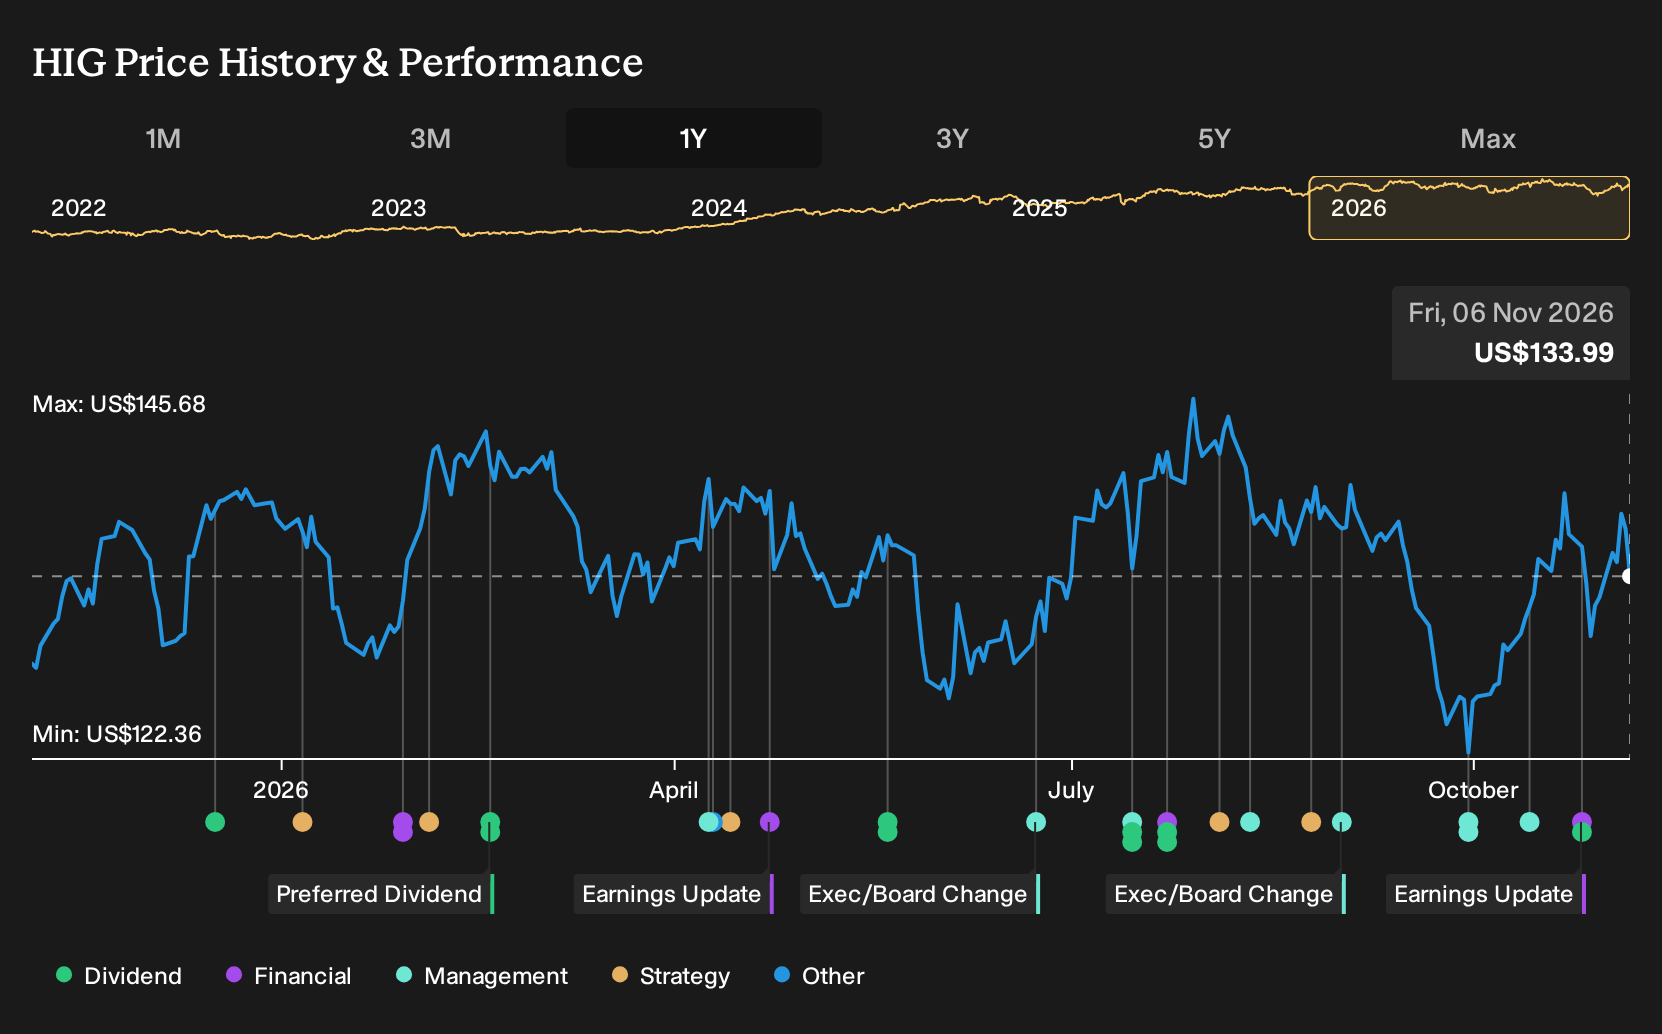
The 12% increase in Hartford Insurance Group’s quarterly dividend to US$0.67 per share is the clearest new signal for investors in this update. It extends a 14 year dividend growth streak and confirms that management is confident enough in cash generation to lift regular payouts while still funding technology, underwriting and integration spending.
For catalysts, that higher dividend intersects with the Equitable Employee Benefits acquisition. This transaction is expected initially to dilute 2027 core earnings before any later accretion. Investors now need to weigh a richer cash return profile against the execution risk of absorbing roughly US$500 million of premiums and a new digital platform in a segment already targeting mid single digit to low double digit margins.
Hartford Insurance Group's current analyst narrative points to forecast revenue of US$32.1b and consensus earnings of US$3.6b by 2029, based on an assumed 2.8% yearly revenue growth rate and a projected decline in earnings of US$0.7b from US$4.3b today.
Uncover how Hartford Insurance Group's fair value indicates a 9% potential upside to its current price before that gap closes.
Exploring Other Perspectives
Five fair value views from the Simply Wall St Community span roughly US$143 to over US$302 for Hartford Insurance Group, which is a wide gap for the same stock. Those private investors clearly do not agree. When you also consider catastrophe risk, pressure in Personal Insurance, and the Equitable integration, there are plenty of reasons to compare multiple viewpoints before deciding how Hartford fits in your portfolio.
Explore 4 other Hartford Insurance Group fair value estimates, including one that suggests it could be worth just $143.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hartford Insurance Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hartford Insurance Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hartford Insurance Group's overall financial health at a glance.
Looking for more Hartford Insurance Group style ideas?
If Hartford Insurance Group has sharpened your focus on quality and risk, use that same lens across the wider market. The Simply Wall St Screener can help you quickly sort through hundreds of other stocks so you can spend more time comparing businesses and less time trawling tickers.
- For investors who want income with fewer surprises, start with a shortlist of resilient payers through 8 dividend fortresses to balance yield with stability.
- If value is your priority, widen your watchlist by scanning a focused 39 high quality undervalued stocks that highlights companies combining stronger fundamentals with more modest pricing.
- For readers who prize financial resilience above all else, filter for balance sheet strength first using a curated list of solid balance sheet and fundamentals (24 results) that screens for sturdier funding and liquidity profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com