


EN
What CES Energy Solutions (TSX:CEU)'s Bigger Credit Facility Means For Shareholders
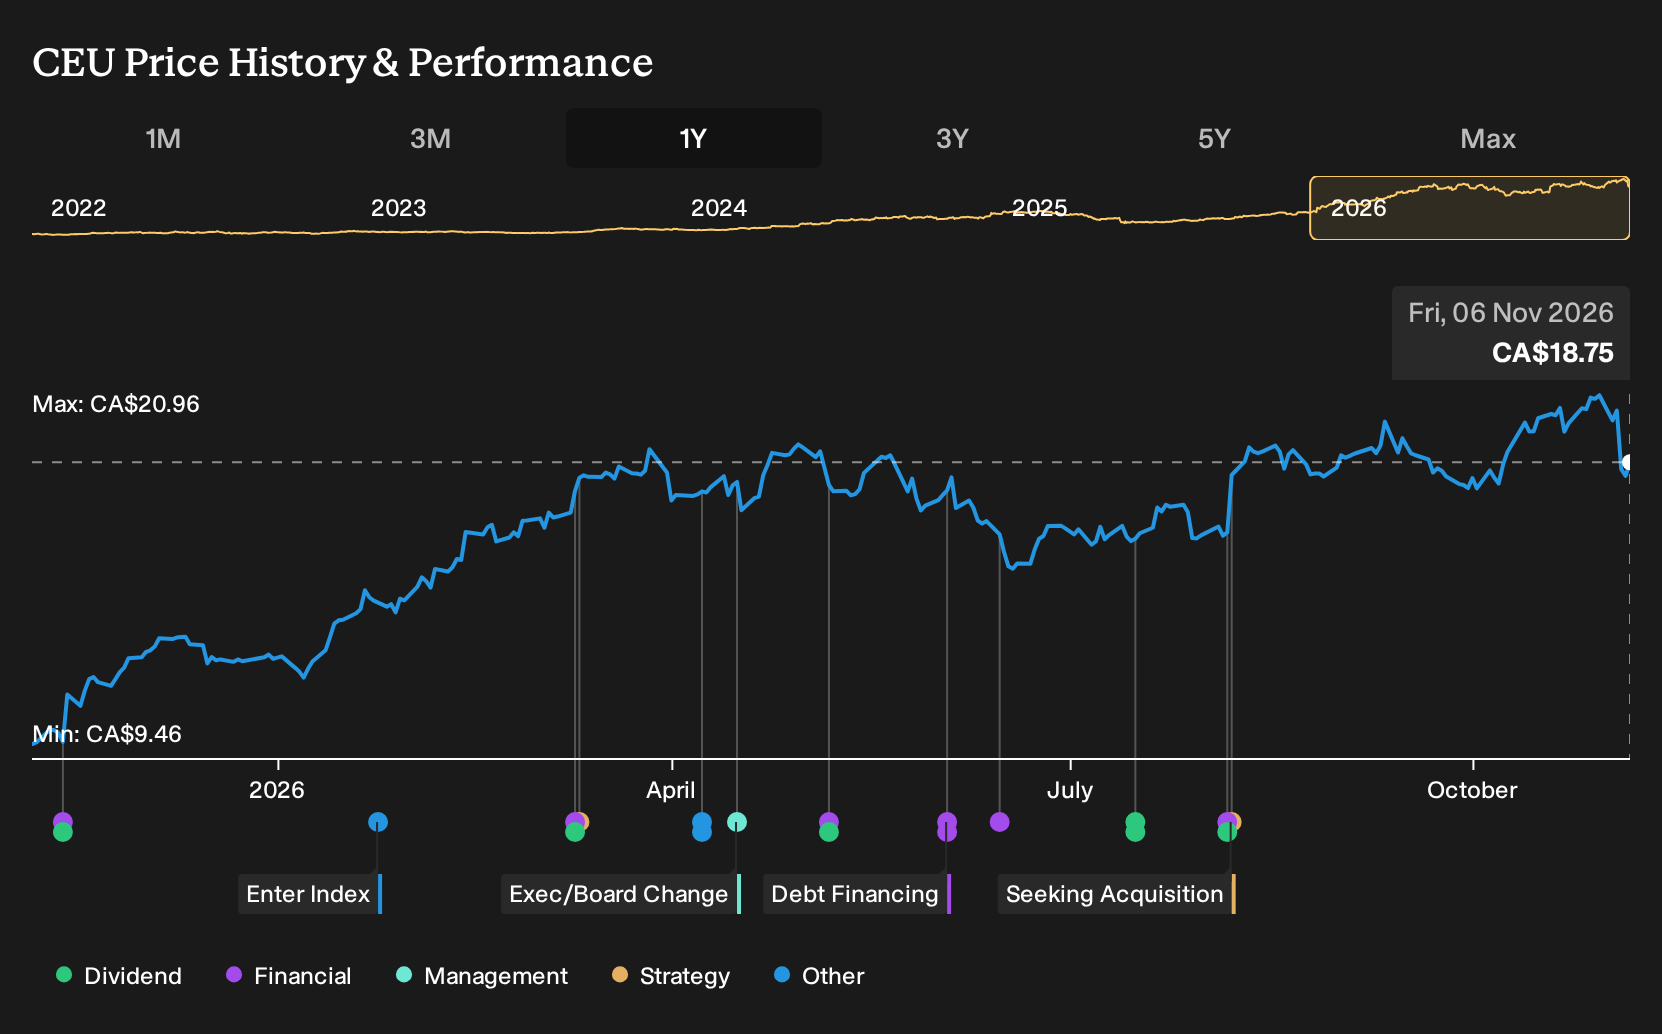
- CES Energy Solutions secured an amended and restated credit agreement that lifts its total credit facility to about C$750 million, with maturity extended to November 6, 2031, and terms secured against most of its assets.
- The larger facility, combined with record 2025 revenue and continued top line expansion into 2026 despite mixed net income, highlights how CES Energy Solutions is funding a consumables focused model tied to drilling and production activity.
- We will now look at how CES Energy Solutions' larger long dated credit facility could influence the investment narrative around its growth plans.
Compare CES Energy Solutions' funding driven growth story with other oilfield and energy service plays by scanning our hand picked list of solid balance sheet and fundamentals (5 results) for potential alternatives.
CES Energy Solutions Investment Narrative Recap
For CES Energy Solutions, the basic bet is that demand for its consumable chemicals and fluids tied to drilling and production remains healthy enough to keep high profit per employee and strong cash generation intact. The enlarged C$750 million credit facility gives management more room to fund bids, capex and working capital as activity moves, without reshaping that core thesis.
In the short term, the key swing factor is still producer spending on drilling and complex well work, which drives volumes in both drilling fluids and production chemicals. The biggest near term risk is margin pressure from competitive tenders and any sustained softness in activity, especially given the higher reliance on external borrowing.
The amended and restated credit agreement is the announcement that matters most for this story right now. CES Energy Solutions now has a larger, longer dated facility maturing in 2031, secured against most assets. That structure supports a consumables heavy model where big customers expect reliable supply and technical support through cycles.
Regarding potential catalysts, the extra liquidity can support pursuit of large production chemical contracts, further supply chain localization or acquisitions similar to past deals such as Fossil Fluids. The flip side is that higher committed borrowing capacity sits next to an already high debt flag, so execution on new contracts and cost control will be important if industry pricing stays tight.
CES Energy Solutions' current analyst narrative points to revenue of CA$3.7b and earnings of CA$351.0m by 2029. This implies 11.6% yearly revenue growth and an earnings increase of about CA$153.4m from CA$197.6m today.
Discover why CES Energy Solutions' fair value indicates a 22% potential upside to its current price that could close more quickly than many investors expect.
Exploring Other Perspectives
Some of the most optimistic analysts focus on CES Energy Solutions’ potential to keep earnings near the bullish CA$403.2 million by 2029 through higher margin production chemicals, rather than just volume growth. Those projections were set before this C$750 million credit facility, so you may want to compare both narratives and decide which feels more realistic to you.
Explore 2 other CES Energy Solutions fair value estimates, including one that suggests up to 138% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CES Energy Solutions research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CES Energy Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CES Energy Solutions' overall financial health at a glance.
Looking for more CES Energy Solutions sized ideas?
If CES Energy Solutions has sharpened your focus on balance sheets and cash generation, it can help to line it up against a wider field of candidates. The Simply Wall St Screener lets you filter for very specific traits, so you can build a watchlist that actually reflects how you like to invest rather than just chasing headlines.
- Prefer to keep downside in check and sleep a little easier at night, even when markets get noisy, by scanning a basket of companies with steadier risk profiles using the 9 resilient stocks with low risk scores.
- If reliable income is high on your list, compare CES Energy Solutions with businesses offering higher yield potential and consistent payouts by reviewing the 3 dividend fortresses.
- For those hunting for mispriced opportunities with solid fundamentals, widen your search beyond CES Energy Solutions by sorting through our hand picked 7 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com