


EN
Millicom Stock Revenue Beat Raises Margin Questions After Q3 Earnings
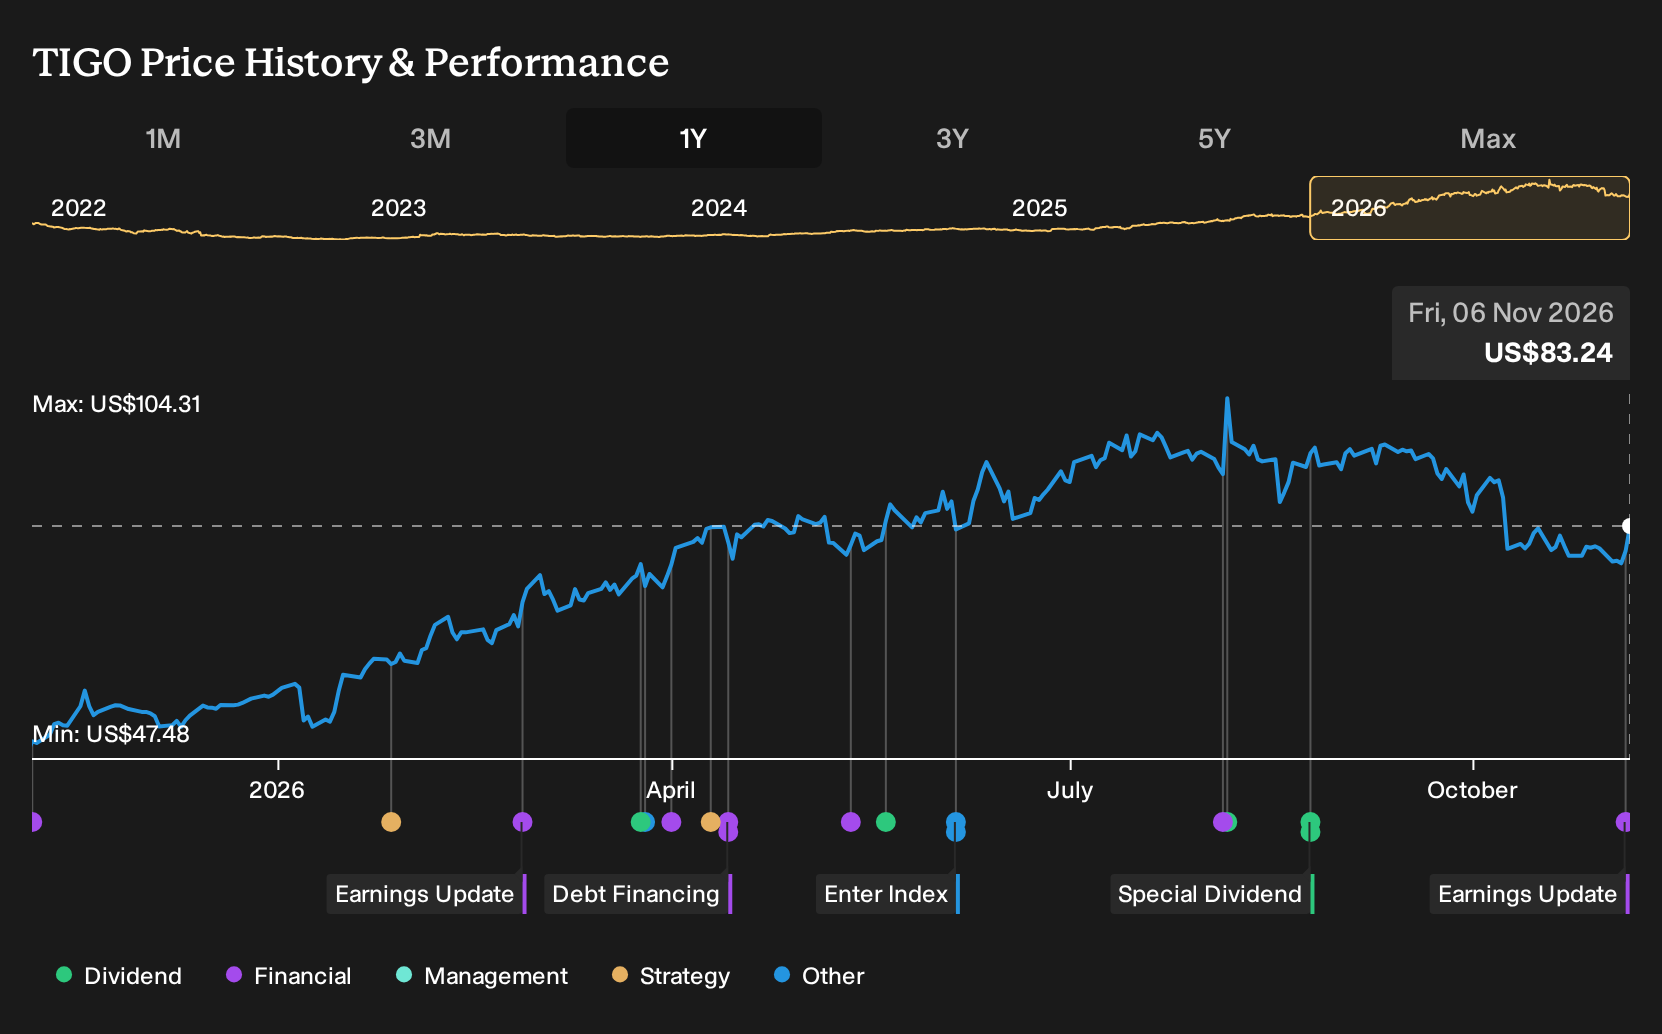
- Millicom International Cellular reported Q3 2026 sales of US$2,276 million and net income of US$98 million, with earnings per share of US$0.58 from continuing operations, while reaffirming full year equity free cash flow guidance of around US$1.1 billion and a leverage goal below 2.5x.
- Management highlighted progress on its Double E and more for more plans, including significant postpaid migration from the prepaid base and stronger convergence. This helped deliver US$2.28 billion in quarterly revenue that exceeded some analyst expectations, even as earnings per share fell short of consensus forecasts.
- The next area of focus will be how Millicom’s revenue outperformance, alongside an earnings miss, may reshape the broader investment narrative.
Scan how Millicom International Cellular’s earnings story compares with other telecom and infrastructure operators by reviewing a curated list of solid balance sheet and fundamentals (24 results)
Millicom International Cellular Investment Narrative Recap
To own Millicom International Cellular, you need to buy into a Latin American telecom story built on postpaid upgrades, convergence and disciplined cash generation. The latest quarter still leans into that idea. Service revenue was solid, equity free cash flow guidance of about US$1.1b was reaffirmed and the leverage goal below 2.5x stayed intact.
The short term swing factor is whether earnings pressure eases while debt keeps trending lower. Q3 net income and EPS were weaker than a year ago, so any delay in margin recovery or higher interest costs remains the biggest operational risk. On this front, the earnings miss looks important, not noise.
The most relevant update alongside the earnings print is management’s confirmation that Millicom International Cellular is on track for roughly US$1.1b in equity free cash flow in 2026 while targeting leverage below 2.5x. For a business carrying about US$8.1b of net debt, that cash profile sits at the center of the thesis.
That same announcement underlined execution on the Double E and more for more plans, with 73% of postpaid sales coming from the prepaid base and strong take up of convergent offers. For you, the key question is whether this operational mix shift offsets margin pressure and refinancing risk quickly enough to keep that cash flow target credible.
Millicom International Cellular's current earnings of $669.0 million are projected by analysts to reach $1.1 billion by 2029. This represents an earnings increase of about $431 million, and this outlook is paired with expectations for revenue to reach $9.6 billion by that same year, implying revenue growth of 9.8% per year over the period.
Uncover how Millicom International Cellular's fair value indicates a 16% potential increase from its current price before the market closes that gap.
Exploring Other Perspectives
One alternate view on Millicom International Cellular focuses heavily on margin risk. The most cautious analysts were pencilling in profit margins sliding to 7.7% and earnings of about US$738.1 million by 2029 on roughly US$9.6b of revenue. That is a much harsher script than consensus, and the fresh Q3 earnings miss may push some forecasts closer to that pessimistic camp. Use this gap in expectations as a reminder that smart people disagree, and explore both the upbeat and cautious scenarios before deciding how this telecom story fits your portfolio.
Explore 3 other Millicom International Cellular fair value estimates, including one that suggests it could be worth just $96.39.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Millicom International Cellular research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Millicom International Cellular. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Millicom International Cellular's overall financial health at a glance.
Looking For More Investment Ideas Beyond Millicom International Cellular?
If Millicom International Cellular has sharpened your focus on cash generation, balance sheets and risk, use that same framework to scan a broader watchlist. The Simply Wall St Screener lets you sift through the market quickly so you can concentrate on a shortlist that actually fits your investing style rather than wading through every stock one by one.
- For investors who care most about financial resilience and low refinancing stress, start with a list of solid balance sheet and fundamentals (24 results) that keeps the focus on durable balance sheets and consistent fundamentals.
- If your goal is to find potential value opportunities with quality characteristics, use a 39 high quality undervalued stocks that blends strong business profiles with prices that may not fully reflect their fundamentals.
- When income and capital preservation matter most, filter for a 8 dividend fortresses that can help you concentrate on companies combining higher yields with an emphasis on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com