


EN
Did Strong Q3 Results Just Shift Genpact (G) Investment Narrative?
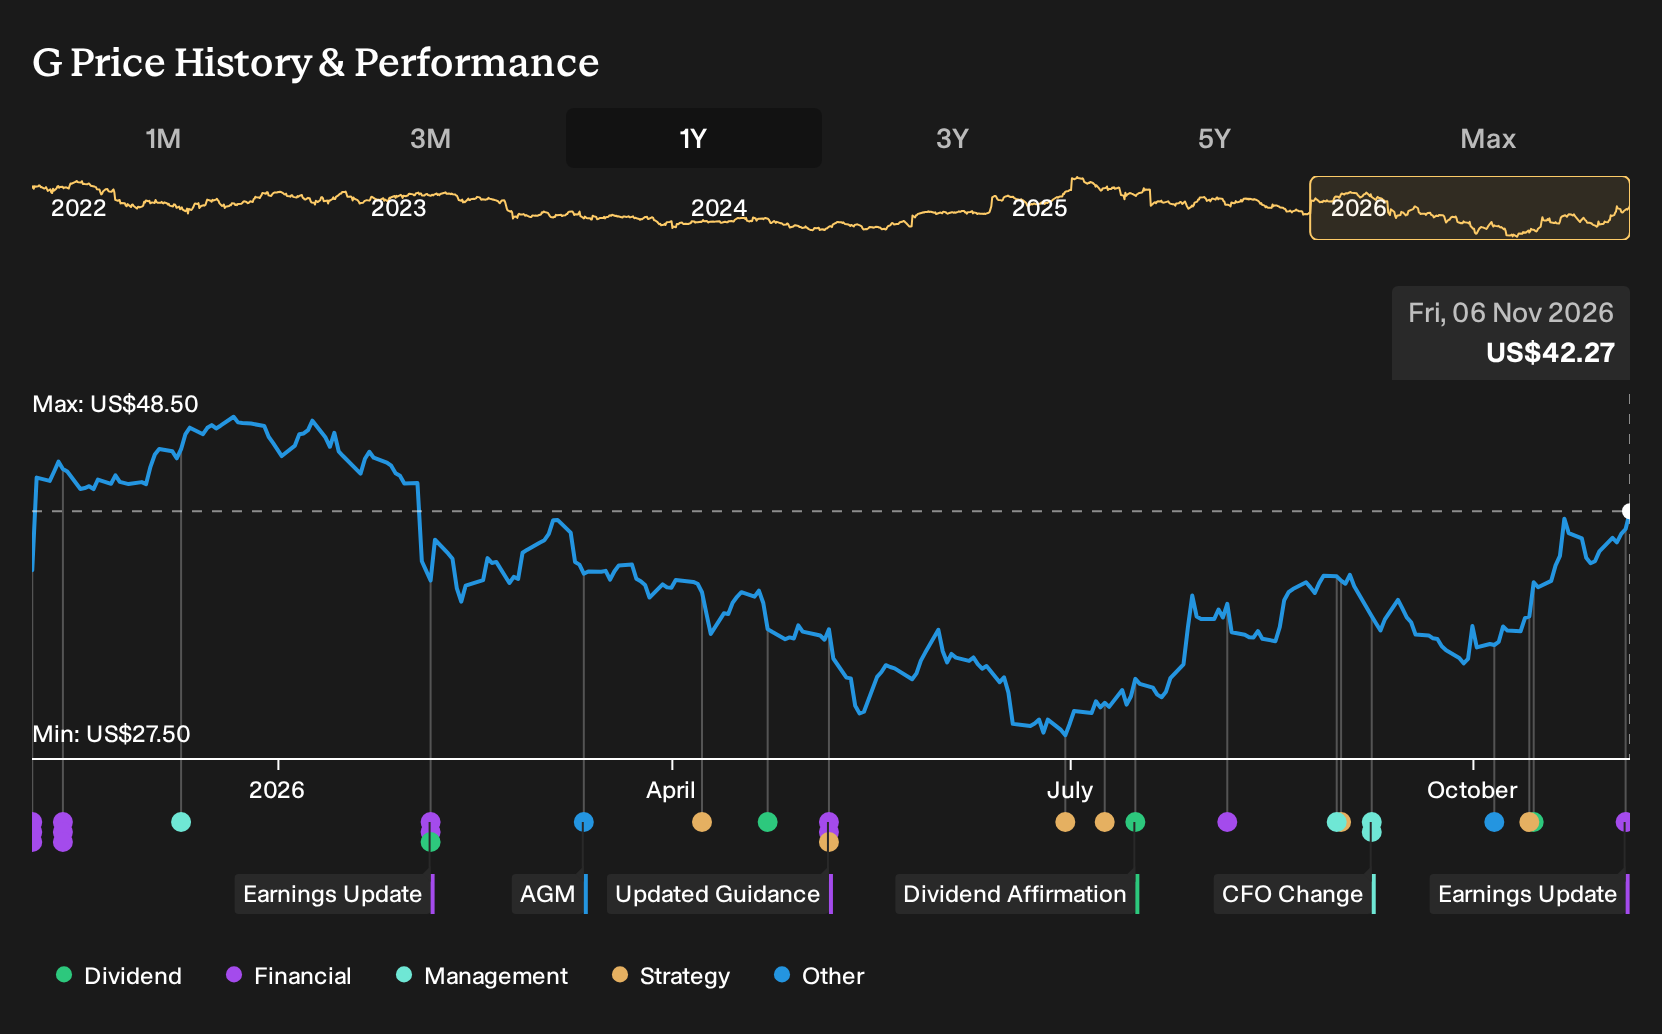
- Genpact reported third quarter 2026 revenue of US$1.39b and net income of US$151.66 million, with basic EPS from continuing operations of US$0.90 and diluted EPS of US$0.89.
- Advanced Technology Solutions and agentic offerings played a central role in this update, supporting gross margin expansion along with a higher full year margin and adjusted EPS outlook.
- We will now look at how Genpact's raised margin and EPS guidance could reshape its investment narrative for long term holders.
Genpact Investment Narrative Recap
To own Genpact, you need to believe its pivot to AI led Advanced Technology Solutions and Agentic Operations can more than offset the drag from exiting lower value content and contact center work. Q3 revenue of US$1.39b and net income of US$151.66 million keep that thesis intact, with gross margin expansion reinforcing the mix shift story.
In the near term, the key catalyst is whether agentic bookings that are expected to exceed US$1b this year convert into recurring, higher margin revenue at scale. The main risk is execution. If AI led projects ramp more slowly than the contracts being exited, overall revenue and earnings could miss current expectations.
The most relevant update for that thesis is the 7.3% year on year revenue growth in Q3 2026, powered by 30.3% growth in Advanced Technology Solutions. For an investor, this points you directly to where the business is trying to migrate, since ATS carries higher revenue per headcount and has been central to margin gains.
Agentic bookings expected at more than five times the 2025 level, with over half from new clients, give Genpact a clearer operational pipeline to work through. Execution risk does not go away, especially with portfolio exits and past communication issues on large deals, but the current earnings print and raised margin and EPS guidance lean toward progress on the core catalysts.
Genpact's narrative projects US$6.5b revenue and US$754.2 million earnings by 2029. This assumes 7.3% yearly revenue growth and an earnings increase of about US$171.5 million from US$582.7 million today.
Uncover why Genpact's fair value indicates that Genpact is trading roughly in line with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts were already penciling in US$6.8b of revenue and US$821.7 million of earnings by 2029 for Genpact before this Q3 report. That outlook leans heavily on Agentic Operations ramping quickly. You can treat this earnings print as a live test of those upbeat assumptions and compare different viewpoints.
Explore 4 other Genpact fair value estimates, including one that suggests potential upside of as much as 198% from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Genpact research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Genpact. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Genpact's overall financial health at a glance.
Looking For More Ideas Beyond Genpact?
Genpact may fit your thesis today, but portfolio strength usually comes from having a bench of alternatives that match different goals, risk levels, and time frames. The Simply Wall St Screener can help you line up other candidates that share some of the quality traits you are seeking.
- If capital preservation and smoother returns matter most to you, consider stocks from our 29 resilient stocks with low risk scores that keep volatility and balance sheet strain in check.
- For investors who care about resilient finances and staying power through different cycles, filter for companies in the list of solid balance sheet and fundamentals (24 results) to see which businesses pair manageable debt with robust fundamentals.
- If you are hunting for less crowded opportunities where quality has not yet attracted broad attention, scan the 19 high quality undiscovered gems and build a watchlist before the crowd catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com