


EN
Does Earnings Outlook Change The Bull Case For MongoDB Stock?
- MongoDB is preparing to report its third quarter fiscal 2027 results on 1 December 2026, accompanied by a conference call to outline its business outlook and discuss developments in its AI focused database platform.
- Recent commentary highlights how MongoDB’s role in powering AI and cloud data workloads, combined with concerns around growth risks and leadership changes, is shaping expectations for its revenue mix and operating leverage.
- We will look at how MongoDB's investment narrative is affected by earnings expectations and its positioning in AI driven data infrastructure.
Scan beyond MongoDB and line up other AI infrastructure plays by checking the hand picked 52 AI infrastructure stocks that could also be sensitive to the same data center and workload trends.
MongoDB Investment Narrative Recap
To be comfortable owning MongoDB, you need to believe its Atlas cloud platform and AI focused features convert into steady usage from both large enterprises and newer AI native customers. The big near term catalyst is the upcoming Q3 FY27 earnings update and outlook. This should give you a clearer read on Atlas consumption and AI workload traction.
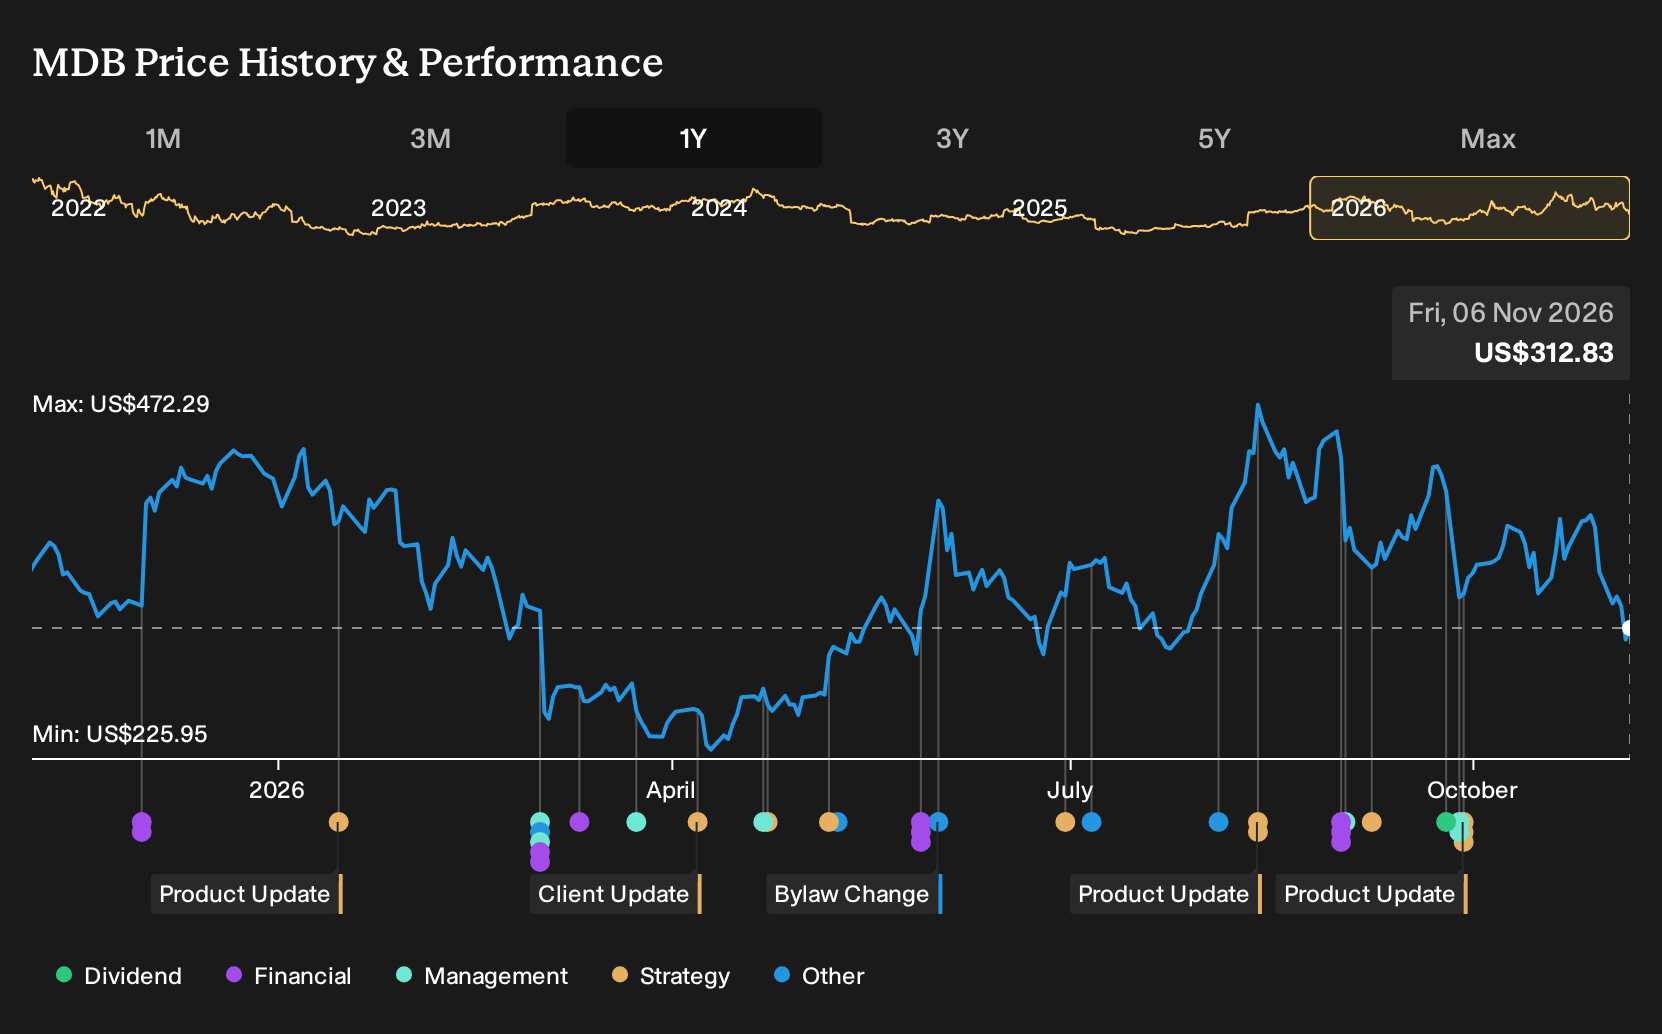
The biggest immediate risk is execution. Recent leadership changes, new AI tools that have not yet delivered the uplift some investors wanted, and strong NoSQL rivals from hyperscalers all put pressure on pricing, margins and product delivery. The recent share price drop ahead of results mostly reflects those existing worries rather than introducing a new, separate concern.
The Q3 FY27 earnings date and conference call on 1 December 2026 is the key announcement to watch. You get fresh data on how MongoDB is converting AI interest into real Atlas and Enterprise Advanced usage, plus how management is thinking about costs, margins and capital allocation off a base of US$2.8b in revenue and US$58.9m in net income.
That update will also matter for risk monitoring. Investors can check whether AI features like vector search and Atlas Agent Engine are gaining commercial traction, whether competition from AWS and Azure is pressuring deal sizes or discounts, and how a relatively new management team is handling go to market execution in what has been a volatile stock with recent insider selling.
What The Current MongoDB Forecasts Assume
MongoDB's current analyst narrative leans heavily on a long runway for its AI oriented data platform to support bigger workloads, but the numbers behind that story are worth unpacking. Consensus expectations build in a 19.6% annual increase in revenue over the next three years and a move in profit margins from 2.1% today to 5.7% by around 2029. That profit shift sits on top of an earnings base of US$58.9m, with analysts, on average, looking for earnings of US$270.0m by the 2029 financial year.
The step up implied here is sizeable. Earnings would need to climb by about US$211.1m from current levels to hit that US$270.0m target. Some forecasters are far more optimistic, pencilling in as much as US$588.4m in earnings, while the most cautious see only US$38.8m. For you as an investor, the spread highlights how differently people model Atlas consumption, AI workload usage and the effect of leadership changes on execution.
Valuation expectations line up with that growth story. The current P/E multiple of 538.1x on existing earnings compresses to 170.6x on the 2029 earnings forecast in the analyst framework, which still sits well above the cited 21.3x for the broader US IT sector. That gap indicates the stock is being treated as a high growth compounder, with investors paying a premium for the possibility that AI tied workloads and higher cloud usage eventually lift both revenue and profitability.
MongoDB's narrative projects US$4.8b revenue and US$270.0m earnings by 2029. This assumes 19.6% yearly revenue growth and an earnings increase of about US$211.1m from the current US$58.9m base.
Uncover why MongoDB's fair value indicates a 45% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternative lens focuses on the risk that leadership turnover and legal inquiries slow MongoDB’s AI execution just as interest peaks around this earnings date. The most bearish analysts were only modeling about US$4.5b of revenue and roughly US$39.0m in 2029 earnings, so their pre news stance was far more cautious than consensus. This upcoming report could easily shift both stories, which is why it helps to compare several viewpoints before you decide how you feel about the stock.
Explore 3 other MongoDB fair value estimates, including one that suggests it could be worth just $385.95!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your MongoDB research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MongoDB. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MongoDB's overall financial health at a glance.
Looking For More Investment Ideas Beyond MongoDB?
Once you have a view on MongoDB, it can help to widen the lens and compare it with other opportunities that fit very different risk and return profiles. The Simply Wall St Screener is built for exactly that, letting you filter the market down to a short list that matches what you care about most.
- If you want potentially higher upside but can tolerate more volatility, scan a curated set of 9 elite penny stocks with strong financials that already carry stronger balance sheets and fundamentals than most tiny companies.
- If your focus is on quality at a reasonable entry point, line up a 39 high quality undervalued stocks that screens for solid cash generation and sturdier finances than the market average.
- If capital preservation matters most to you, narrow the field to a 29 resilient stocks with low risk scores that filters for businesses with more resilient risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com