


EN
What Arrow Electronics Bulls Got Right
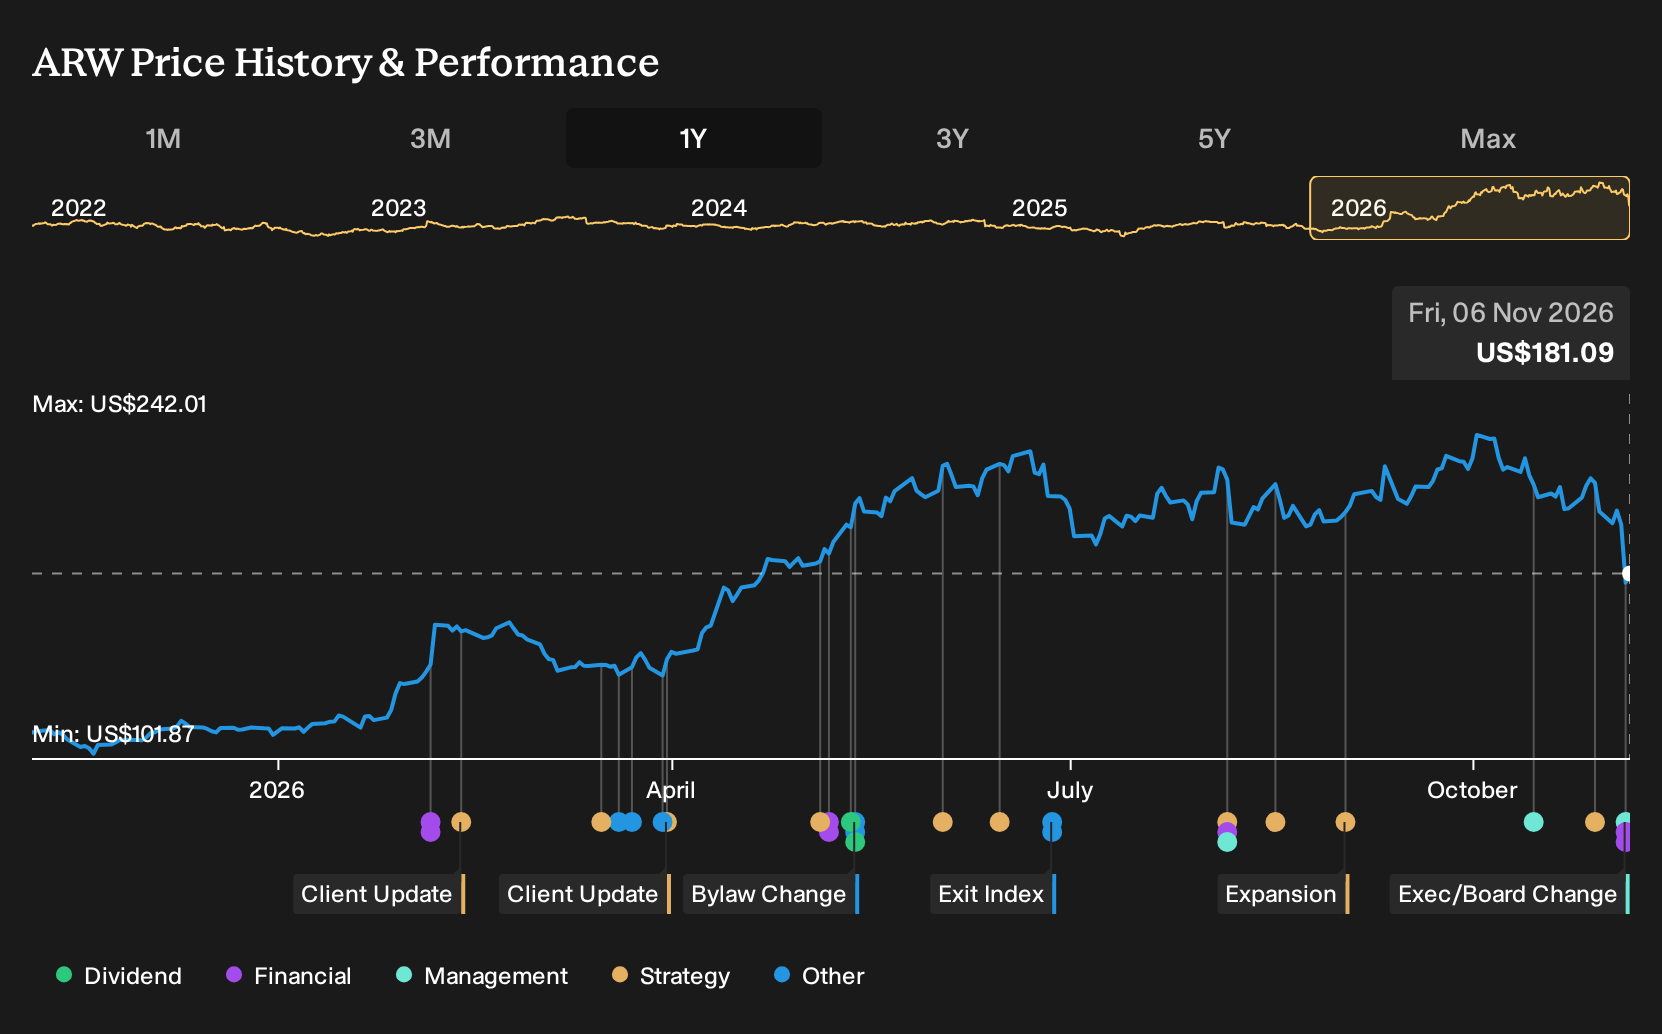
Arrow Electronics has been busy signing fresh work, including more than US$92 million of government contracts alongside a new US$1 billion share repurchase program that grabbed headlines this year. Holding Arrow Electronics over the past year would have returned 62.1%, including dividends. If you were weighing a buy on 6 November 2025, what would need to be true about AI driven demand, margin resilience, and capital allocation for that outcome to look reasonable upfront?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Arrow Electronics is not the only name tied to this theme. Zero in on 52 AI infrastructure stocks and compare how each one is priced.
The Two Arrow Electronics Stories Investors Had To Choose Between
The shares cost US$111 at the start of the period, and you had to decide which Arrow Electronics story felt closer to reality.
The bullish narrative pinned fair value at US$135. It was built on the idea that digital transformation and electrification would support sustained demand for advanced components, while value-added services and platforms like ArrowSphere increased recurring revenue and helped margins.
The bearish case pointed to a fair value of US$98. It focused on semiconductor industry corrections, mixed regional performance, and high inventory levels that could pressure revenue, cash flow, and profitability.
What The Arrow Electronics Evidence Actually Tested
Arrow Electronics then reported Q3 2026 revenue of US$10.7b versus US$7.7b in Q3 2025, with net income rising from US$109.2m to US$318.4m and net margin moving from 1.4% to 3.0%. That outcome leaned toward the bullish story on AI linked demand and margin resilience, although insider selling and overvaluation concerns meant the evidence still cut both ways.
The lesson is simple. When a thesis hinges on AI driven demand and better margins, track segment revenue, reported net margin, and the mix of higher value services rather than relying on a strong share price to make the case.
What Arrow Electronics' Run Leaves You Paying For
Arrow Electronics now trades at US$181 after a 62.1% gain over the past year. The selected Narrative places its Fair Value above that level and attributes the gap to how AI data center work, higher margin services and mix shift could affect earnings quality.
Instead of broad cyclicality, a buyer today would be assuming that supply chain services, cloud platforms and engineering work tied to AI and hyperscalers are still underappreciated in the current price.
"Arrow Electronics is scaling higher margin supply chain services for large hyperscalers, including programs where Arrow designs, builds and tests AI data center infrastructure and manages consigned inventory, AR and AP flows. This could support operating margins and earnings quality as more multi year agreements are signed."
One Narrative disagrees with today's price. → See where this Narrative says Arrow Electronics should trade
Find Your Own Contrarian Opportunity
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 39% below our estimate - targets AI-focused data workloads with dense, efficient enterprise flash storage platforms.
- Company 2 - 40% below our estimate - leans on an established AI software ecosystem to keep major compute buyers using its GPUs.
- Company 3 - 48% below our estimate - expands a digital small-business banking platform while aiming to manage credit and expense risks.
That is three of the list. See the full list of 39 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com