


EN
What Newmark Group Bears Saw Before The Fall
If you had looked at Newmark Group in late 2025 and decided to wait for “clearer proof” before buying, the past year would have felt like a painful kind of relief. For Newmark Group shareholders, the loss over the past year was 30.7%, including dividends. With strong quarterly headlines arriving through 2026, the obvious question is: what information was already on record in November 2025 that might have flagged this risk?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Newmark Group has already moved. Pinpoint other ways to investigate the theme among 52 AI infrastructure stocks.
The Two Stories Investors Had To Weigh On Newmark Group
The shares cost US$17.07 at the start of the period, and Newmark Group sat between two very different but reasonable stories about its future.
The optimistic narrative put Fair Value at US$18.45, with analysts assuming revenue growth of 8.2% a year and profit margins reaching 5.3%. That view leaned on expansion into data centers and other alternative assets.
The cautious case pointed to Fair Value of US$14. It focused on the risk that remote and hybrid work would depress office leasing and leave the core business exposed.
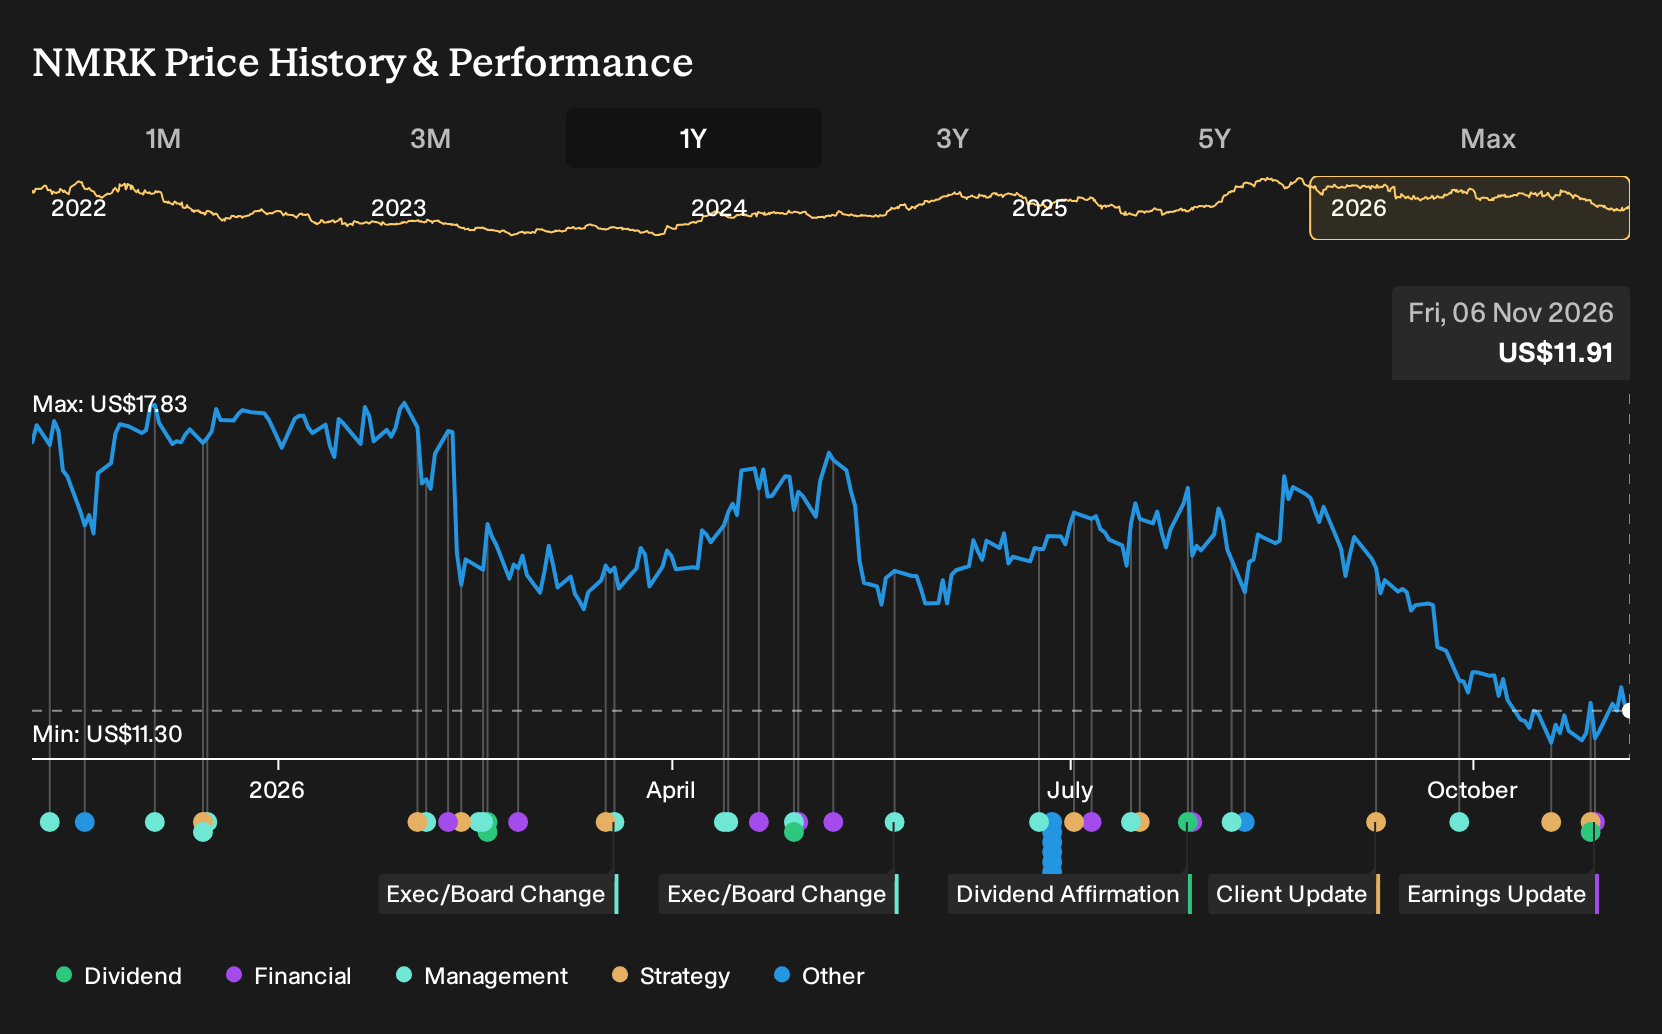
What the 2026 Results Put to the Test for Newmark Group
Newmark Group’s Q3 2026 figures gave the optimistic story some backing. Revenue moved from US$863.46 million in Q3 2025 to US$973.20 million, and net income also rose. The evidence on profitability was less clean. Net margin slipped from 5.3% to 5.0%, which meant the higher-margin part of the bull case still looked unproven. Overall, the data cut both ways.
The hinge assumption here was not growth alone but growth with stronger profitability. When you assess another company, check whether rising sales are matched by a higher net margin in the filings, not just by upbeat commentary.
What You Are Really Paying For In Newmark Group Today
Newmark Group now trades at US$11.91, with the selected Narrative arguing that its Fair Value sits above that level. The focus is less on a quick rebound and more on how fee mix, capital markets reach, and global services reshape the earnings base.
The Narrative centers on broader, higher margin management and servicing income, paired with global advisory and capital markets expansion. For that higher figure to be justified, a buyer today would need to believe Newmark can scale recurring fee pools faster than the cost and risk of that buildout.
"Key Takeaways: Analysts expect Newmark Group to keep pushing toward a higher mix of recurring management and servicing revenues, international advisory growth, and a larger real estate capital markets role, supported by recent revenue, earnings, and free cash flow performance. The main thing that has to go right is sustained execution on scaling higher margin management and servicing revenues, global advisory expansion, and capital markets share gains, while managing leadership transition and uneven property valuations."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Which Company Could Surprise You Next?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 50% below our estimate - uses partnerships and acquisitions to expand larger, recurring fee income streams.
- Company 2 - 41% below our estimate - applies AI tools and tighter carrier vetting to reduce fraud and insurance costs.
- Company 3 - 31% below our estimate - integrates a bank acquisition and automation platform to reshape its digital lending model.
That is three of the list. See the full list of 39 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com