


EN
Coherent Stock Earnings Beat Has The Bull Case Changed
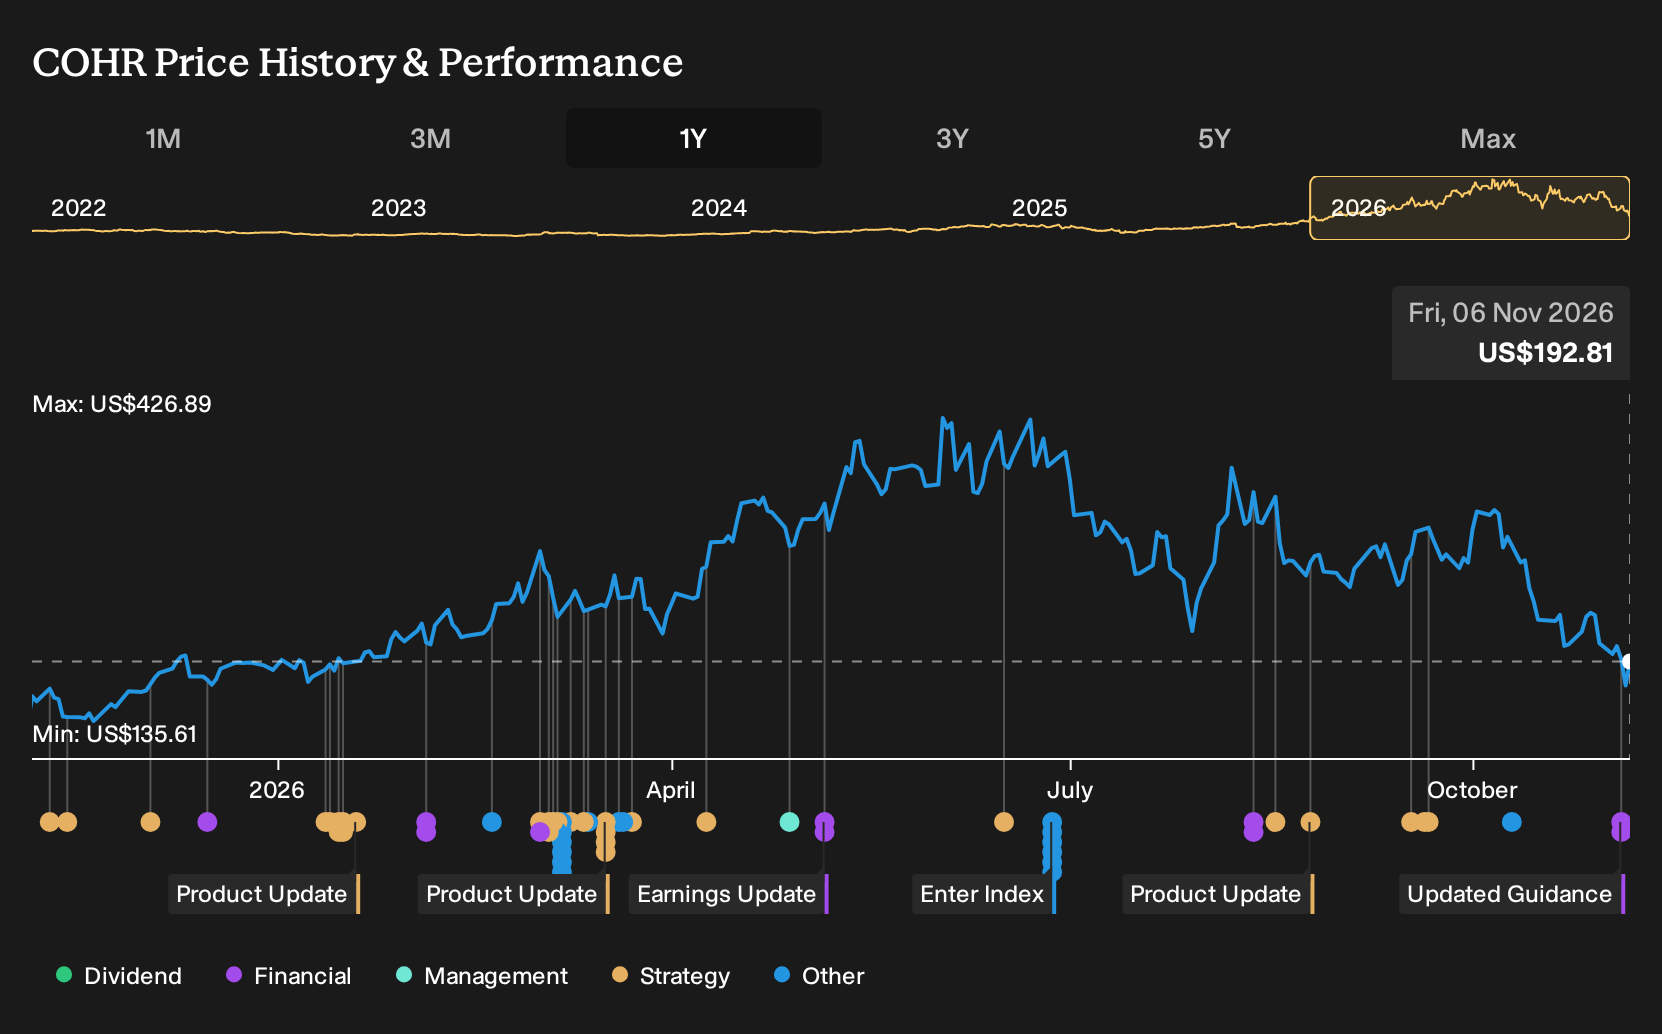
- Coherent reported first quarter fiscal 2027 sales of US$2,370.32 million and net income of US$384.67 million, and then forecast second quarter revenue between US$2.55 billion and US$2.75 billion.
- The business tied this guidance to surging AI datacenter demand, long term PhotonLink optics agreements including a US$20 billion contract, and a focus on higher margin photonics platforms.
- We will look at how Coherent's investment narrative is shaped by strong AI datacenter demand and its multiyear PhotonLink agreements.
Scan how Coherent's AI optics story compares with other hardware plays riding similar demand by reviewing the hand picked 52 AI infrastructure stocks.
Coherent Investment Narrative Recap
To own Coherent, you need to believe its AI oriented datacenter and communications operation can stay at the center of customer build outs while large capex and competition do not erode economics. The latest quarter, with US$2,370.32 million in sales and US$384.67 million in net income, supports that AI optics story but does not remove execution risk.
The key near term catalyst is continued strength in AI datacenter orders flowing through to revenue and margins while industrial and materials lines remain more mixed. The biggest current risk sits in heavy investment and customer concentration. Any pause in hyperscaler spending or pricing pressure in transceivers could quickly show up in earnings volatility.
The clearest recent announcement is Coherent’s long term PhotonLink optics agreement of about US$20b with a major AI customer, tied to integrated optics for future datacenters. That sits alongside first quarter basic EPS of US$1.96 and diluted EPS of US$1.90 from continuing operations, which gives investors a cleaner baseline for that contract.
For catalysts, that PhotonLink deal plus the guidance for second quarter fiscal 2027 revenue between US$2.55b and US$2.75b points to a multiyear AI build out that depends on Coherent scaling indium phosphide and maintaining product differentiation. The related risk is customer concentration and pricing pressure if cheaper Asian competitors target these same optics platforms.
Coherent's narrative projects US$19.3b revenue and US$3.6b earnings by 2029. This implies analysts are penciling in 39.4% yearly revenue growth and an earnings increase of roughly US$2.8b from US$769.9m today.
Discover how Coherent's fair value indicates a 101% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
The bearish narrative on Coherent leans hard on a single worry. Capacity could be built for PhotonLink and 6 inch indium phosphide just as AI optics demand cools. Before this new guidance, the lowest analysts were only modeling about US$18.4b of revenue and US$3.4b of earnings by 2029. That is a meaningfully more cautious story than consensus. It shows how far opinions can stretch. Use it as a reminder to compare several viewpoints before deciding how this fresh Q2 outlook might reshape your own.
Explore 4 other Coherent fair value estimates, including one that suggests it could be worth just $387.80!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so consider forming your own view.
- A great starting point for your Coherent research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Coherent. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coherent's overall financial health at a glance.
Looking For More Investment Ideas Beyond Coherent?
Once you have formed a view on Coherent, it can help to set it beside other opportunities with very different risk and income profiles. A quick pass through a few focused stock lists can sharpen your sense of what feels attractive for your own portfolio.
- For steadier profiles where balance sheet strength takes priority over excitement, scan the list of solid balance sheet and fundamentals (24 results) to see which businesses pair financial resilience with cleaner fundamentals.
- If you prefer to aim at potential mispricing, compare Coherent with companies that screen as attractively valued using the 39 high quality undervalued stocks to spot ideas where quality and pricing line up.
- Income focused investors who want cash returns paid regularly can review the 8 dividend fortresses and see which payouts and balance sheets look worth a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com