


EN
Why AppLovin Stock Is In Focus After Record Earnings
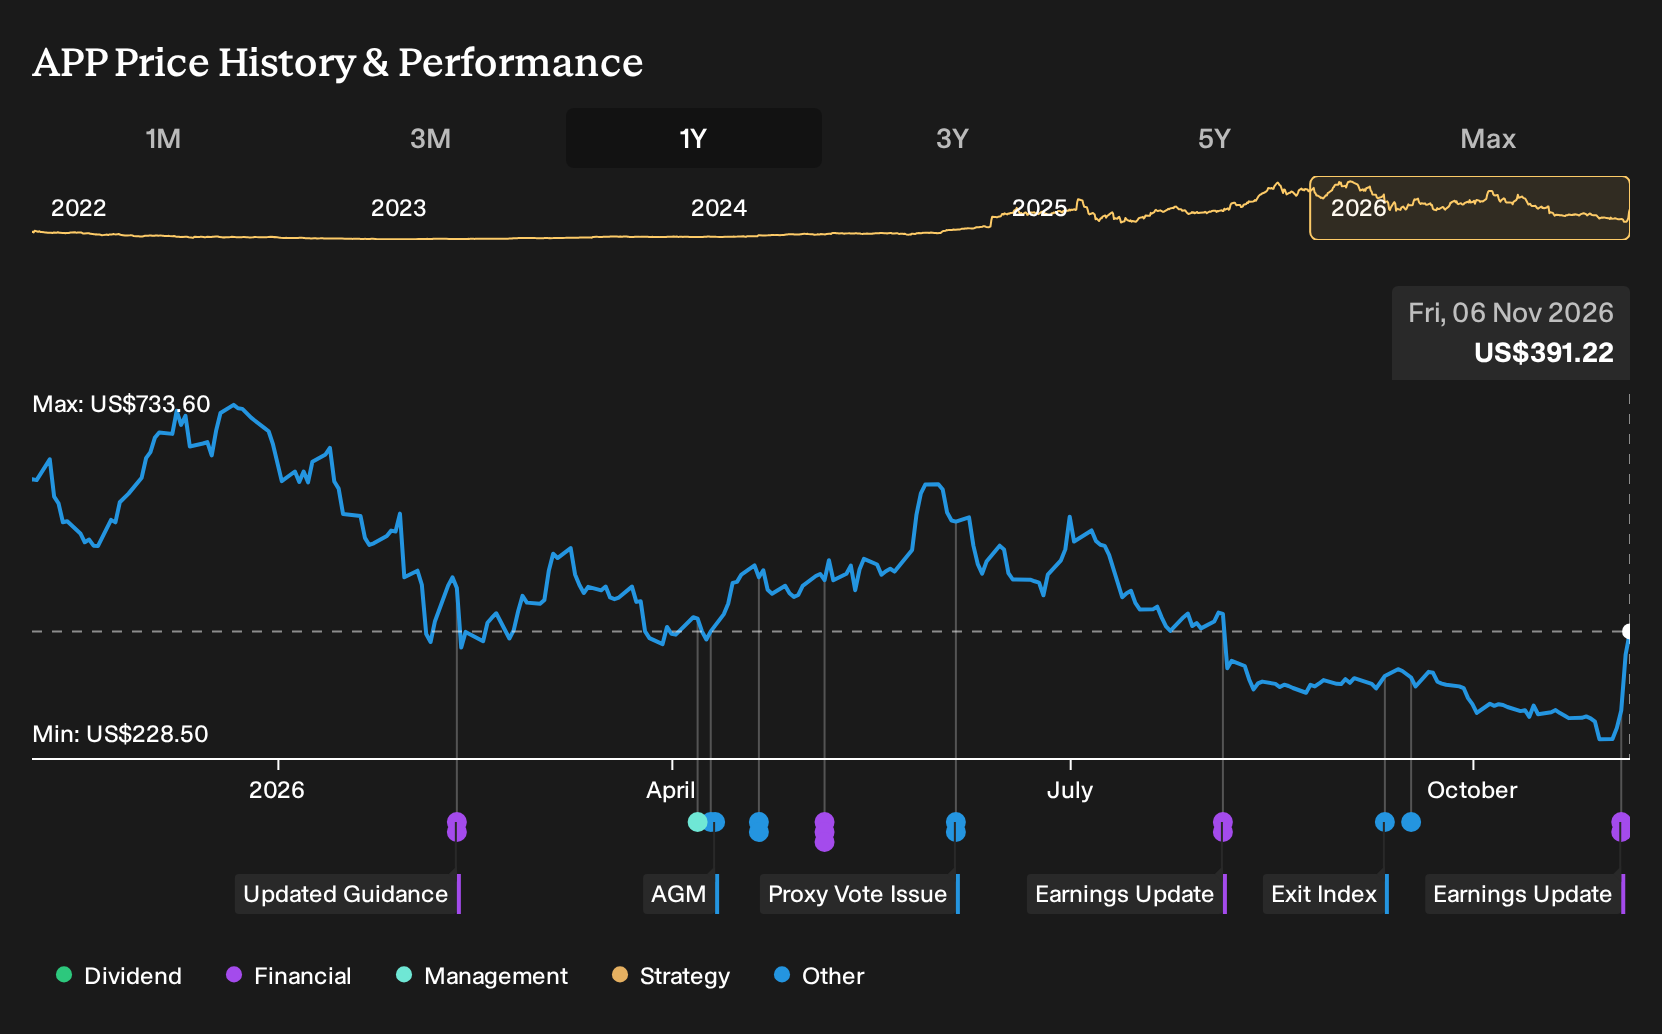
- AppLovin reported record Q3 2026 results, with revenue of US$2.19b and net income of US$1.44b, alongside strong nine-month profitability and guidance for Q4 sales between US$2.37b and US$2.40b.
- The business linked this performance to upgraded AI driven ad models and paired it with a US$3.6b total share repurchase authorization, signaling a focus on both product efficiency and capital returns.
- Next, the focus will be on how AppLovin's AI powered earnings strength and expanded buyback program reshape the existing investment narrative.
See how AppLovin’s AI-driven ad momentum compares with other potential breakouts by checking a curated list of 52 AI infrastructure stocks in the same broad theme.
AppLovin Investment Narrative Recap
To own AppLovin, you need to buy into the idea that its AI powered ad engine can keep attracting budgets from both mobile gaming and newer consumer verticals while holding on to strong profitability. Q3 pointed to that thesis in the numbers, with high net income and very wide margins, but it also raised the bar for what advertisers and investors now expect.
In the near term, the key swing factor is whether the partial rollout of the new models and the Q4 revenue outlook translate into sustained demand without forcing much higher compute or sales spend. The biggest risk still sits around regulation, legal disputes and any sign that gaming centric demand or newer use cases begin to soften after this spike.
The clearest supporting announcement for this earnings story is AppLovin’s move to lift its total share repurchase authorization to US$3.6b after already buying back 4.1 million shares for US$1.4b. That capital return sits on top of nine month net income of US$3.9b and points to very strong cash generation during the period.
For you as a shareholder, the enlarged buyback can tighten the share count if executed, which may amplify the effect of any future earnings progress. It also concentrates exposure to the same legal, competition and privacy risks, since more of the profit stream accrues to remaining investors if AI model execution and advertiser appetite stay supportive.
What The AppLovin Forecasts Assume
AppLovin's narrative projects US$13.1b revenue and US$8.5b earnings by 2029, based on analyst estimates. This implies 24.2% yearly revenue growth and roughly a 1.9x earnings increase from US$4.4b today.
Discover why AppLovin's fair value indicates a 20% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
One sharp disagreement around AppLovin comes from a more pessimistic view on its AI driven margins. The lowest analysts were pencilling in earnings of about US$8.1b by 2029 on roughly 62% margins, compared with consensus US$8.5b. Those forecasts were set before this Q3 surprise, so you may see opinions shift as fresh numbers feed in.
Explore 12 other AppLovin fair value estimates, including one that suggests as much as 15% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your AppLovin research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AppLovin. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AppLovin's overall financial health at a glance.
Looking For More Investment Ideas Beyond AppLovin?
Once you have a view on AppLovin, it can help to set it alongside other opportunities that match the kind of risk, income or quality profile you want in your portfolio. The Simply Wall St Screener gives you curated shortlists so you can quickly compare businesses on the factors that matter most to you.
- If you want potentially underappreciated opportunities with solid fundamentals, start with a curated set of 19 high quality undiscovered gems that may not yet be widely followed.
- For investors who care most about balance sheet strength and business durability, filter for companies on the list of solid balance sheet and fundamentals (24 results) that can help anchor a more resilient portfolio.
- If limiting downside risk is your priority, narrow the field to a focused group of 29 resilient stocks with low risk scores that score well on stability metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com