


EN
Mobileye Global (MBLY) Lifts Guidance Following Earnings As Fair Value Debate Returns
Guidance shift and fresh earnings put Mobileye Global in focus
Mobileye Global (MBLY) moved back into the spotlight after management raised full year 2026 revenue guidance and released third quarter results, giving investors new data on both outlook and recent performance.
The company now projects 2026 revenue between US$1,995 million and US$2,020 million, slightly narrowing and lifting the lower end of its previous range. This adjustment in guidance arrives alongside fresh quarterly and nine month figures that show a mix of sales growth over the longer stretch and sizeable losses that remain a key part of the story.
Mobileye Global’s guidance tweak landed against a tough backdrop, with the share price jumping 11.7% on the day to US$5.73, yet still down 19.9% over 30 days and 49.0% year to date, while the 1 year total shareholder return has fallen 54.6% and the 3 year total shareholder return is down 84.7%. This points to improving short term momentum after a prolonged reset in expectations.
Spot opportunities around Mobileye Global’s reset by scanning a curated set of 52 AI infrastructure stocks that are shaping the future of autonomous driving and data-heavy computing.After an 11.7% rebound, yet deep multi year losses and heavy recent net losses, the real tension around Mobileye Global now sits in the valuation. Do these prices still skew the risk reward toward buyers?
Most Popular Narrative: 39% Undervalued
With Mobileye Global last closing at $5.73 and the most followed narrative anchoring fair value at $9.37, the current quote implies a wide gap that investors need to justify with their own expectations on growth, margins and risk.
The current valuation and this narrative together imply the share price does not fully reflect the cash generative ADAS business, future Surround ADAS contribution and optionality in robotaxes and humanoid robotics.
The convergence of autonomous driving and humanoid robotics around shared AI perception and simulation capabilities, supported by the acquisition of Mentee Robotics and a roadmap to commercial humanoid deployments from around 2028, introduces additional long term revenue and earnings optionality that current expectations may not fully reflect.
See why 74 investors see Mobileye Global as 39% undervalued.
Result: Fair Value of $9.37 (UNDERVALUED)
Still, shrinking SuperVision shipments and pressure from China related tariffs could quickly weaken the Mobileye Global narrative if ADAS volumes or pricing disappoint.
Find out about the key risks to this Mobileye Global narrative.
Another View On Mobileye Global’s Valuation
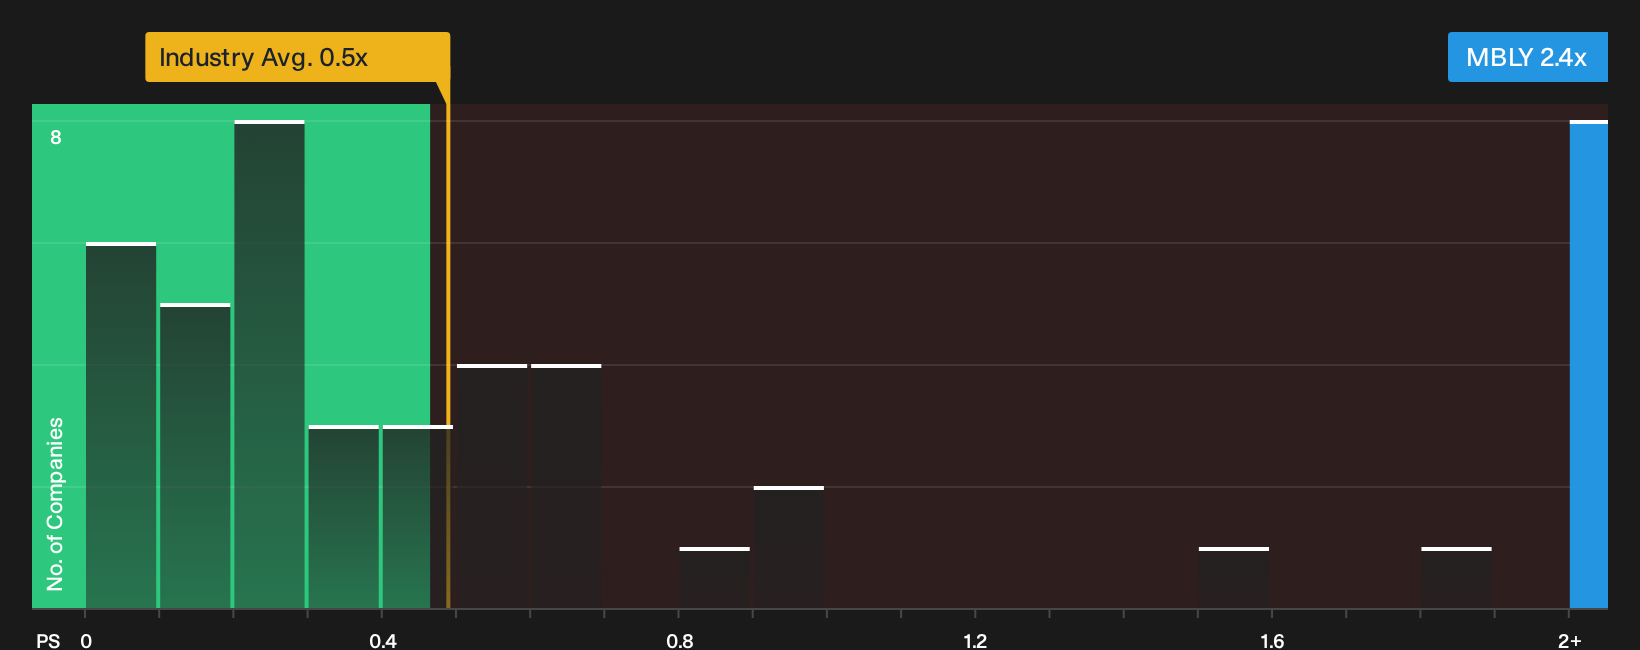
There is a twist once you step away from fair value estimates and look at plain P/S math. Mobileye Global trades at a P/S of 2.4x, which is double the peer average at 1.2x and far above the US Auto Components industry at 0.5x, yet still slightly below a fair ratio of 2.6x. That mix of premium vs peers and small discount vs fair ratio raises a simple question. Is the stock cheap on fundamentals or just less expensive than it used to be?
For a closer look at how that sales multiple stacks up against the rest of the sector and where the ratio could move over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of pressure and optimism around Mobileye Global feels unresolved, do not wait for consensus to form before you act. Review the full breakdown of the upside factors behind this story through 2 key rewards.
Looking for more investment ideas beyond Mobileye Global?
If Mobileye Global has your attention, do not stop at a single ticker. Broaden your watchlist and give yourself more ways to put capital to work.
- Target potential mispricing by scanning a focused pool of high quality valuations through 39 high quality undervalued stocks.
- Strengthen portfolio resilience by concentrating on companies with robust finances using the list of solid balance sheet and fundamentals (24 results).
- Put your cash to work in income focused opportunities by reviewing a curated set of 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com