


EN
How Investors May Respond To SM Energy Stock After Debt Reduction Progress
- SM Energy reported third quarter 2026 revenue of US$2,170 million and net income of US$93 million, with basic EPS from continuing operations of US$0.39, while nine month revenue reached US$6,149 million and net income was US$829 million.
- The business has largely met its US$1 billion divestiture target through the US$950 million Galvan sale, used about US$1.3 billion for net debt reduction, and actioned roughly US$400 million of merger synergies, reshaping its cost base and balance sheet.
- We will look at how SM Energy's investment narrative is affected by this debt paydown driven by the Galvan divestiture.
Scan how SM Energy's balance sheet reset compares with other operators that also emphasise debt reduction and cash generation in our hand-picked list of solid balance sheet and fundamentals (24 results).
SM Energy Investment Narrative Recap
To own SM Energy, you need to be comfortable with a story that leans on cost efficiency, multi basin flexibility and disciplined use of cash, rather than chasing volume at any price. The third quarter showed that, even with revenue of US$2,170 million and net income of US$93 million, earnings per share can feel tight when costs and depletion weigh on results.
The near term swing factor is whether SM Energy can keep translating its operational gains and merger synergies into consistent free cash generation while carrying a relatively high absolute debt load. The biggest risk is a weaker commodity backdrop or project level disruptions hitting cash flow just as the balance sheet is being reset.
The most relevant update for that thesis is the recent report that SM Energy has actioned about US$400 million of merger synergies, roughly doubling its original target. Those savings directly address the cost side of the equation and support the idea of a structurally leaner operating model, even if quarterly earnings move around.
On top of that, the Galvan sale and US$1.3 billion of net debt reduction, with no senior note maturities until mid 2028, give management more breathing room to focus on execution in the Permian, South Texas, Uinta and DJ assets. For you as a shareholder, the question is whether that combination of lower leverage and lower costs is enough to offset exposure to commodity prices, regulatory friction and recent share dilution.
SM Energy's current analyst framework points to forecast revenue of US$7.4b and projected earnings of US$1.8b by 2029, based on assumed yearly revenue growth of 14.4% and an earnings increase of about US$0.8b from US$1.0b today.
Discover how SM Energy's fair value indicates a 54% potential upside to its current price that may not last much longer.
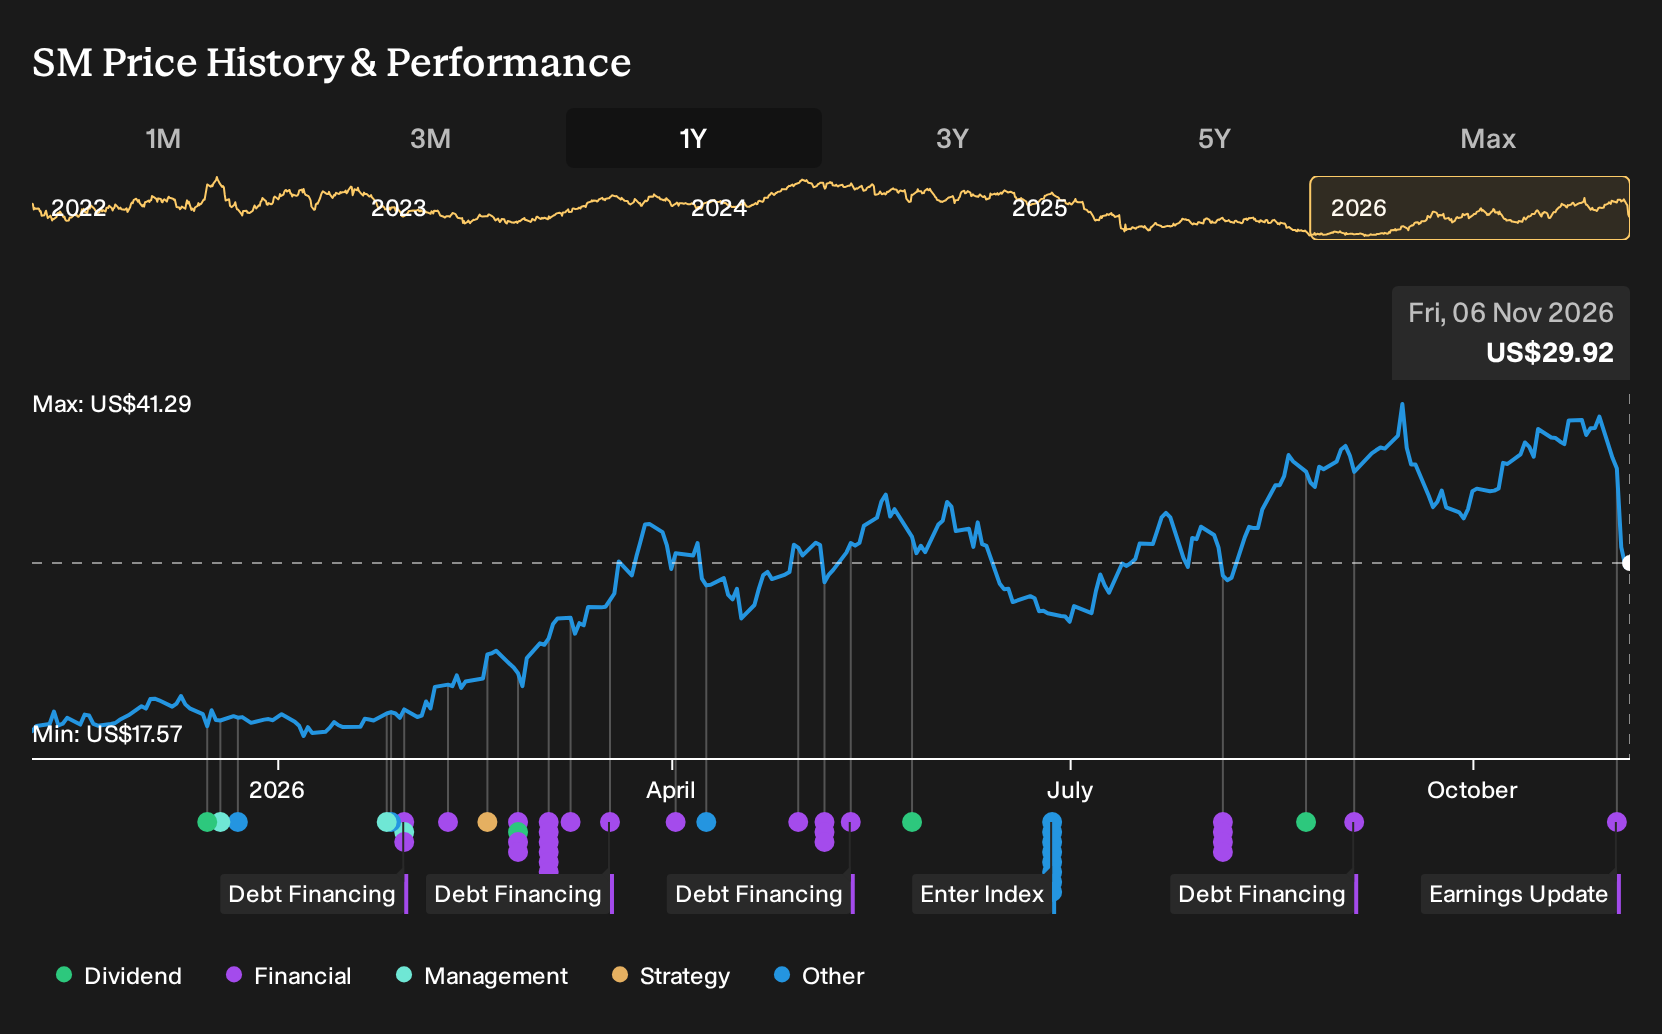
Exploring Other Perspectives
One alternate view on SM Energy leans hard on valuation risk. The most cautious analysts were working off a US$35.0 price target and 2029 earnings of about US$1.6b on US$7.6b of revenue, which they saw as already priced in. Those forecasts pre date this quarter, so you may see those narratives shift as new numbers sink in.
Explore 5 other SM Energy fair value estimates, including one that suggests it could be worth just $35.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SM Energy research is our analysis highlighting 6 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for SM Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SM Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond SM Energy?
If SM Energy has sharpened your focus on balance sheets, cash flow and risk, it can help to line that thesis up against a wider field of companies. The Simply Wall St Screener lets you filter the market by exactly the traits you care about so you can keep building a watchlist that fits your approach.
- If you want potential upside with a small starting price tag, scan 9 elite penny stocks with strong financials that already show stronger financial quality than many peers.
- If resilience matters most to you, filter for 29 resilient stocks with low risk scores that pair steadier fundamentals with lower overall risk scores.
- If you prefer under the radar prospects with solid metrics, comb through 19 high quality undiscovered gems that screen well on both quality and valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com