


EN
Axalta Coating Systems (AXTA) Q3 Results Put Its Undervalued Narrative To The Test
Axalta Coating Systems (AXTA) has released its third quarter 2026 results, reporting sales of US$1,311 million and net income of US$95 million, along with guidance that indicates flat to low single digit sales growth.
Axalta Coating Systems shares have climbed recently, with a 7 day share price return of 6.99% and a 30 day gain of 11.16%, even though the 90 day move shows a 4.56% decline. At the same time, the 1 year total shareholder return of 25.73% points to solid longer term momentum building around the story.
Scan how Axalta Coating Systems compares to other coatings and materials players with resilient fundamentals using our hand picked list of solid balance sheet and fundamentals (24 results).
Axalta Coating Systems has rallied strongly over the past year, while current guidance points to only flat to low single digit sales growth. Is most of the re-rating already reflected in the share price, or could there still be some room left?
Most Popular Narrative: 7% Undervalued
Axalta Coating Systems is trading at a last close of $36.45 against a widely followed fair value estimate of $39.33, which frames the current move as a moderate re-rating rather than a stretched price.
The planned all stock merger of equals with AkzoNobel, with shareholder approvals already secured and a targeted US$600m of annual run rate cost synergies where most are expected within three years of closing, could materially influence Axalta Coating Systems' future net margins, free cash flow and earnings power as integration progresses.
See why 3 investors see Axalta Coating Systems as 7% undervalued.
Result: Fair Value of $39.33 (UNDERVALUED)
Still, higher raw material costs and soft demand in construction facing Axalta Coating Systems could pressure margins and unsettle confidence in that undervaluation story.
Find out about the key risks to this Axalta Coating Systems narrative.
Another View: What Axalta Coating Systems’ P/E Is Telling You
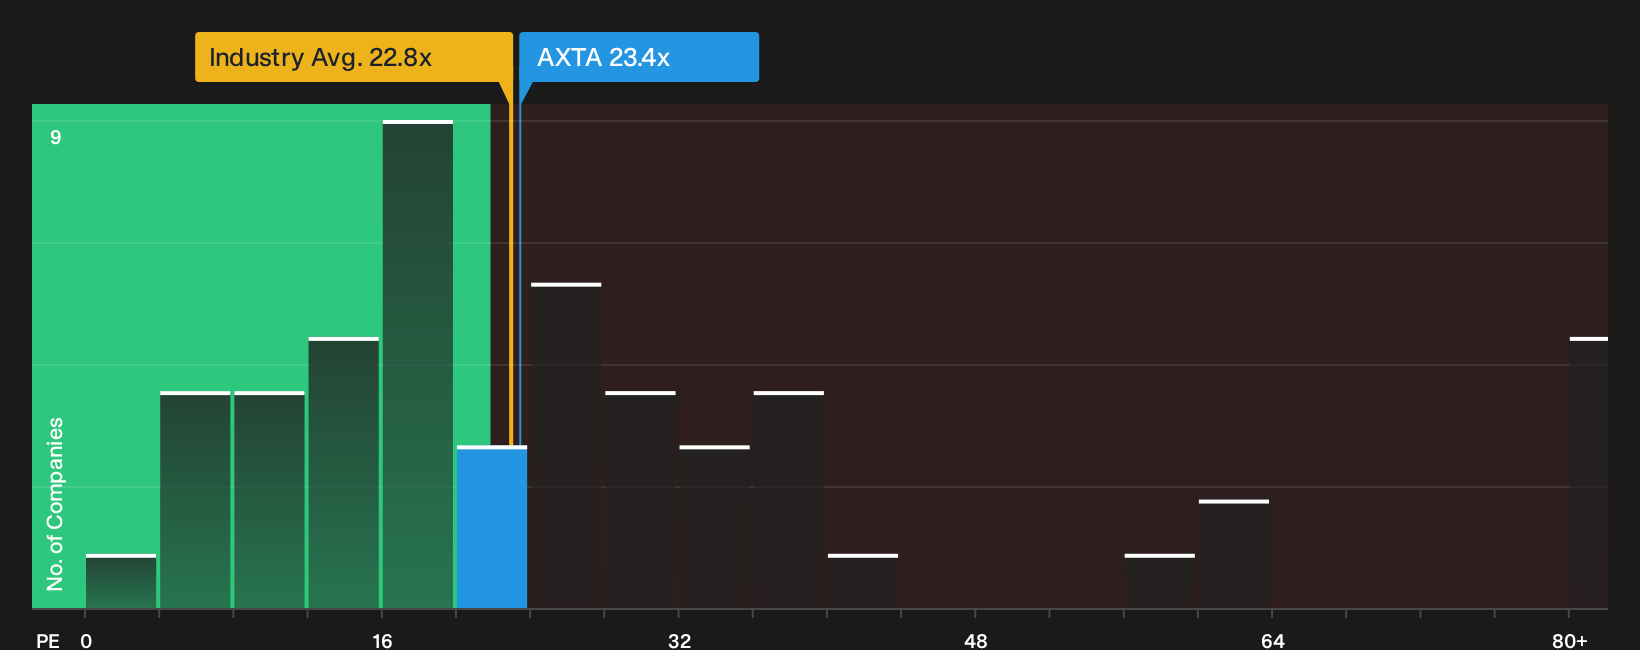
That 7% discount to fair value paints Axalta Coating Systems as modestly undervalued. Yet the stock trades on a P/E of 23.4x compared with a fair ratio of 20.3x, and 22.8x for both the US Chemicals industry and peer group. The premium may signal optimism, or it could be a margin for disappointment if earnings progress slows.
If you prefer to anchor your work in simple earnings multiples, our fair ratio framework can help you size up how much valuation risk you are really taking with Axalta Coating Systems, and whether comparable alternatives look cleaner on the numbers. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mix of optimism and concern around Axalta Coating Systems only matters if you put the figures in context and decide what they mean for you. Act while sentiment is still forming by weighing both sides of the story with the 2 key rewards and 1 important warning sign.
Looking for more Axalta Coating Systems style investment ideas?
If you like how Axalta Coating Systems frames risk and reward, do not stop here. Use targeted screeners to surface fresh ideas built on real fundamentals.
- Target strong value potential by reviewing a curated 39 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Prioritize resilience by running through a 29 resilient stocks with low risk scores focused on companies with sturdier balance sheets and lower overall risk scores.
- Hunt for the next overlooked opportunity by scanning a 19 high quality undiscovered gems packed with underfollowed stocks that still show solid financial underpinnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com