


EN
How Investors May Respond To Bristow Group Stock After Q3 Earnings
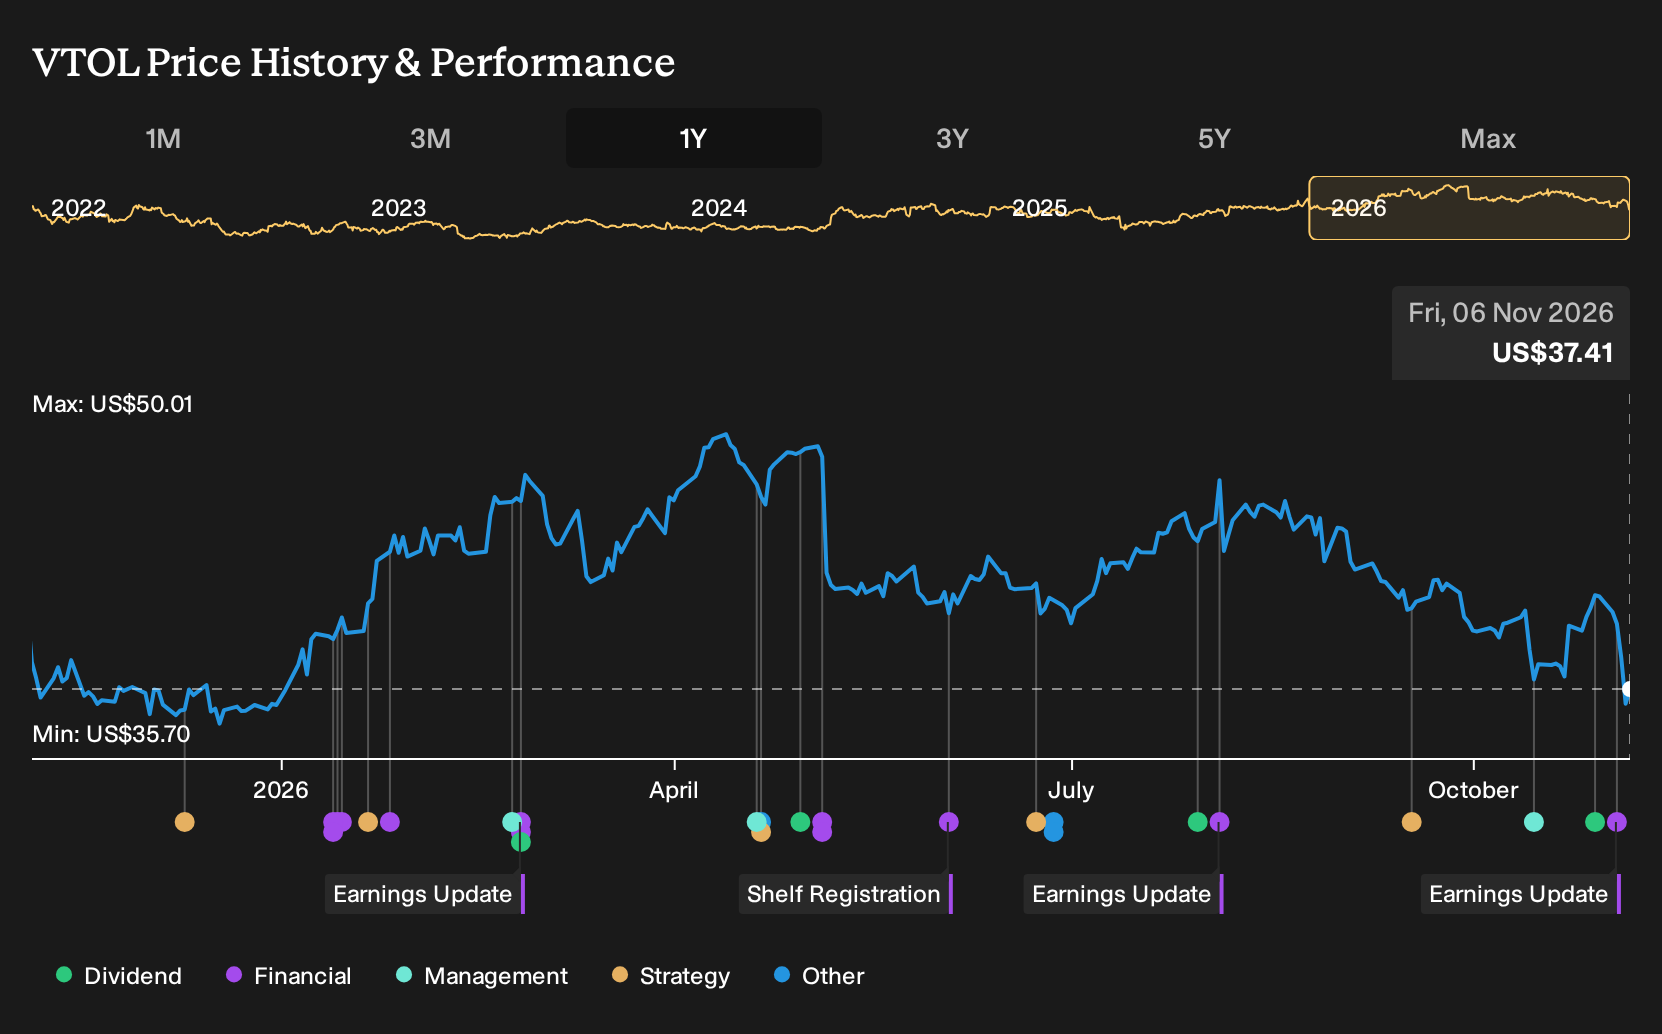
- Bristow Group reported third quarter 2026 results with sales of US$437.92 million and net income of US$27.73 million, equal to basic earnings of US$0.94 per share from continuing operations.
- The firm paired those earnings with a regular quarterly dividend of US$0.125 per share, which highlighted a commitment to directing some cash generation back to shareholders while it manages its vertical flight services portfolio.
- This analysis explores how Bristow Group's investment narrative is shaped by its third quarter profit and the maintained cash dividend.
Compare Bristow Group's income and dividend profile with hand picked aviation and infrastructure peers in the list of solid balance sheet and fundamentals (24 results) to see how other operators balance profitability with resilience.
Bristow Group Investment Narrative Recap
To own Bristow Group, you have to buy into a story where long duration government search and rescue work and repriced offshore contracts gradually support steadier profits, even while execution around aircraft availability stays bumpy. The Q3 2026 result, with US$437.92 million in sales and US$27.73 million in net income, adds another datapoint rather than a sharp reset.
The near term swing factor still sits in how efficiently Bristow Group manages contract transitions and supply chain friction that have previously weighed on margins. The key risk stays the same. If higher margin work and portfolio reshaping do not convert into stronger free cash flow, there is less room for debt reduction, reinvestment and continued shareholder payouts.
The reaffirmed US$0.125 quarterly dividend announced on 29 October 2026 is the clearest operational signal around this earnings print. Bristow Group is choosing to keep a cash return in place while it funds government ramp ups, offshore repricing and the integration of Berry Aviation, all against a backdrop of high debt and mixed recent profitability trends.
For you as a shareholder, that dividend is relevant to the main catalysts. Steadier contracted government revenue and repriced offshore work need to support both balance sheet flexibility and ongoing distributions. If supply chain constraints or weaker than expected margins persist and free cash flow remains tight, the payout could come under scrutiny, so monitoring coverage from earnings and cash generation now matters more than the headline yield.
Bristow Group's narrative projects US$2.0b revenue and US$241.1 million earnings by 2029, which reflects forecast yearly revenue growth of 7.9% and an earnings increase of about US$136.9 million from US$104.2 million today.
Uncover why Bristow Group's fair value indicates a 72% potential upside to its current price, a discount that could narrow as sentiment catches up.
Exploring Other Perspectives
One alternate view zooms in on Bristow Group’s cash generation rather than contract wins. The most cautious analysts were pencilling in about US$2.0b of revenue and US$225.0 million of earnings by 2029, yet still saw only a US$56.0 fair value. That is a much tougher lens on today’s Q3 profit and dividend. You can use those more pessimistic assumptions as a reference point to test how this fresh earnings release might reshape expectations over time.
Explore 3 other Bristow Group fair value estimates, including one that suggests it could be worth just $64.33!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis.
- A useful starting point for your Bristow Group research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bristow Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Bristow Group's overall financial position at a glance.
Looking For More Ideas Beyond Bristow Group?
If the Bristow Group story leaves you wanting a broader watchlist, it can help to line it up against other opportunities that fit very different profiles.
- For investors who want quality on sale, compare Bristow against companies that screen as potential value opportunities in the 39 high quality undervalued stocks.
- If steadier balance sheets matter most to you, focus on businesses with stronger financial cushions using the list of solid balance sheet and fundamentals (24 results).
- Those hunting for future market leaders before they become widely followed can scan for smaller, under-covered stocks through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com