


EN
What Ingram Micro Holding (INGM)'s Strong Earnings Outlook Means For Shareholders
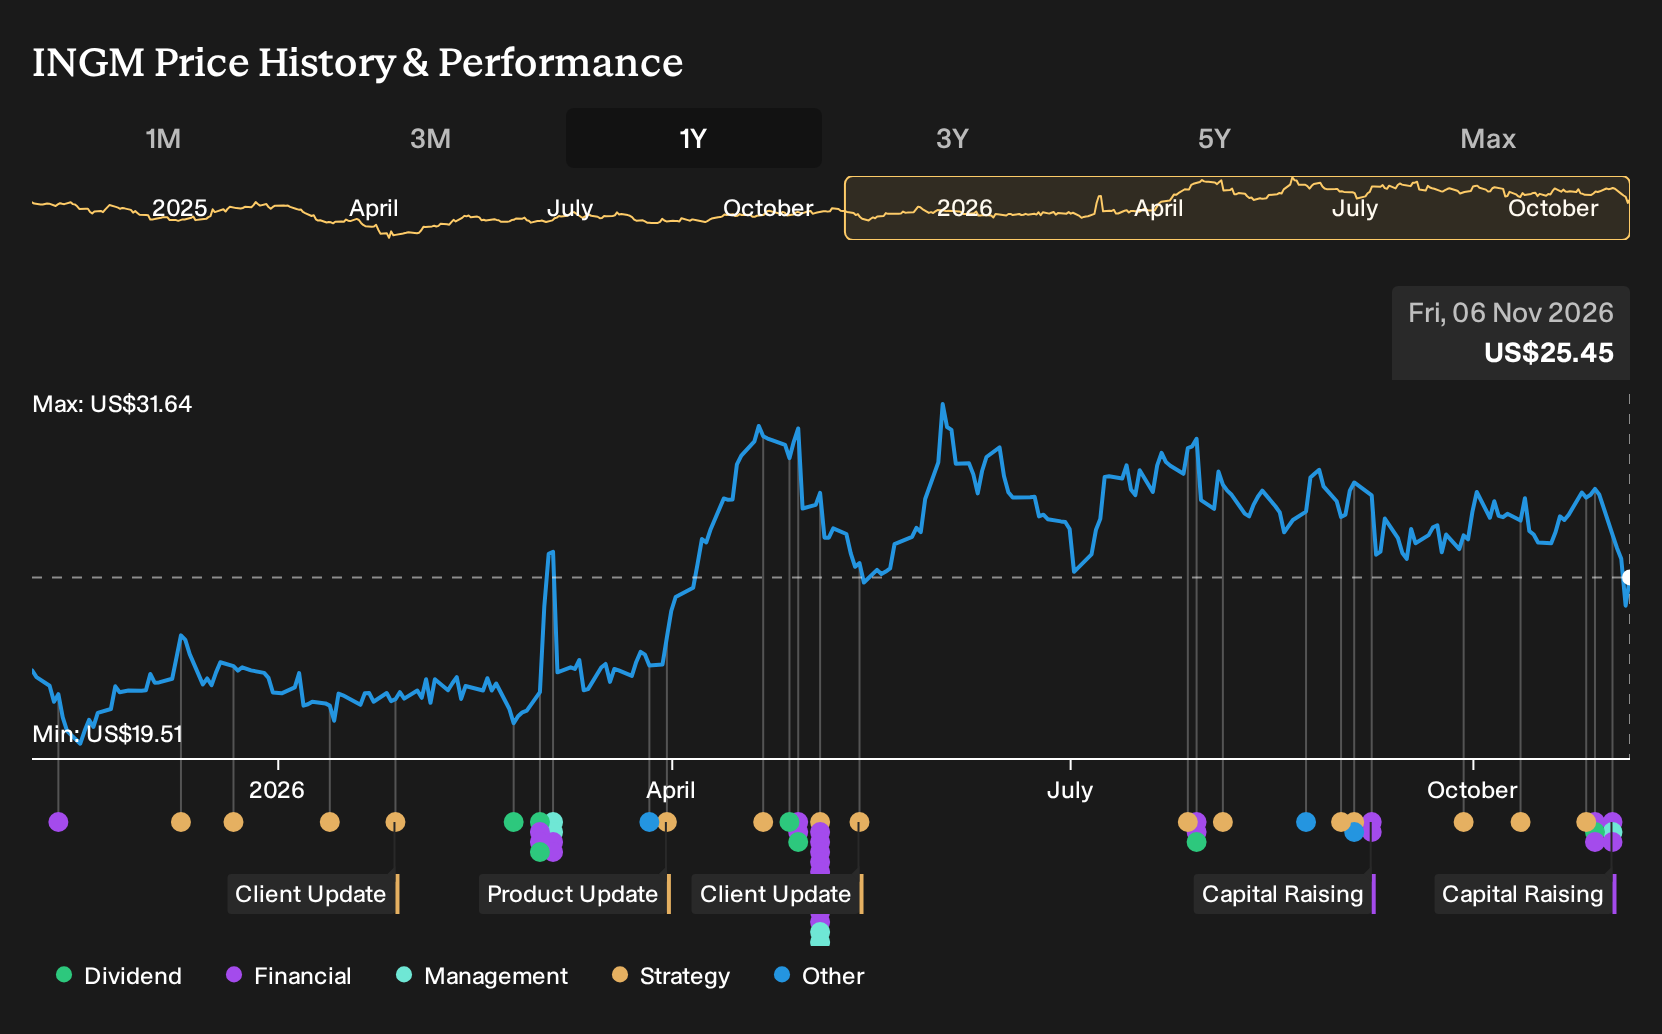
- Ingram Micro Holding has completed a follow on equity offering of 11,000,000 common shares for about US$284.9 million at US$25.90 per share, shortly after reporting third quarter 2026 results that showed higher sales, net income and earnings per share versus the prior year.
- The equity raise comes alongside fourth quarter 2026 net sales guidance of US$17.5b to US$17.9b and a modest dividend increase. Together, these developments indicate that management is funding growth and capital returns while still using buybacks earlier in the year.
- We will now explore how Ingram Micro Holding's stronger third quarter earnings and higher fourth quarter guidance influence its investment narrative.
Scan how Ingram Micro Holding’s fresh equity raise and higher sales tie into a broader trend in quality, cash generative businesses by comparing it with 39 high quality undervalued stocks.
Ingram Micro Holding Investment Narrative Recap
To own Ingram Micro Holding, an investor needs to be comfortable with a high volume, low margin distribution model that leans on scale, working capital and digital platforms like Xvantage to squeeze more earnings out of each dollar of sales. The recent equity raise, coming after stronger third quarter results and higher fourth quarter sales guidance, supports that capital intensive reality rather than changing it.
The near term catalyst is execution on AI centric hardware, enterprise solutions and SMB demand while keeping margins and cash generation under control as volumes rise. The main risk is that large, low margin GPU and infrastructure deals plus elevated inventory needs stretch the balance sheet and dilute profitability if demand or cloud growth underperforms.
Among the recent announcements, the SMB Quick Buy launch with Cisco on the Xvantage platform looks most relevant to the equity raise and earnings story. This tool targets one of Ingram Micro Holding’s key potential profit drivers, higher margin SMB solutions, by using automation and AI to simplify configuration, quoting and ordering for partners.
If SMB Quick Buy helps partners process more Cisco and Meraki transactions with fewer manual touchpoints, that can support operating leverage and improve mix toward repeatable, service rich workflows. The same distribution network that now has fresh equity capital behind it also carries execution risk, because slower partner adoption of Xvantage features or weaker SMB demand would limit how much these digital tools can contribute to the catalysts investors are focused on.
Ingram Micro Holding's narrative projects US$61.4b revenue and US$678.6 million earnings by 2029. This implies 3.1% yearly revenue growth and an earnings increase of about US$248 million from US$430.6 million today.
Uncover how Ingram Micro Holding's fair value indicates a 30% potential upside to its current price that could narrow faster than many investors expect.
Exploring Other Perspectives
One alternate view on Ingram Micro Holding leans heavily on free cash flow risk. Before this equity raise, the most cautious analysts were working off roughly US$60.2b of 2029 revenue and US$668.3 million of earnings, only slightly below consensus. You can read that as a much more muted story that might shift as this capital raise and stronger guidance are absorbed.
Explore another Ingram Micro Holding fair value estimate, including one that suggests it could be worth just $31.93!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ingram Micro Holding research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ingram Micro Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ingram Micro Holding's overall financial health at a glance.
Looking for more investment ideas beyond Ingram Micro Holding?
Once you have a view on Ingram Micro Holding, it can help to compare that thesis with other companies that share similar qualities or offer a very different risk profile. The Simply Wall St Screener gives you a fast way to line up those options side by side using the metrics that matter to you.
- For investors who care most about resilient balance sheets and steady fundamentals, consider scanning a list of solid balance sheet and fundamentals (24 results) that might complement or contrast with Ingram Micro Holding in your portfolio.
- If capital preservation and smoother return profiles are higher on your list, check out 29 resilient stocks with low risk scores that could suit a more cautious approach.
- When you want upside potential backed by strong business quality rather than hype, take a look at 19 high quality undiscovered gems that may offer fresh ideas alongside Ingram Micro Holding.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com