


EN
Seadrill (SDRL) Earnings Reset The Valuation Debate After Higher 2026 Guidance
Seadrill earnings spark fresh look at the stock
Seadrill (SDRL) just paired a fuller 2027 drilling schedule with a third straight increase to its annual outlook, after raising 2026 operating revenue and adjusted EBITDA guidance on the latest earnings call.
Recent trading has been choppy. Seadrill's share price slipped 19.73% over the past week and is down 5.51% over the past month, even though the year to date share price return is 20.74% and the 1 year total shareholder return is 48.12%. This suggests longer term momentum remains in place as the market weighs the richer 2027 schedule and higher 2026 guidance against the latest quarterly loss and updated risk profile.
Scan other offshore and energy contractors that are showing similar contract momentum and cash generation potential with our hand picked 39 high quality undervalued stocks.
After a sharp pullback against stronger guidance and a fuller 2027 book, Seadrill now asks a simple question of buyers: Does the updated risk profile still justify paying today’s price for that future work?
Most Popular Narrative: 22% Undervalued
On the most followed view, Seadrill's fair value sits at $54.00, comfortably above the last close at $42.20. This puts the current pullback against that higher 2026 guidance in sharper relief.
The shift from heavy project spending on reactivations and reacceptances toward lower capital expenditure guidance of US$200 to US$240m, together with refinancing at lower coupons and an extended share repurchase authorization, points to an inflection toward stronger free cash flow and potential improvement in net margins and per share earnings.
See why 11 investors see Seadrill as 22% undervalued.
Result: Fair Value of $54.00 (UNDERVALUED)
Still, the Seadrill story can unravel quickly if offshore customers cut back spending, or if weaker margins and cash generation persist despite the current backlog.
Find out about the key risks to this Seadrill narrative.
Another View: Seadrill looks expensive on sales
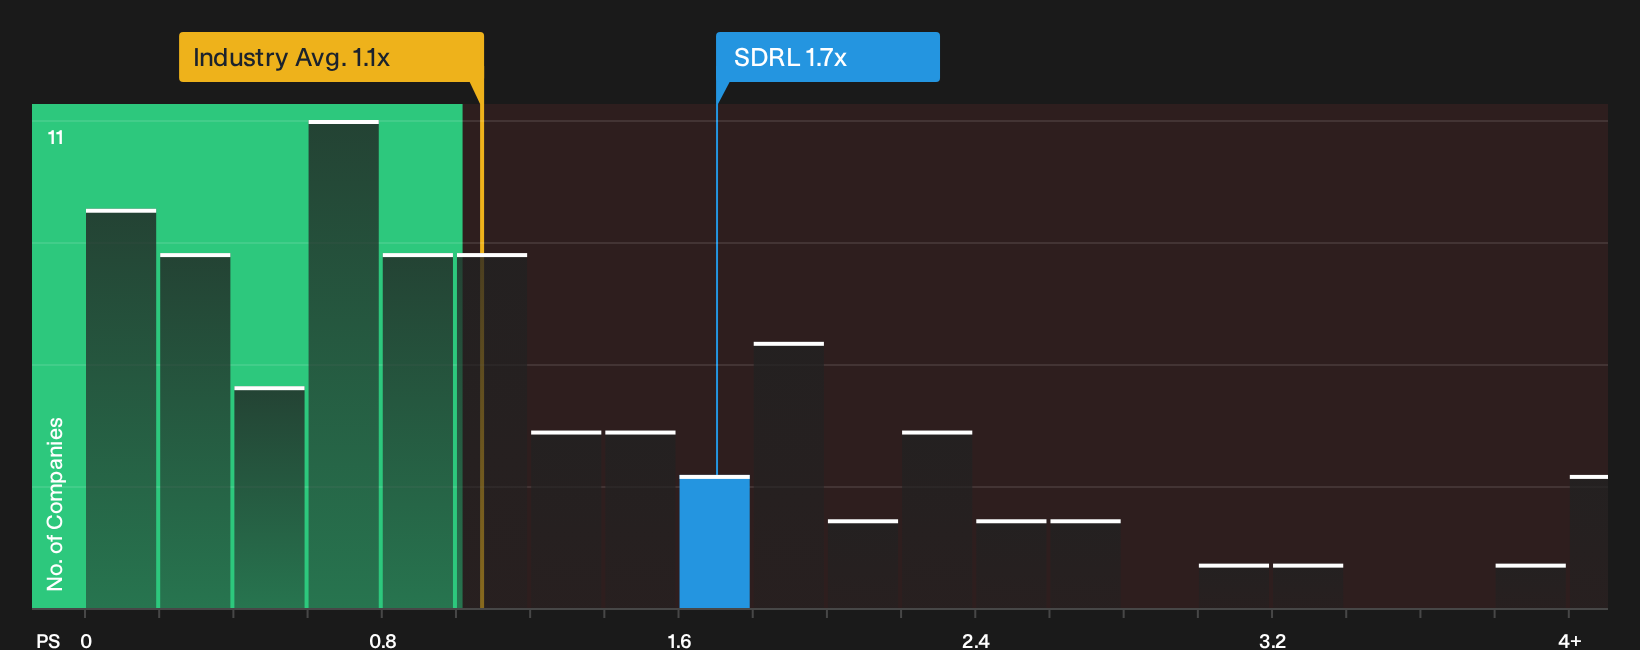
Seadrill might look appealing on a $54.00 fair value from the narrative, but its current P/S ratio of 1.7x sits well above the US Energy Services industry average of 1.1x, the peer average of 1.1x, and even the fair ratio of 1.1x that the market could move toward.
If sentiment cools or expectations reset, that gap in P/S multiples could compress and eat into return potential before any improvement in earnings shows up in the numbers. How comfortable are you paying a premium today for a business that is still loss making?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like these only matter if you pressure test them yourself and move before sentiment shifts away from you. Start by weighing the upside case in the 2 key rewards
Ready for more Seadrill sized ideas?
If Seadrill has you rethinking your playbook, do not stop at one ticker. Broader context sharpens judgment and often surfaces better risk reward trades.
- Spot potential breakout candidates early by scanning the 9 elite penny stocks with strong financials that already pair tiny share prices with stronger balance sheets and fundamentals.
- Zero in on quality at a discount by running through the 19 high quality undiscovered gems that combine solid cash generation with quieter market attention.
- Protect the downside first by reviewing the 29 resilient stocks with low risk scores that score well on resilience, volatility, and financial strength before sentiment crowds in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com