


EN
Should Mixed Earnings Require Action From MSA Safety Stock Investors
- MSA Safety reported past third quarter 2026 sales of US$536.43 million with net income of US$58.4 million, alongside nine month sales of US$1.50b and net income of US$215.86 million.
- The firm paired this mixed profitability picture with US$58.31 million of completed share repurchases and continued common and preferred dividends, which highlights an ongoing focus on capital returns alongside operating execution.
- Next, the focus will shift to how MSA Safety's higher year to date earnings and ongoing buybacks may influence its investment narrative.
MSA Safety Investment Narrative Recap
For MSA Safety, the core belief is that a higher value mix in detection and connected safety can support earnings resilience even when some regions are soft. The latest quarter fits that story only partially. Sales reached US$536.43 million, but quarterly net income moved the other way, so the key short term question is how much margin pressure persists.
The near term swing factor is whether cost inflation and Middle East related headwinds remain manageable. Nine month net income of US$215.86 million suggests the year is tracking ahead of the prior period, which helps the longer term mix and SCBA replacement catalysts. The biggest risk still looks like sustained margin compression rather than demand falling away.
The most relevant update here is the earnings release itself, because it links directly to those margin and mix catalysts. Quarterly sales of US$536.43 million compare with US$468.45 million a year earlier, while net income moved from US$69.61 million to US$58.4 million. That mix of higher revenue and softer profit puts the cost base under the microscope.
The same report shows nine month sales of US$1.50b and net income of US$215.86 million. This ties into the story of connected solutions, detection weighting and upcoming SCBA replacement needs. If gross margins continue to moderate from earlier 2026 levels, cost discipline and pricing on higher spec products become the operational swing factors that either support or delay those catalysts.
MSA Safety's analyst narrative points to forecast revenues of US$2.5b and earnings of US$409.6 million by 2029, based on an assumed yearly top line expansion of 8.8% and an expected earnings increase of about US$95.7 million from US$313.9 million today.
Uncover why MSA Safety's fair value indicates a 23% potential upside to its current price that could narrow quickly.
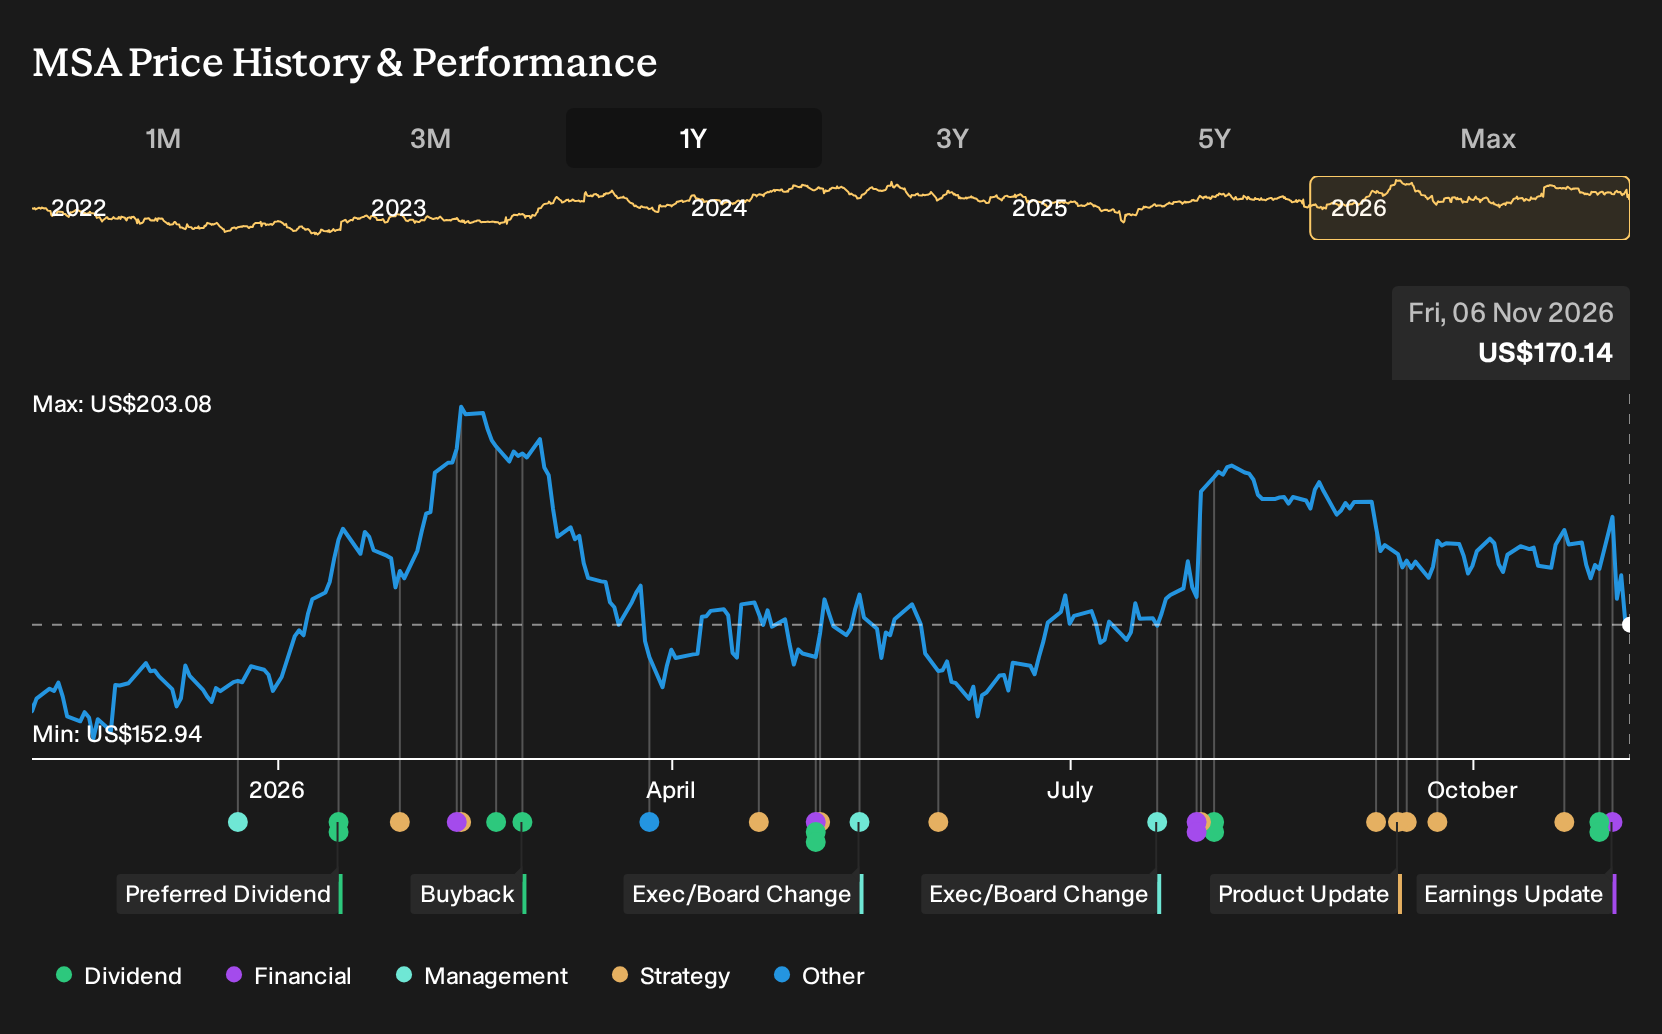
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$209 per share at the low end to about US$327 at the high end, which already shows how far opinions on MSA Safety can stretch. When you add Middle East exposure, cost pressures and the pending SCBA replacement cycle, investor views can legitimately diverge. Use that spread as a prompt to test several alternative angles before deciding how MSA Safety fits your own approach.
Explore another MSA Safety fair value estimate, including one that suggests it could be worth just $209.14!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your MSA Safety research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MSA Safety. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MSA Safety's overall financial health at a glance.
Looking for more investment ideas beyond MSA Safety?
If the MSA Safety story has you thinking about portfolio balance, use that same lens to survey a broader watchlist. The Simply Wall St Screener can help you filter for companies with financial traits that match how you like to take risk, rather than leaving you to scroll through tickers at random.
- For investors who want income that does more of the heavy lifting, consider steady payers through the 8 dividend fortresses and see which yields line up with your targets.
- If capital protection sits higher on your priority list, filter for resilience with the 29 resilient stocks with low risk scores to find businesses where balance sheets and risk scores take center stage.
- When you want upside but still care about fundamentals, search for quality at a discount using the 39 high quality undervalued stocks and spot candidates that may merit a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com