


EN
What BMW's Profit Warning Means For Shareholders
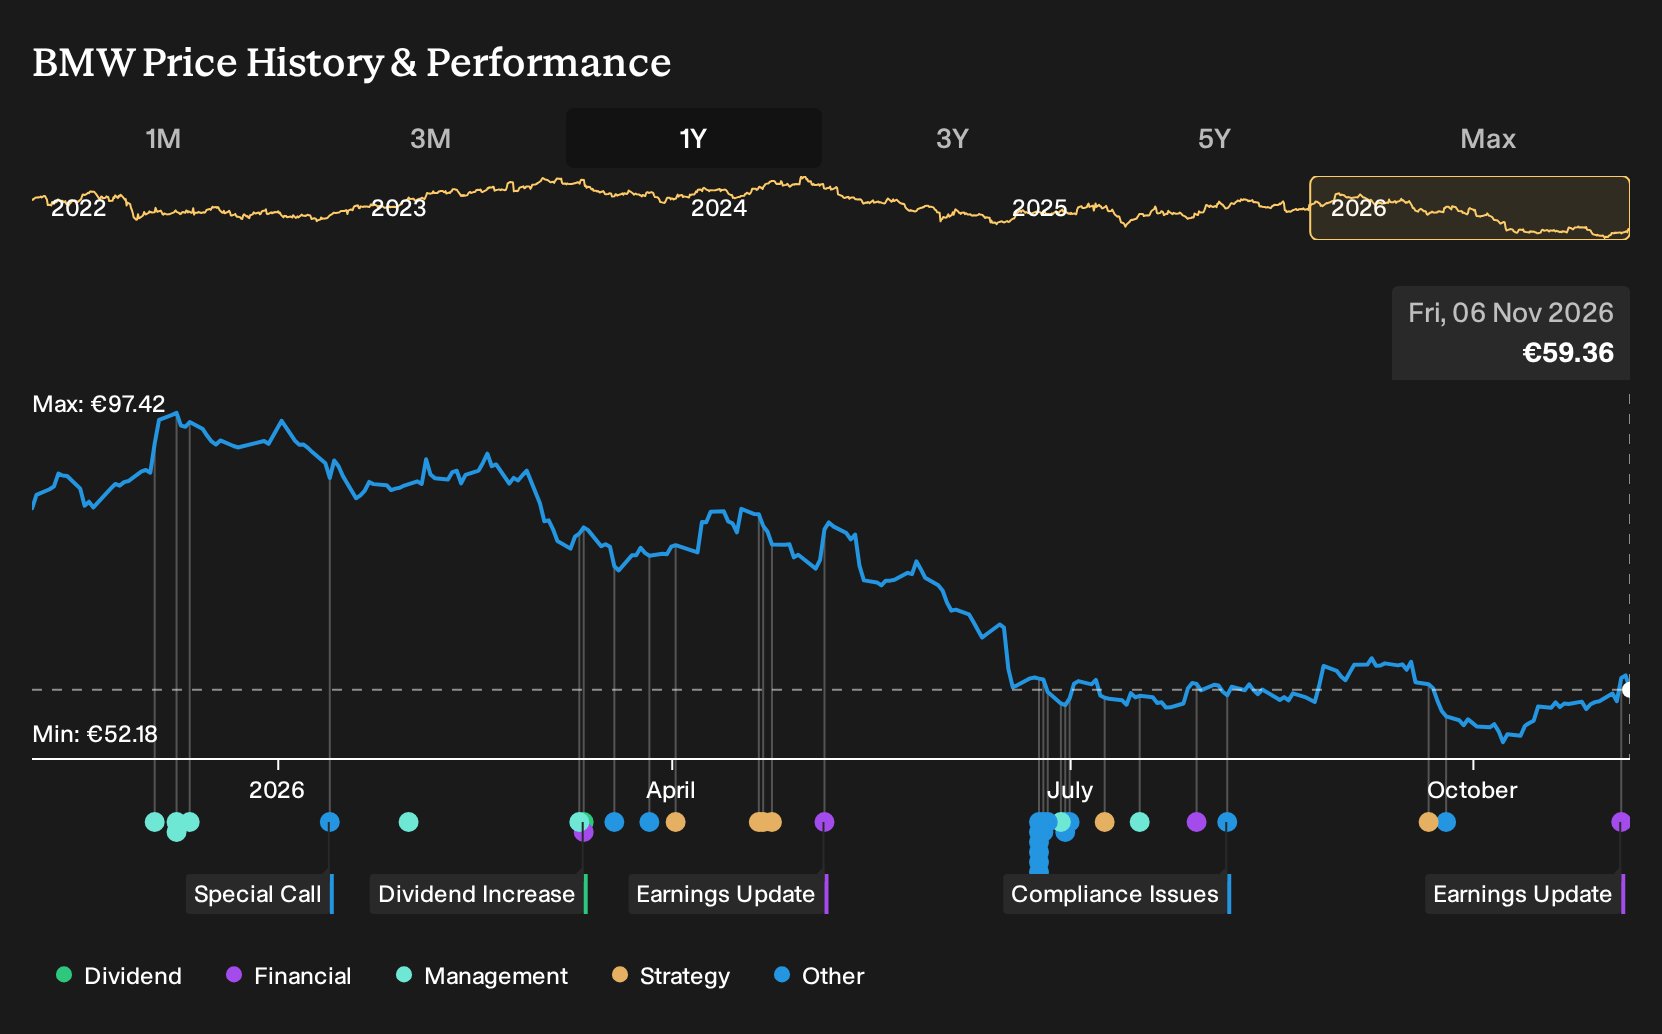
- Bayerische Motoren Werke reported third quarter 2026 sales of €20,292 million and net income of €1,461 million, alongside a reduced automotive profit outlook and a core margin range that now runs from a slight loss to a slight profit.
- The second profit warning of 2026 highlights that weaker China contribution and higher restructuring costs, including workforce reductions, are weighing on BMW's earnings profile.
- We will now examine how Bayerische Motoren Werke's weaker profit outlook and China-related pressure could reshape its wider investment narrative.
Compare Bayerische Motoren Werke's margin reset with other carmakers facing similar pressure in China by scanning our curated list of 225 high quality undervalued stocks.
Bayerische Motoren Werke Investment Narrative Recap
Bayerische Motoren Werke shareholders effectively need to believe the restructuring and product pipeline can offset weaker China economics and tariff costs. The core short term swing factor is execution on cost cuts while keeping premium pricing power intact. The latest quarter, with lower sales and earnings, puts more pressure on that efficiency story rather than changing it.
The biggest immediate risk still sits in China, where pricing pressure and softer volumes are already visible in the margin reset. Management now signals an automotive margin that could hover around breakeven, so any further demand shock or tariff hit would bite quickly. On the upside, new BEV launches and a leaner cost base remain the main operational catalysts.
The clearest piece of news to track against those catalysts is BMW reaffirming free cash flow guidance above €2.5b and an operational EBIT margin above 2% for 2026, despite lower volume expectations. That indicates management is leaning hard on restructuring, capital discipline and mix, rather than counting on a rapid rebound in unit sales.
For investors, that confirmation makes execution on the €1.25b EBIT improvement plan central. Workforce reductions, process automation and supplier standardization now do the heavy lifting in the investment narrative. If those measures land on time while Neue Klasse and iX3 volumes in Europe and China build as planned, the thesis around margin repair and cash generation stays intact, even with China risk still front and center.
Bayerische Motoren Werke's current analyst storyline points to revenues of €139.4b and earnings of €7.0b by 2029. That implies revenue growth of 2.9% per year and an earnings increase of about €0.7b from €6.3b today.
Uncover why Bayerische Motoren Werke's fair value indicates a 17% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view zooms in on Bayerische Motoren Werke's slower shift away from combustion engines. The most cautious analysts were pencilling in roughly flat revenue at about €129.3b by 2029 and earnings slipping toward €5.3b. Those pre news forecasts sketch a far harsher margin story. Use that as a reference point and explore several competing narratives before deciding what this latest profit warning might change.
Explore 5 other Bayerische Motoren Werke fair value estimates, including one that suggests it could be worth just €60.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bayerische Motoren Werke research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Bayerische Motoren Werke. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bayerische Motoren Werke's overall financial health at a glance.
Looking for more investment ideas beyond Bayerische Motoren Werke?
If the BMW story has you reassessing your portfolio, it can help to line it up against other opportunities with different risk and income profiles. Use the Simply Wall St Screener to broaden your watchlist and pressure test your convictions against a wider set of listed businesses.
- If capital preservation comes first for you, start with companies that pair sturdier financial positions with steadier operations by reviewing our 212 resilient stocks with low risk scores.
- If income is the priority, focus on businesses that currently offer higher yields and more resilient payout histories through our curated 232 dividend fortresses.
- If you want a broader hunting ground for potential mispricing, scan our hand picked 588 high quality undiscovered gems and see which underfollowed stocks deserve a deeper look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com