


EN
How Investors May Respond To Grindr (GRND) Revenue Growth And Quarterly Loss
- Grindr reported Q3 2026 sales of US$141.38 million compared with US$115.77 million a year earlier, while results shifted from a US$30.83 million profit to a net loss of US$6.6 million and earnings per share moved from earnings of US$0.16 to a loss of US$0.04.
- Across the first nine months of 2026, Grindr generated US$409.46 million in sales versus US$313.92 million a year before, yet net income declined from US$74.49 million to US$37.89 million, which suggests rising cost or investment pressure even as the platform brought in higher revenue.
- This raises the question of how Grindr's investment narrative is affected by higher revenue paired with a swing to loss in the latest quarter.
Scan how Grindr's latest earnings twist compares with other platforms by reviewing a curated set of 39 high quality undervalued stocks that pair solid fundamentals with compressed expectations.
What Is Grindr's Investment Narrative?
To own Grindr, you have to buy into a simple idea. The platform has a focused LGBTQ user base that supports both ad revenue and premium subscriptions, and recent figures show that people are still spending on the service. The Q3 2026 swing from a profit to a US$6.6 million loss interrupts the clean profitability story, yet the first nine months still show US$37.89 million in net income. That mix keeps the near term centered on execution, not just user growth.
The real question is whether Grindr can fund heavier product, trust and safety, and marketing spend without stretching an already leveraged balance sheet further. Analysts currently see meaningful upside from here and expect strong earnings expansion, so this quarter matters for confidence in that path. In the short term, the loss puts more scrutiny on cost discipline, pricing power on subscriptions, and how capital intensive Grindr’s next phase really becomes.
Yet there is one pressure point in Grindr’s story that deserves much closer attention once you look at ...
There's only one way to know the right time to buy, sell or hold Grindr. Head to Simply Wall St's company report for the latest analysis of Grindr's Fair Value.
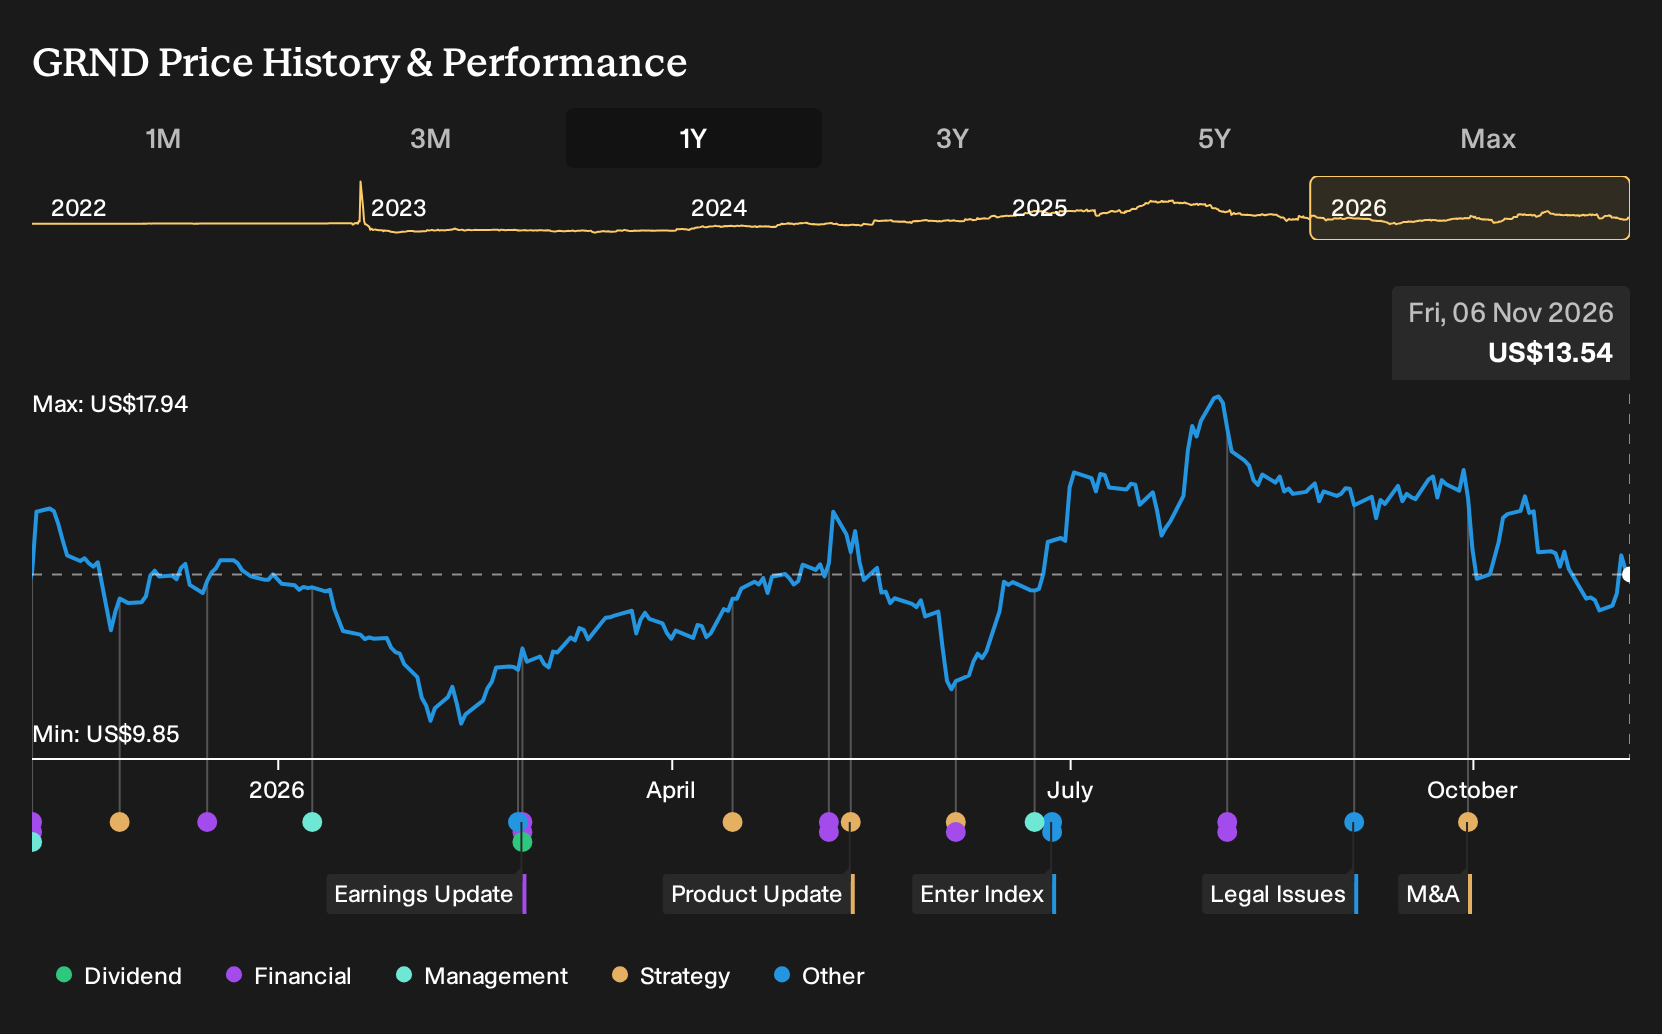
Exploring Other Perspectives
One alternate view puts Grindr’s healthcare push at the center of the story. The most optimistic analysts, using pre earnings data, were modeling revenue of US$856.1 million and earnings of US$193.6 million by 2029. If this quarter challenges that path, those forecasts and the upbeat narrative may shift quite a bit.
Explore 4 other Grindr fair value estimates, including one that suggests as much as 77854% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Grindr research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Grindr. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Grindr's overall financial health at a glance.
Looking For More Investment Ideas Beyond Grindr?
If Grindr's latest results have you rethinking concentration risk, it can help to scan a wider field of opportunities that match your own preference for quality, risk level, and income potential.
- If you want resilient businesses that aim to prioritise capital strength, filter for companies on the list of solid balance sheet and fundamentals (24 results) and see which ones fit your standards.
- For those who care most about stability and lower downside risk, narrow your search using a 29 resilient stocks with low risk scores that focuses on companies with more measured risk profiles.
- If you prefer quality stories that are not yet crowded, run through a 19 high quality undiscovered gems to find businesses with strong fundamentals that the market may be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com