


EN
How Investors Are Reacting To NOV (NOV) Stronger Earnings Guidance Flat
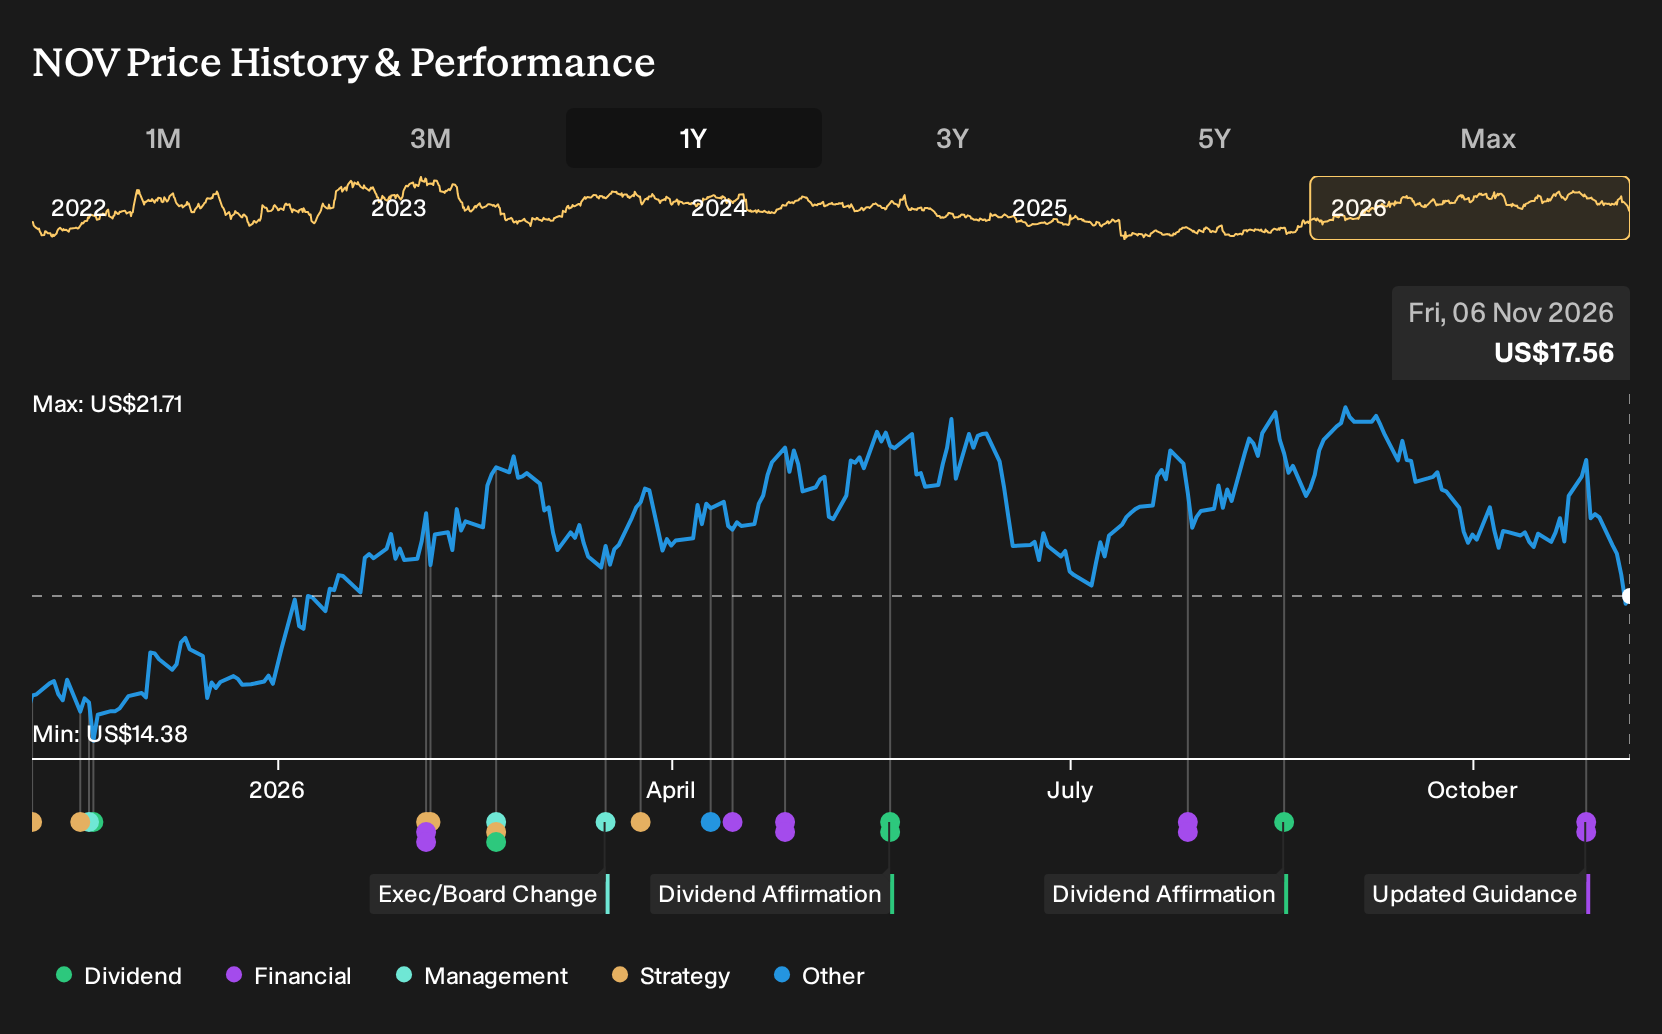
- NOV Inc. reported third quarter 2026 revenue of US$2,226 million and net income of US$90 million, with basic and diluted EPS from continuing operations of US$0.25. The company guided to roughly flat consolidated revenue year over year for the fourth quarter.
- The nine-month 2026 figures show revenue of US$6,412 million and net income of US$221 million, so investors can now weigh stronger quarterly profitability against a full-year picture that still looks relatively steady on sales and earnings.
- We will look at how NOV’s investment narrative aligns with higher quarterly earnings per share alongside guidance for roughly flat near-term revenue.
Compare NOV’s flat revenue outlook and rising EPS with a curated set of companies that pair resilient top lines with stronger earnings momentum using 39 high quality undervalued stocks.
NOV Investment Narrative Recap
NOV stock largely hinges on your view of offshore and international unconventional activity, and whether that backlog can sustain earnings when headline revenue is steady. The latest quarter showed higher EPS alongside relatively stable sales, while management still guides to roughly flat fourth quarter revenue. That mix keeps the focus squarely on execution, pricing discipline and cost control.
The short term swing factor is whether NOV can protect margins against rising tariffs, freight and input costs while working through its deepwater and digital backlog. The biggest risk remains operational hiccups in key regions or softer upstream spending, which could keep revenue and profitability tracking closer to the current muted guidance.
The most relevant update is the third quarter 2026 print. NOV posted US$2,226 million of quarterly revenue compared with US$2,176 million a year earlier, and net income of US$90 million compared with US$42 million. Basic and diluted EPS from continuing operations were US$0.25, up from US$0.11, which indicates that the recent earnings story is about more than just volume.
Across the first nine months of 2026, revenue was US$6,412 million compared with US$6,467 million, while net income was US$221 million compared with US$223 million. That relatively steady year to date profile, paired with stronger quarterly profitability, creates a clear test. Investors can watch whether NOV converts its subsea, deepwater and digital opportunities into sustained margin improvement against the tariff and regional disruption risks already flagged.
NOV’s current analyst story points to US$9.6b of revenue and US$538.9 million of earnings by 2029, with that outcome built on 3.4% yearly top line growth and an increase in earnings of about US$444 million from US$95.0 million today.
Uncover why NOV's fair value indicates a 26% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view says the bigger issue for NOV is not tariffs but structurally low profitability, with gross margins near 20.3% and free cash flow margins around 3.4% to 3.6% before this latest quarter. The most cautious analysts were only baking in roughly US$9.4b of 2029 revenue and US$553.6 million of earnings, so the new flat Q4 guidance and stronger recent EPS could push those expectations in either direction. Use this spread in opinions as a prompt to compare several narratives before you decide how NOV fits your portfolio.
Explore 2 other NOV fair value estimates, including one that suggests it could be worth just $22.18!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your NOV research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NOV. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NOV's overall financial health at a glance.
Looking for more investment ideas beyond NOV?
Once you have an initial view on NOV, it can help to compare it with other companies that have different risk, quality and income profiles. The Simply Wall St Screener lets you quickly filter across thousands of stocks so you can line up alternatives that better match your own goals and tolerance for volatility.
- If capital preservation is front of mind, start with companies that score well on resilience and see how they stack up using 29 resilient stocks with low risk scores.
- If a sturdy balance sheet matters more to you than rapid expansion, line up candidates with stronger fundamentals through the list of solid balance sheet and fundamentals (24 results).
- If you want to focus on valuation and quality together, compare NOV with a curated pool of opportunities screened by both metrics via the 39 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com