


EN
Atmus Filtration Technologies (ATMU) Earnings Beat And Buyback Put Valuation Back In Focus
Atmus Filtration Technologies (ATMU) just delivered third quarter 2026 results that topped analyst forecasts on both revenue and earnings, raised full year guidance, and introduced a new US$300 million share repurchase plan.
The stronger than expected Q3 update and fresh US$300 million buyback authorization have come alongside a sharp swing in sentiment. Atmus Filtration Technologies has posted a 1 day share price return of 9.6% and a 7 day share price return of 10.8% after a softer year to date patch where the share price return is down 3.5% and the 90 day share price return is slightly negative. Meanwhile, the 1 year total shareholder return of 6.1% and very large 3 year total shareholder return of about 17x suggest longer term holders have still been well rewarded as earnings, acquisitions and capital returns reshape expectations.
Spot similar earnings and buyback stories by scanning our curated list of 39 high quality undervalued stocks, which also pair cash generation with shareholder returns.After a double digit rebound and a fresh US$300 million buyback in play, the question now is whether Atmus Filtration Technologies still offers an attractive entry point or if most of the easy upside has already been priced in.
Most Popular Narrative: 22% Undervalued
Atmus Filtration Technologies last closed at $50.6 while the most followed narrative pegs fair value at $65.2, which frames today’s bounce against a still sizeable valuation gap based on longer term earnings and cash flow expectations.
The expansion into industrial filtration through Koch Filter, with Industrial Solutions guided to US$155 million to US$165 million of 2026 revenue at roughly 20% EBITDA margins, gives Atmus a new platform tied to data centers, healthcare and HVAC that can support revenue growth and margin diversification.
See why 2 investors see Atmus Filtration Technologies as 22% undervalued.
This narrative uses a 9.1% discount rate to bring those future cash flows back to today, then compares that result to the current share price. The 22.4% discount to the $65.2 fair value estimate suggests the market is valuing Atmus Filtration Technologies below what these earnings and margin assumptions imply, even after factoring in execution risks around Koch Filter integration and sustaining record quarterly performance.
Result: Fair Value of $65.2 (UNDERVALUED)
Still, the upbeat Atmus Filtration Technologies narrative runs into trouble if record US$528 million quarterly sales prove hard to repeat or if Koch Filter margins fall short.
Find out about the key risks to this Atmus Filtration Technologies narrative.
Another View: Cash Flow Puts Atmus Above Fair Value
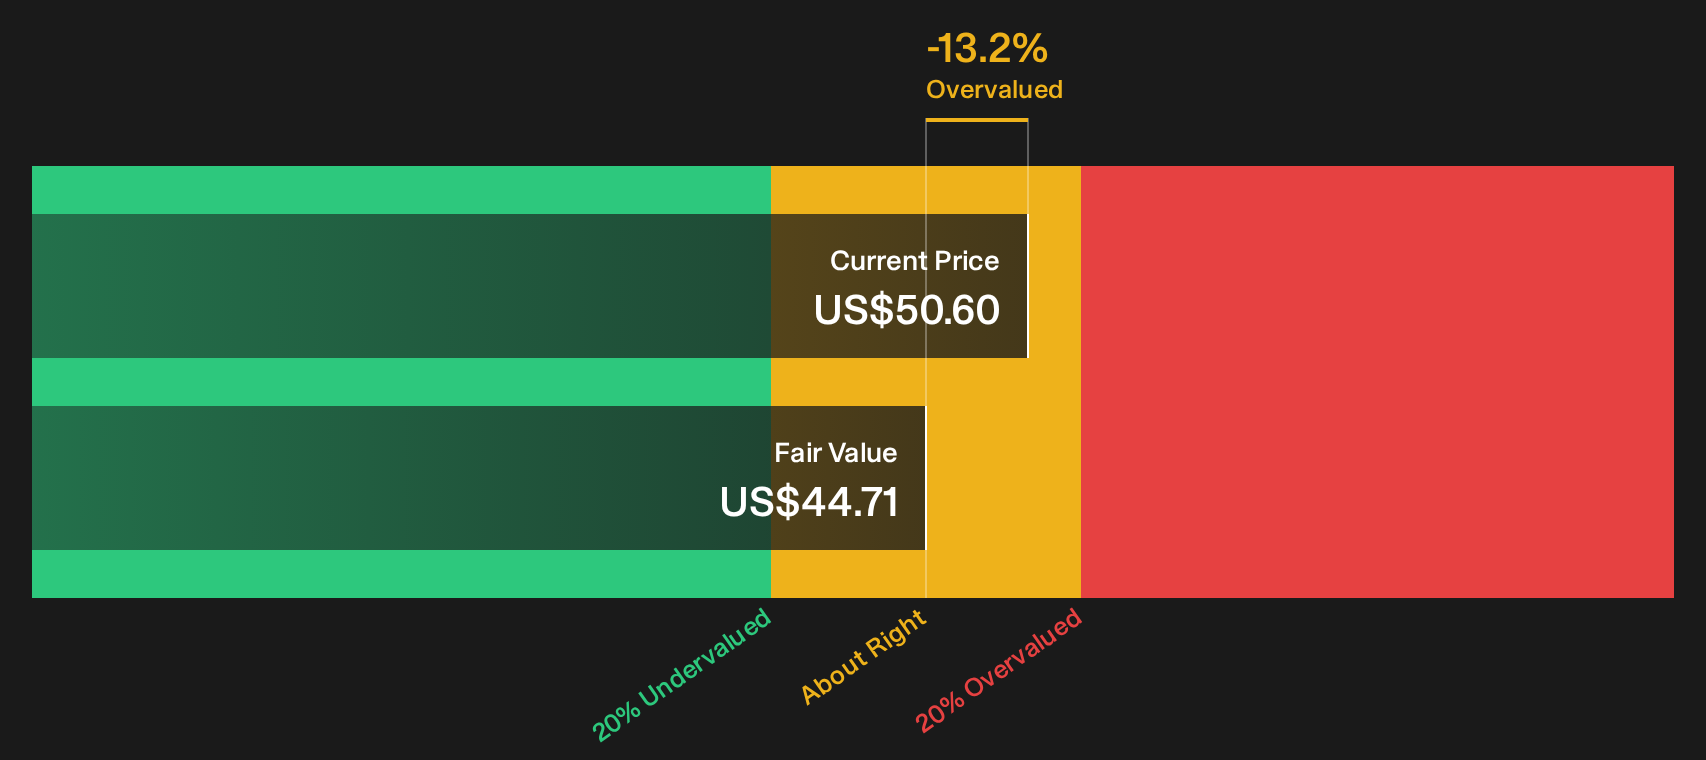
The popular narrative says Atmus Filtration Technologies is undervalued versus a $65.2 fair value, yet the SWS DCF model points in the opposite direction. On that cash flow view, the stock at $50.6 screens as overvalued relative to an estimated future cash flow value of $44.71. That raises a simple question for investors: Which story carries more weight, the earnings narrative or the cash flows?
Our DCF model rests on explicit long term cash flow assumptions, discount rates and terminal values that can shift as new data comes in. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Atmus Filtration Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Atmus Filtration Technologies so far. If you want to act before sentiment settles, weigh the potential upside and downside yourself by reviewing the 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Atmus Filtration Technologies?
If Atmus Filtration Technologies has your attention, do not stop here. Fresh opportunities often show up first in the data, not the headlines.
- Target steadier candidates by checking a 29 resilient stocks with low risk scores that filters for resilience when broader conditions feel uncertain.
- Hunt for mispriced potential through a 19 high quality undiscovered gems that focuses on under-the-radar businesses with solid fundamentals.
- Prioritize financial strength by reviewing a list of solid balance sheet and fundamentals (24 results) so you focus on companies with healthier foundations backing their share prices.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com