


EN
CenterPoint Energy (CNP) Earnings Put Its Valuation Back In Focus
CenterPoint Energy (CNP) just released third quarter and year to date results, with sales, revenue and net income all above the prior year, putting fresh attention on how the utility is executing.
Investors have been weighing those higher year to date earnings against a mixed price pattern, with CenterPoint Energy’s share price up 5.5% over the past month but down over the past week, while the 3 year total shareholder return of 61.9% points to strong longer term compounding.
Scan for other regulated utilities showing similar earnings traction by reviewing our hand picked 42 power grid technology and infrastructure stocks alongside the latest numbers from CenterPoint Energy.
CenterPoint Energy’s stock has climbed over the past month yet still trades below the average analyst target, while one intrinsic model points to a premium. Is the market’s caution on this utility actually warranted?
Most Popular Narrative: 8% Undervalued
On the most followed view of CenterPoint Energy, the fair value sits at $44.41 compared with the latest close of $40.66. This puts the spotlight on what needs to go right to justify that gap.
CenterPoint Energy expects to grow non-GAAP EPS at the mid to high end of a 7% to 9% range annually through 2028 and through 2035, which ties long dated earnings growth directly to its US$66.7b capital investment plan and large-load expansion and therefore to future revenue and earnings.
See why 6 investors see CenterPoint Energy as 8% undervalued.
Result: Fair Value of $44.41 (UNDERVALUED)
Still, the CenterPoint Energy story can break if the premium P/E multiple contracts, or if higher funding and dilution costs drag on future earnings power.
Find out about the key risks to this CenterPoint Energy narrative.
Another View: CenterPoint Energy Through The P/E Lens
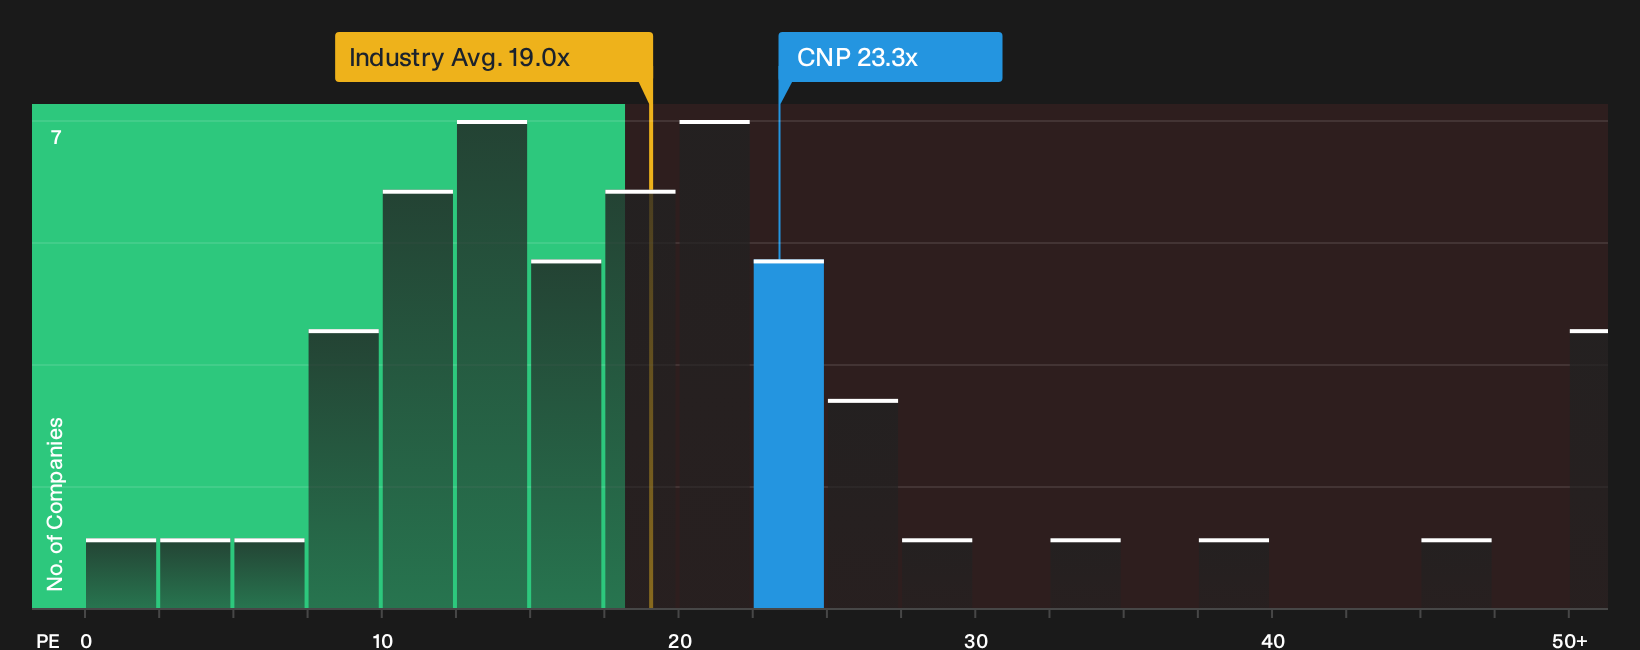
The first narrative leans on a fair value of $44.41, yet CenterPoint Energy currently trades on a P/E of 23.3x compared with 21.5x for peers and 19x for the broader Integrated Utilities group. Its fair ratio sits at 22.4x.
This mix of a peer and industry premium, combined with a P/E that is above the fair ratio the market could gravitate toward, points to valuation risk if sentiment cools or growth expectations ease. How comfortable are you paying extra for this utility on those terms?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on CenterPoint Energy is split, with fresh earnings strength balanced against valuation questions. Move quickly, test the numbers and shape your own view using our breakdown of 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CenterPoint Energy?
Do not stop with one utility. Broaden your watchlist right now by testing different angles on quality, value and income across the wider market using focused screeners.
- Target potential mispricings by scanning companies that combine quality fundamentals with attractive valuations through the 39 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (24 results) that highlights businesses with stronger financial footing than most.
- Hunt for future contenders by checking the 19 high quality undiscovered gems that wider markets may not be paying close attention to yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com